
Dow (DOW) Stock May Be A Bargain On Strong Q3 Earnings
Dow Inc. has rallied strongly in 2026, which puts a fresh spotlight on whether the current share price lines up with the sales the business is generating. After a run like this, the key issue for investors is how much revenue power the market is assuming Dow can sustain and build on from here.
- The stock is up 34.4% year to date, so anyone buying or holding now is implicitly making a much bigger call on the value of Dow's sales base than at the start of the year.
- Recent earnings showed higher profit and lower debt, which can influence how investors think about the quality, staying power and risk profile of those sales.
- Your read on Dow is one view; the desks covering it have another. See what analysts think Dow's shares could be worth.
The stock's next move may depend on whether Dow's current share price can be squared with the level and trajectory of its sales.
If you want to test whether Dow's recent share price jump lines up with its sales story, you can run the same check across a wider set of 28 high quality undervalued stocks.
Is Dow a Bargain on Sales?
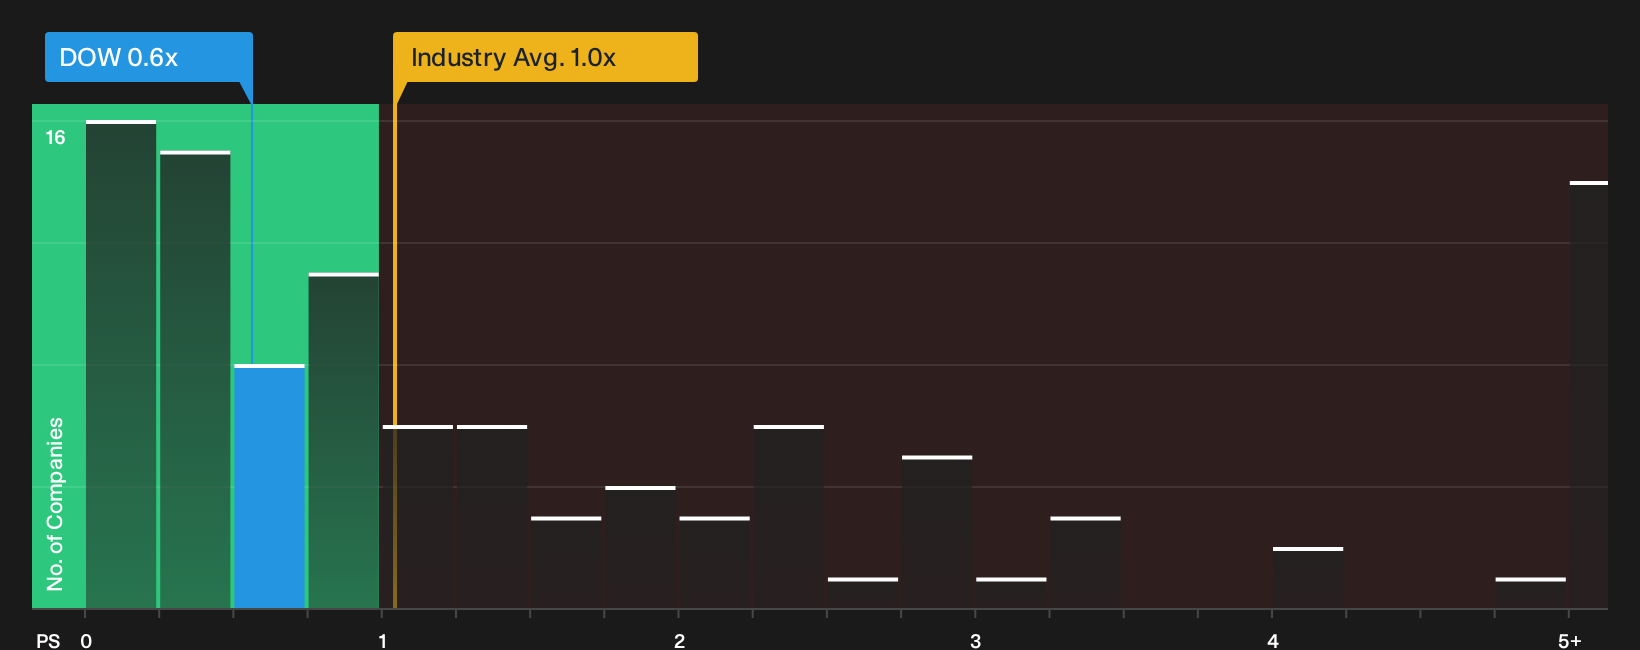
P/S fits Dow because investors are weighing the value of every dollar of sales in a sector where earnings can move around more than revenue. On that score, the stock trades on a P/S of roughly 0.6x, compared with an industry average near 1.0x and a peer group closer to 1.2x. That gap indicates the market is pricing Dow's revenue stream at a discount to many other chemicals companies.
Because the fair multiple model blends the sector, margins, growth profile and risk into a tailored benchmark, Dow's current P/S also comes in below what that framework would imply. The strong Q3 2026 update, with earnings ahead of forecasts and debt lower, has not closed that gap, so the share price still reflects a lower value per dollar of sales than those reference points suggest. If you think Dow's recent execution on revenue quality and cash generation can be maintained, that mismatch on the P/S ratio could matter for your assessment of upside from here. Explore the numbers behind Dow's P/S valuation.
The Dow Narrative: What Would Justify Today's Price?
Simply Wall St Narratives for Dow pick up where the P/S puzzle leaves off by explaining which combinations of future growth, margins and earnings would need to occur for Dow's stock to be worth materially more or less than today. These Narratives are available on the Community page. Each scenario links a fair value estimate to a particular view of Dow's potential catalysts and key risks, allowing you to track over time which version of events is actually unfolding.
Community views on Dow are split between those who see more value in the self help story and those who think the current price already reflects it.
Bull case: roughly fairly valued
"Dow has increased its 2026 outlook for self help benefits to more than US$1.3b and continues to target over US$3b of largely structural improvements by 2029..."
Discover why this Narrative puts Dow at roughly fairly valued.
Bear case: 9% overvalued
"Bearish analysts expect Dow's exposure to traditional petrochemical chains and ongoing macro volatility, including weaker polyethylene pricing, to keep pressure on earnings and limit the benefit from self-help programs..."
Explore why this Narrative puts Dow at 9% overvalued.
Dow's valuation story leaves one key issue unresolved
Price and sales only tell part of the picture for Dow, because the research screens backing this work have also highlighted specific risk checks that need a closer look. Take a closer look at 2 warning signs (1 major) before settling on a valuation.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com