
What Chugai Pharmaceutical (TSE:4519)'s Enspryng Approval Means For Shareholders
- Genentech, a Roche subsidiary, has received U.S. approval for Enspryng in thyroid eye disease, which is expected to generate royalty and profit-sharing income for Chugai Pharmaceutical through their alliance structure.
- The added thyroid eye disease indication broadens the potential use of Enspryng within Chugai Pharmaceutical’s biologics portfolio and links future cash inflow expectations more closely to execution on high-value specialty therapies.
- We will examine how Chugai Pharmaceutical's investment narrative is affected by expected royalty inflows from Enspryng's new thyroid eye disease approval.
Compare Chugai Pharmaceutical's royalty story with a curated group of cash generative healthcare stocks by scanning the 14 high quality undervalued stocks that may be trading below intrinsic value on Simply Wall St.
Chugai Pharmaceutical Investment Narrative Recap
Owning Chugai Pharmaceutical means believing its focus on biologics, oncology and specialty immunology can offset reliance on a few big earners like Hemlibra and Actemra. The key near term driver is whether the pipeline, co-developed assets with Roche and existing products can keep cash generation resilient as pricing pressure and patent timing remain front of mind.
The new Enspryng thyroid eye disease indication supports that story only at the margin. It points to better product depth rather than a single defining shift. The biggest risk stays the same for now. Any slowdown in late stage R&D progress or sharper drug price revisions could matter more to earnings than this approval.
The Enspryng approval for thyroid eye disease is the announcement that ties most clearly into this royalty angle. It reinforces Chugai Pharmaceutical's push into high value biologics that can sit alongside Hemlibra, Actemra and newer agents like Vabysmo in the portfolio. Investors are essentially watching whether these kinds of specialty therapies can keep profit quality strong.
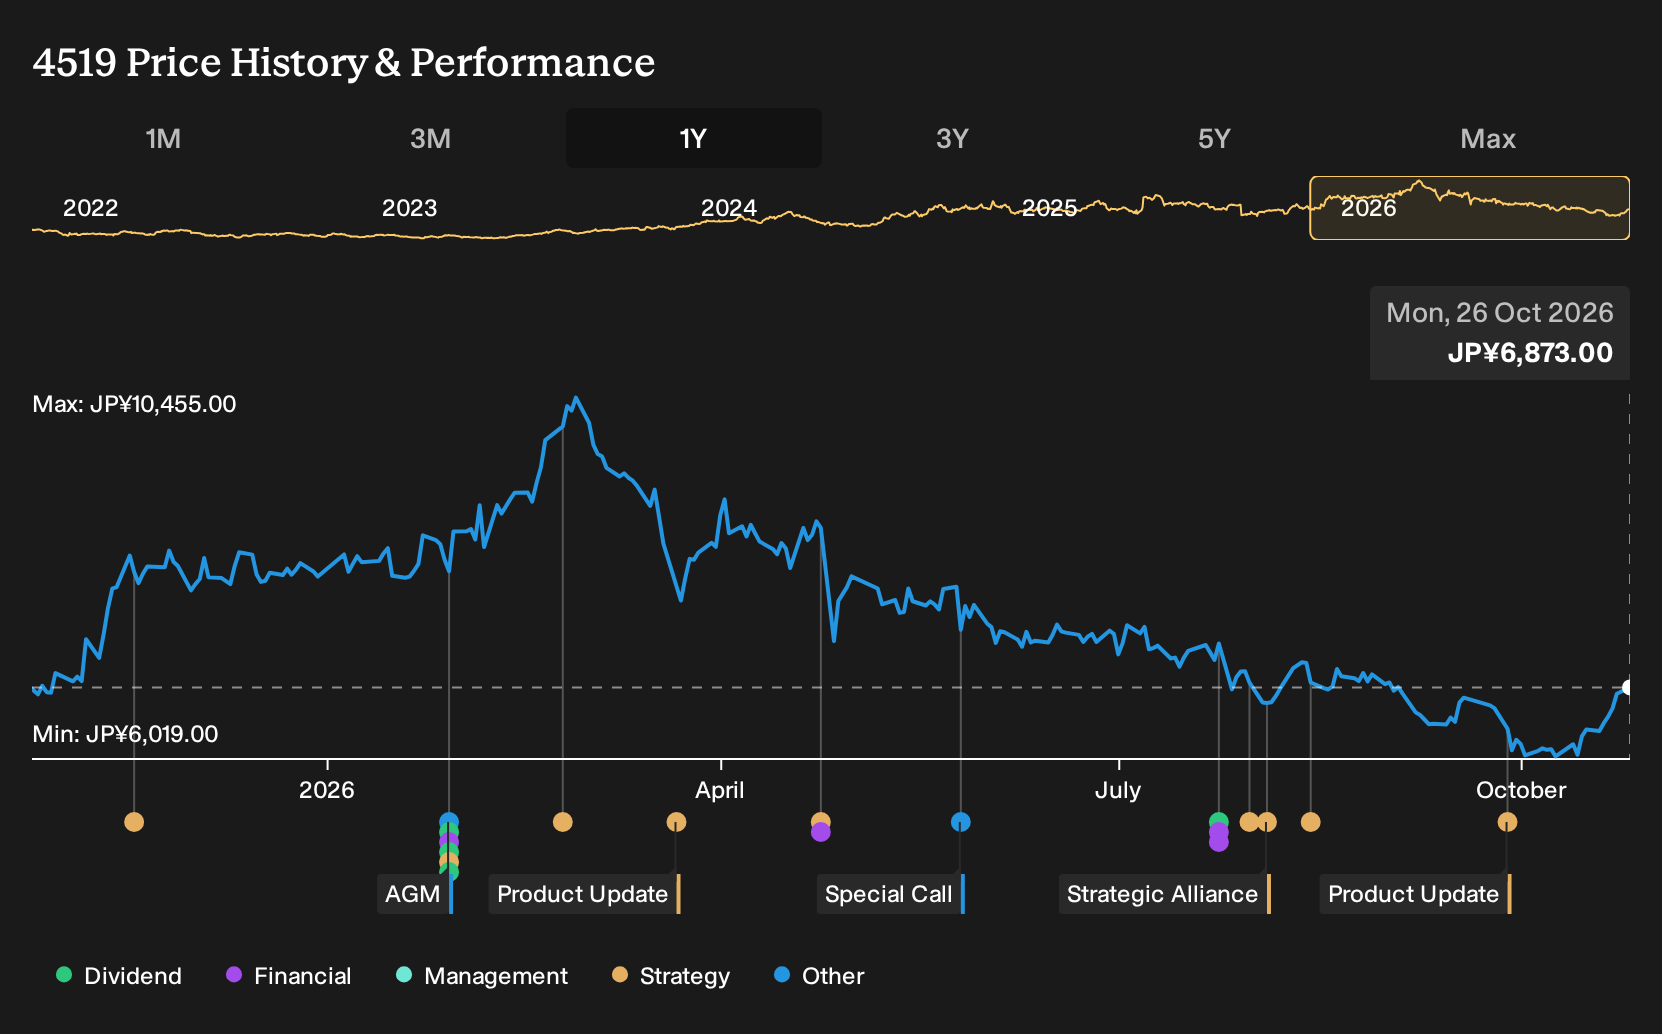
This update also arrives while Chugai trades on a P/E of about 24x, above both the JP pharmaceuticals sector and its peer average, yet still flagged as trading below some discounted cash flow estimates. That mix of strong historic earnings growth, high return on equity and pipeline plus partner execution risk is what investors are weighing against the incremental Enspryng royalty story.
On these consensus assumptions, Chugai Pharmaceutical is modeled to reach ¥1.72b in revenue and ¥693.1b in earnings by 2029, based on forecast revenue growth of 8.6% a year and an earnings increase of ¥221.7b from earnings today of ¥471.4b.
Uncover why Chugai Pharmaceutical's fair value indicates a 26% potential upside to its current price before that discount to Chugai Pharmaceutical closes.
Exploring Other Perspectives
You might see the Enspryng thyroid eye disease news and immediately think upside for royalties, yet the most optimistic analysts already assumed a much richer Chugai Pharmaceutical story built on broader filings. Before this update, they were pencilling in revenue of ¥2,005.4b and earnings of ¥820.4b by 2029, far above the more cautious ¥1,720.2b and ¥693.1b consensus path. That gap shows how sharply views differ and why it can help to compare several narratives and decide which assumptions feel realistic to you as new data arrives.
Explore 3 other Chugai Pharmaceutical fair value estimates, including one that suggests as much as 59% upside from the current price.
Form Your Own Verdict
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Chugai Pharmaceutical research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Chugai Pharmaceutical. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Chugai Pharmaceutical's overall financial health at a glance.
Looking for more investment ideas beyond Chugai Pharmaceutical?
If you want to pressure test your view on Chugai Pharmaceutical, it can help to line it up against other businesses with different income profiles, risk levels and balance sheet strength using the Simply Wall St Screener.
- For investors who prioritise steady income over headlines, compare Chugai Pharmaceutical with companies labeled as 30 dividend fortresses that might better match a portfolio built around cash payouts.
- If capital preservation and sleep-at-night risk levels matter most to you right now, weigh up Chugai Pharmaceutical against 22 resilient stocks with low risk scores and see how the trade off between volatility and quality looks.
- For a more opportunistic watchlist of potential future leaders, cross check your Chugai Pharmaceutical thesis against 72 high quality undiscovered gems that combine solid fundamentals with lower current visibility.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com