
Is Permian Basin Royalty Trust (PBT) Overvalued As Its Monthly Cash Distribution Rises?
Argent Trust Company declared a higher monthly cash distribution for unitholders of Permian Basin Royalty Trust (PBT), supported by a final settlement payment from Blackbeard Operating and by stronger natural gas volumes and pricing on Texas Royalty properties.
Against that backdrop, Permian Basin Royalty Trust units have been strong this year, with a year to date share price return of 91.47% and a 1 year total shareholder return of 88.28%. However, the recent 7 day share price move has softened near term momentum compared with the robust 90 day share price return of 20.29%.
Spot similar income stories by scanning hand picked royalty and energy plays with the 5 dividend fortresses, which combine higher yields with balance sheet strength.Permian Basin Royalty Trust has surged while its calculated intrinsic value now sits slightly above the current unit price. Is that a thin margin of safety or a fair reflection of the risks behind this rally?
Price-to-Earnings of 96.9x: Is it justified?
Permian Basin Royalty Trust units trade on a P/E of 96.9x, which is a steep figure relative to many US stocks and suggests investors are paying a high price for each dollar of recent earnings.
The P/E ratio compares the current unit price with earnings per unit. For a royalty trust like Permian Basin Royalty Trust, this measure effectively shows how generously the market values a stream of distributions that is closely tied to oil and gas production and pricing.
When earnings have declined by 2.6% per year over the past 5 years and fell 1.7% over the last year, such a high P/E indicates the market is putting a rich tag on a business where recent profit trends have not been moving higher.
Compared with the US Oil and Gas industry average P/E of 12.5x and a peer average of 13.4x, the 96.9x multiple is far higher and signals that Permian Basin Royalty Trust units are priced far above sector and peer benchmarks.
See what the numbers say about this price — find out in our valuation breakdown.
Result: Price-to-Earnings of 96.9x (OVERVALUED)
Still, if Permian Basin Royalty Trust distributions settle at lower levels or energy prices weaken, that rich P/E could quickly look stretched.
Find out about the key risks to this Permian Basin Royalty Trust narrative.
Another View: Cash Flows Paint A Harsher Picture
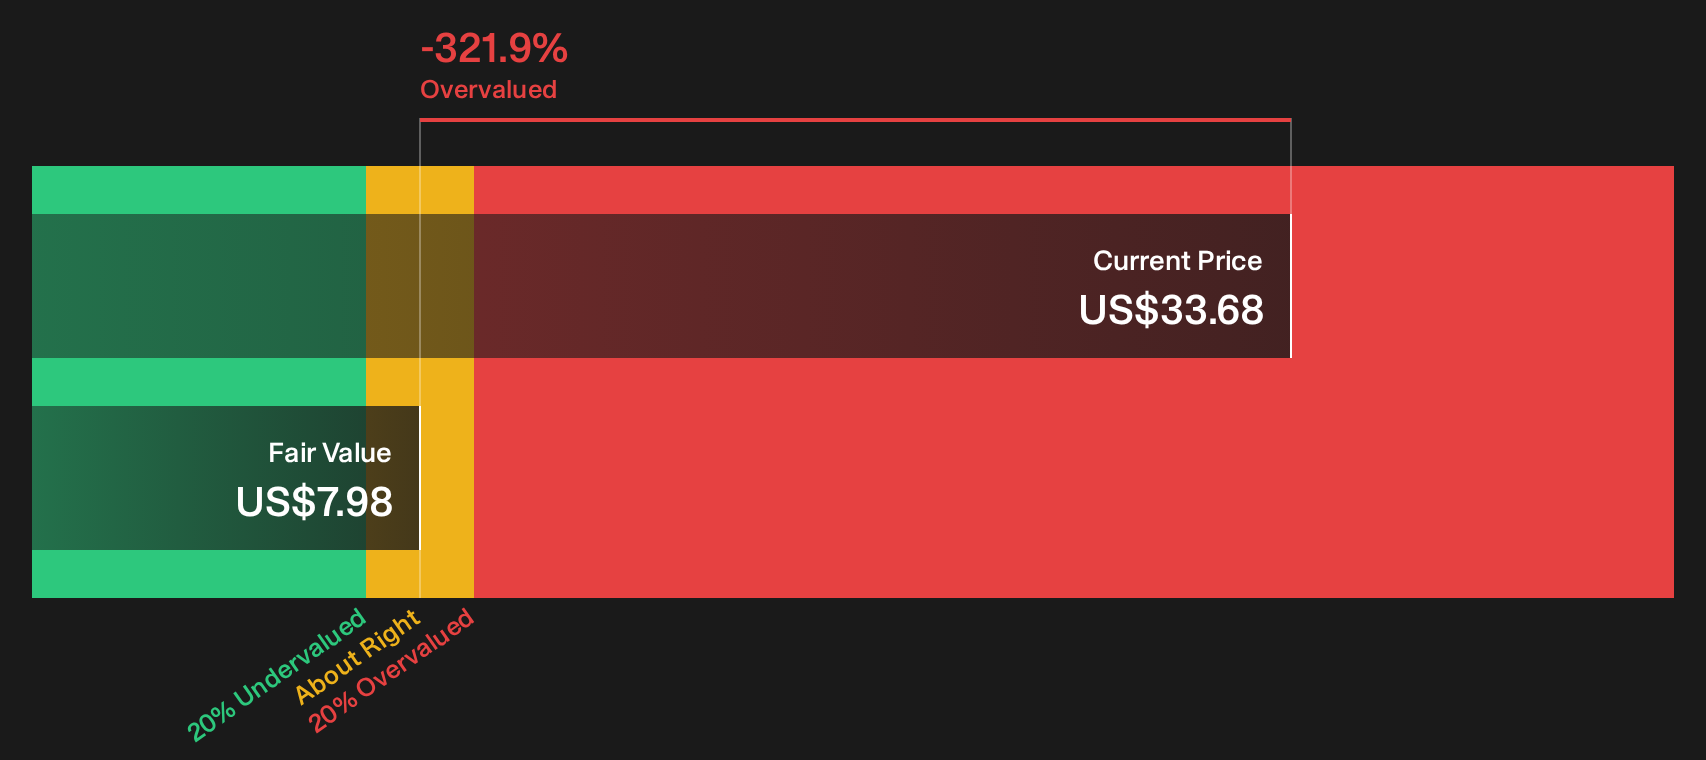
A second lens on Permian Basin Royalty Trust uses the SWS DCF model, which estimates a future cash flow value of $7.98 per unit against a recent price of $33.68. On this measure the trust screens as heavily overvalued. This raises the question of where that leaves investors who only look at the P/E.
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Permian Basin Royalty Trust for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 28 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Concerned that the tone around Permian Basin Royalty Trust feels stretched or overly cautious today? Move quickly, test every assumption, and ground your own thesis in the underlying numbers and risk factors before relying on the headline story alone. To dig into the specific issues flagged by this research, start with the 1 important warning sign.
Looking for more investment ideas beyond Permian Basin Royalty Trust?
You have already done the hard part by questioning the rally in Permian Basin Royalty Trust. Now widen the lens and use structured screens to uncover opportunities that better match your risk, income, and valuation priorities.
- Target resilient balance sheets and steadier fundamentals by running a list of solid balance sheet and fundamentals (24 results) that filters for businesses with financial strength at the core of their story.
- Chase quality at a sensible entry point with the 28 high quality undervalued stocks and compare what you pay today with what the underlying fundamentals suggest.
- Lock in your focus on income by reviewing the 5 dividend fortresses and zero in on higher yield candidates with support from stronger financials.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com