
Can Sartorius (XTRA:SRT3) Justify Its Valuation As 2026 Guidance Holds Despite Tariff Risks?
Sartorius (XTRA:SRT3) moved back into focus after confirming and refining its 2026 earnings guidance while flagging tariff related headwinds that could trim group revenue by up to €40 million.
The refreshed 2026 guidance and Q3 results landed alongside a sharp swing in sentiment, with Sartorius posting a 1-day share price return of 3.03% and a 90-day share price return of 26.71% as investors reacted to clarified tariff impacts, the planned segment reorganisation, and the upcoming Executive Board reshuffle.
Compare Sartorius with other life science suppliers that screen strongly on quality and value by scanning our hand picked list of 194 high quality undervalued stocks right now.
Sartorius now trades only slightly below the average analyst target while sitting at a deeper discount to some intrinsic value estimates. How generous is that remaining gap after the recent 90 day surge?
Price-to-Earnings of 89x: Is it justified for Sartorius?
Sartorius now trades at a P/E of 89x, which is high relative to many life sciences peers, even with the share price at €281.8 and a DCF estimate pointing to a fair value of €337.24.
The P/E multiple captures how much investors are paying today for each euro of current earnings. For a specialist supplier into biopharmaceutical manufacturing and life science research, a rich valuation often reflects expectations for steady demand, scalable margins, and resilient cash flows rather than just the next quarter of results.
Sartorius shows a mixed picture on those drivers. Net profit margin is 6% compared with 3.8% last year, and earnings grew 63.5% over the past year after a period where profit declined by 30% per year on a 5 year view. Forecasts now point to earnings growth of 21% per year and revenue growth of 9% per year, both ahead of the wider German market but with a projected return on equity of 14.5% that still screens as low, plus a high level of debt and 100% of liabilities coming from higher risk funding sources rather than customer deposits.
The comparison work is blunt. At 89x earnings, Sartorius trades well above the Global Life Sciences industry average of 36.7x and above a peer average of 48.2x. The estimated fair P/E of 28.8x also sits far below the current multiple, suggesting the market is assigning a large premium to the forecast earnings path that could compress if sentiment cools or growth assumptions are revised.
Explore the SWS fair ratio for Sartorius.
Result: Price-to-Earnings of 89x (OVERVALUED)
Still, the rich 89x P/E sits against tariff pressure, high debt, and a weak recent 5 year share return that could all puncture confidence in the Sartorius story.
Find out about the key risks to this Sartorius narrative.
Another View: What The DCF Model Says About Sartorius
The rich 89x earnings multiple paints Sartorius as expensive, yet the SWS DCF model points in a different direction. On those projected cash flows, the share price of €281.8 sits about 16.4% below an estimated fair value of €337.24, which raises a simple question: is the market overpaying on earnings but underpaying on cash generation?
For anyone who wants to see how that cash flow based estimate is built step by step, the SWS DCF model is laid out in full detail in the valuation workup, Look into how the SWS DCF model arrives at its fair value.
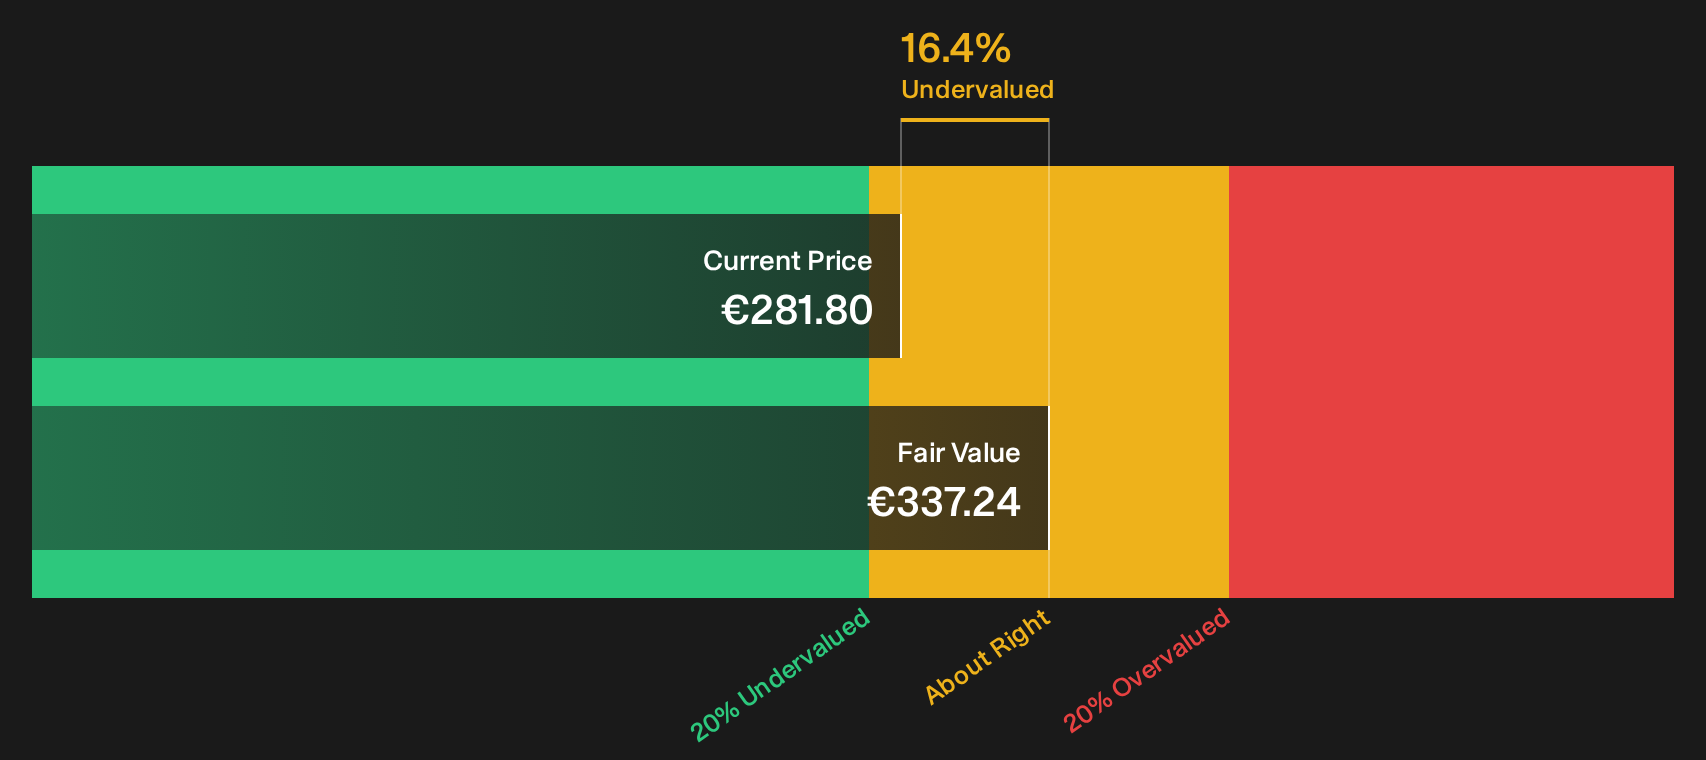
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Sartorius for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Conflicted by the mix of risk flags and upside signals around Sartorius right now? Move quickly, review the numbers yourself, and then weigh up the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Sartorius?
Do not stop with one watchlist candidate. Use the Simply Wall Street Screener to quickly spot fresh ideas that fit your style and risk tolerance.
- Target potential mispricing by reviewing a curated 194 high quality undervalued stocks that couples strong fundamentals with room for a better market view.
- Strengthen portfolio resilience by scanning a list of solid balance sheet and fundamentals (207 results) that can help when conditions get tougher.
- Get ahead of the crowd by checking a 611 high quality undiscovered gems before attention and valuations catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com