
Prosperity Bancshares (PB) Lifts Dividend As Fair Value Questions Come Back Into Focus
Dividend increase puts Prosperity Bancshares in focus
Prosperity Bancshares (PB) moved back onto income investors’ radar after the board approved a higher quarterly dividend of $0.64 per share for the fourth quarter of 2026.
The payout, set for January 4, 2027 to holders on record as of December 15, 2026, represents a 6.67% lift, or $0.04 per share, compared with the prior quarter.
Prosperity Bancshares has seen its share price slip around 5.5% over the past three months even as the 1-year total shareholder return sits near 12.8%. The richer dividend and recent 7-day share price gain of 3.4% suggest interest is rebuilding around the stock at roughly $69.50 a share.
Scan beyond Prosperity Bancshares and line up other income plays with resilient balance sheets using our curated 5 dividend fortresses as a starting watchlist.
Prosperity Bancshares has climbed after the dividend news, yet the stock still trades below both analyst targets and some intrinsic value estimates. Does that gap reflect opportunity, or is it a fair warning label on the current price?
Most Popular Narrative: 14.8% Undervalued
Prosperity Bancshares is priced at $69.50 while the most followed narrative pegs fair value near $81.54, so the current setup hinges on whether expected cost savings, margins and capital returns actually come through.
Completion of the American Bank, Texas Partners and Stellar transactions positions Prosperity Bancshares to consolidate a larger Texas and Oklahoma footprint. Management has pointed to about US$100 to US$110 million of annual pretax cost savings that would directly support a lower efficiency ratio and higher net earnings power once integration is complete.
See why 3 investors see Prosperity Bancshares as 15% undervalued.
Result: Fair Value of $81.54 (UNDERVALUED)
Still, the Prosperity Bancshares story can break if credit costs flare up again, or if flat loan volumes keep dragging on interest earning asset growth.
Find out about the key risks to this Prosperity Bancshares narrative.
Another View: Prosperity Bancshares Through The P/E Lens
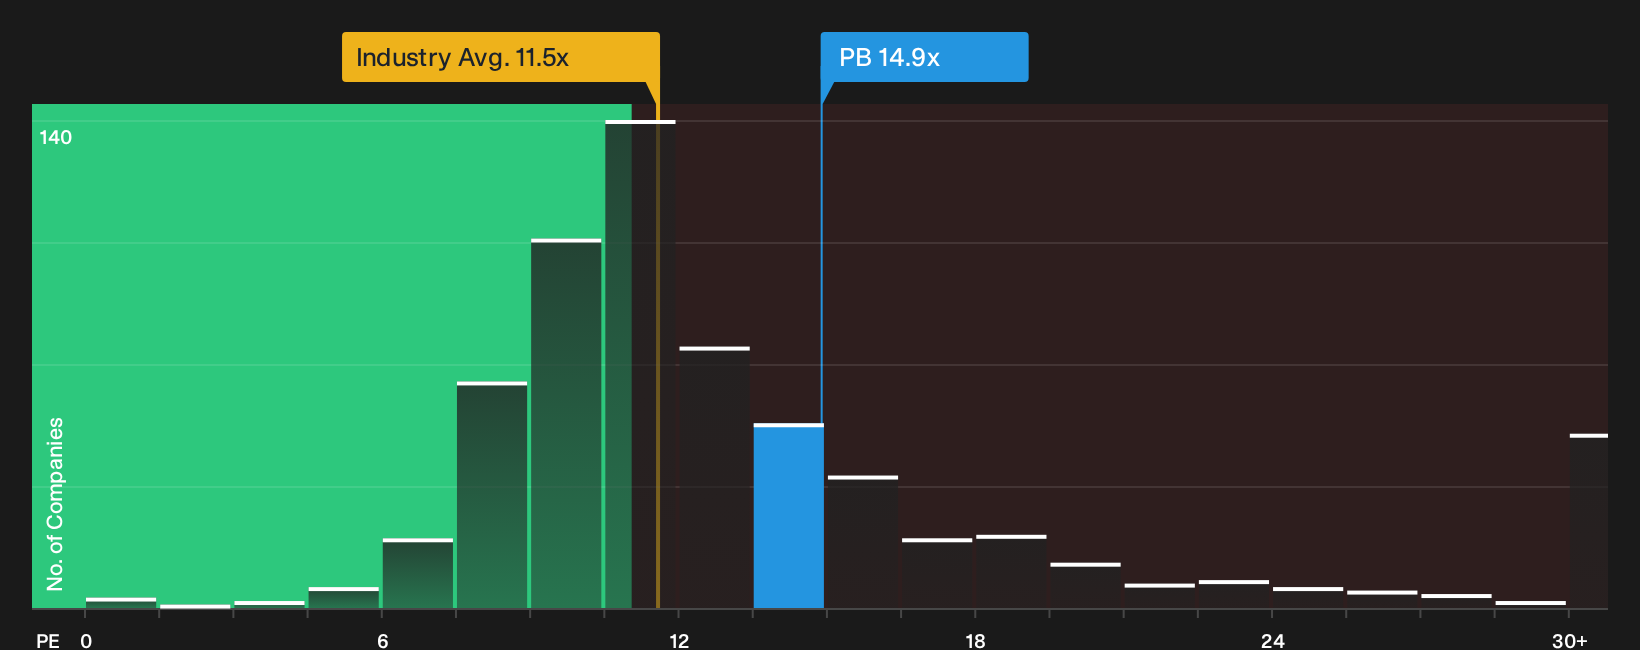
The SWS fair value work suggests Prosperity Bancshares trades around 41% below intrinsic value at $69.50, yet the market is not treating it as obviously cheap. On a P/E of 14.9x, the bank changes hands at a premium to both the US Banks industry on 11.6x and a peer average of 10.9x, and only slightly below an estimated fair ratio of 15.3x. That mix of discount on one model and premium on another leaves a basic question for investors: Which yardstick feels more realistic for how this stock ultimately gets priced?
For a closer look at how this valuation gap is built off earnings multiples, review See what the numbers say about this price — find out in our valuation breakdown..
Next Steps
Mixed signals around Prosperity Bancshares can feel messy. Move quickly, review the full data set, and weigh both the upside and the warnings for yourself with 4 key rewards and 2 important warning signs.
Looking for more Prosperity Bancshares style income ideas?
If Prosperity Bancshares has you rethinking your watchlist, broaden the view now. Fresh ideas today can matter more than fine tuning a single ticker.
- Target reliable cash flows by scanning a curated pool of income opportunities with resilient payouts and balance sheets using 5 dividend fortresses.
- Hunt for mispriced quality where fundamentals and valuations line up, then build a shortlist straight from 29 high quality undervalued stocks.
- Protect your downside first and let upside take care of itself by filtering resilient businesses through 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com