
KRAS Cancer Trial Partnership Might Change The Case For Investing In Incyte (INCY)
- Genmab and Incyte recently announced a clinical trial collaboration to test petosemtamab with Incyte’s KRAS G12D inhibitor INCB161734 plus standard chemotherapy in first line KRAS G12D mutated metastatic colorectal cancer, with Genmab running the Phase 1/2 study and Incyte co funding and supplying its agent.
- The partnership gives Incyte deeper exposure to gastrointestinal oncology through a KRAS focused regimen that aligns with its effort to build multiple non Jakafi franchises across solid tumors.
- We will now look at how this KRAS G12D colorectal cancer collaboration could influence Incyte's investment narrative around non Jakafi opportunities.
Expand your watchlist beyond Incyte by scanning a hand picked 29 high quality undervalued stocks that share strong fundamentals and may be priced below what their cash flows imply.
Incyte Investment Narrative Recap
To own Incyte, you need to believe the business can gradually replace Jakafi dependence with a set of newer oncology, dermatology and hematology products while absorbing heavier R&D and deal costs. The KRAS G12D colorectal tie up fits that story but does not change the near term swing factor, which remains execution on already launched drugs and pivotal programs.
The biggest operational risk still sits in the pipeline, especially GI oncology and mutation directed MPNs, where any weak data could leave the non Jakafi revenue mix thinner than planned while spending stays high. This new study adds optionality rather than shifting that risk balance.
The most relevant fresh update is Incyte’s ESMO 2026 data slate for INCB161734 in colorectal and pancreatic cancers and for other solid tumor agents. Those readouts speak directly to whether the KRAS G12D franchise has enough clinical traction to justify its growing share of the R&D budget.
If the data package refines safety and activity expectations, investors get a clearer sense of how realistic the long term GI oncology ambitions are and how much ongoing spend they might require. That context shapes how meaningful the Genmab colorectal collaboration could become within the broader non Jakafi catalyst stack.
Incyte's current analyst setup points to revenues of US$5.8b and earnings of US$1.2b by 2029, with earnings today at US$1.6b. This profile implies flat top line expectations over the next three years, alongside an earnings decrease of US$0.4b by the 2029 forecast year.
Uncover why Incyte's fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment shifts.
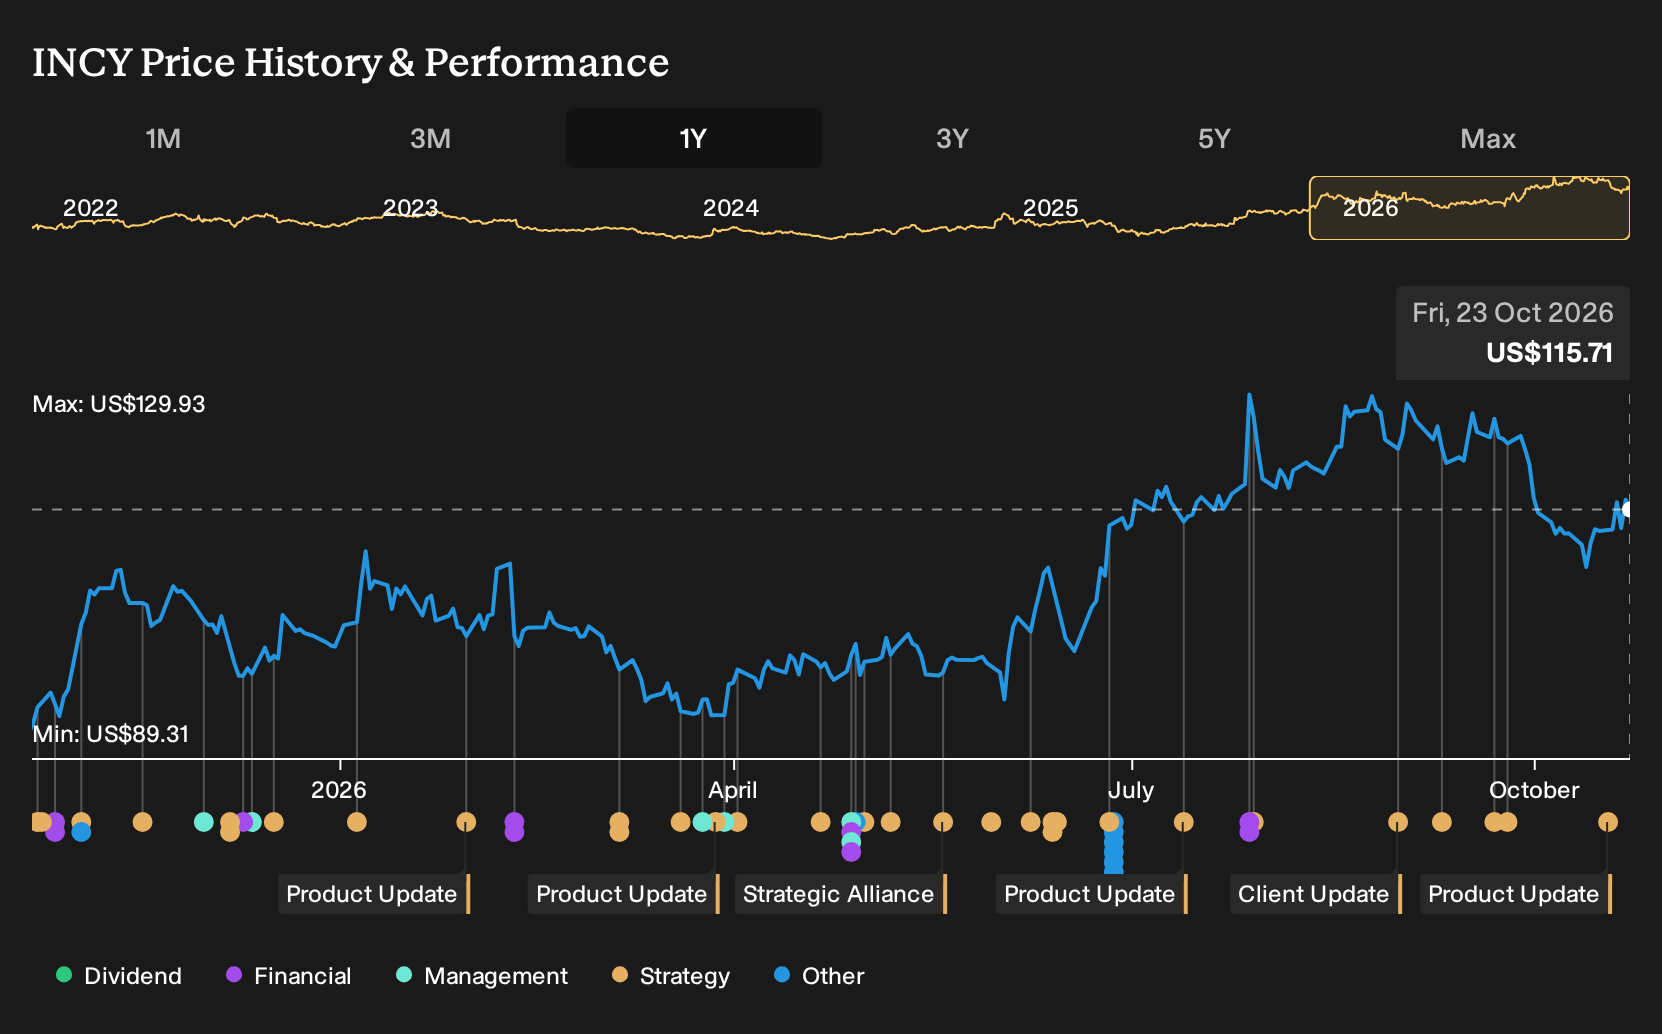
Exploring Other Perspectives
Some of the most optimistic analysts lean on a single potential catalyst: that Incyte’s GI oncology push can reset expectations. Before this Genmab tie up, they were modeling revenue of about US$7.6b and earnings of US$2.2b by 2029, compared with the bearish camp closer to US$5.8b and US$1.2b. That gap shows how widely views can differ and invites you to weigh how this new KRAS G12D colorectal study might shift those narratives.
Explore 4 other Incyte fair value estimates, including one that suggests up to 45% upside from the current price.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Incyte research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Incyte. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Incyte's overall financial health at a glance.
Looking For More Ideas Beyond Incyte?
Once you have a view on Incyte, it can help to widen the lens and compare it with other companies that match your preferred balance of quality, valuation, income and risk. The Simply Wall St Screener lets you filter for those traits quickly so you can spend more time weighing the story behind each ticker.
- If capital preservation matters most, start with a group of 30 resilient stocks with low risk scores that historically show more resilient profiles when conditions get choppy.
- If reliable cash flows and cleaner finances appeal, scan a list of solid balance sheet and fundamentals (24 results) to see which businesses pair sturdy balance sheets with fundamental strength.
- If you want to get paid while you wait, review a curated set of 5 dividend fortresses that combine higher yields with a focus on sustainability.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com