
Biotest (XTRA:BIO3) Shares Look Pricey Following A Fair Value Gap
Biotest (XTRA:BIO3) continues to trade quietly after a flat week, leaving investors weighing a year-to-date gain of about 4% against a roughly 19% decline over the past 3 years.
Short term momentum has cooled, with a 1-day share price return of down 3.4% and a 90-day share price return of down 3.4%. The year-to-date share price return of 4.4% and a 1-year total shareholder return of 4.9% show only modest progress compared with the longer term 3-year total shareholder return decline of 19.0%.
Scan Biotest alongside a curated group of peers by checking stocks on the 194 high quality undervalued stocks that combine resilient balance sheets with established cash generation.
Biotest looks like a solid specialist in plasma based therapies, yet the share price has barely budged overall despite this year’s small uptick. Is that quiet chart hiding fair value, or is it an opportunity on the screen today?
Price-to-Sales of 1.8x: Is it justified?
Biotest changes hands at a P/S ratio of 1.8x, while sitting in a part of the market where many biotech stocks carry far richer tags. That gap raises a simple question for investors weighing the €28.4 share price. Is this a discount that reflects real risks, or has sentiment moved further than the current financial profile justifies?
The P/S multiple looks at how much investors are paying for each euro of revenue. For a specialist in plasma based therapies with €635.2m in sales but a net loss of €24.5m, earnings based metrics do not tell much. A sales based yardstick gives a clearer read on how the market values Biotest's commercial footprint while the business still reports losses.
Against peers, the contrast is stark. The stock trades at 1.8x sales compared with a European biotechs industry average of 8.9x and a peer group average of 23.8x. That is a steep discount. However, Biotest is also unprofitable, carries a negative return on equity of 4.81%, and interest payments are not well covered by earnings, so the lower multiple may also reflect balance sheet pressure and execution risk while losses are being reduced.
Result: Price-to-sales of 1.8x (UNDERVALUED).
See what the numbers say about this price — find out in our valuation breakdown.
Still, Biotest's ongoing losses and weak interest cover could quickly change the story if cash needs rise or clinical projects stall.
Find out about the key risks to this Biotest narrative.
Another view on Biotest’s value
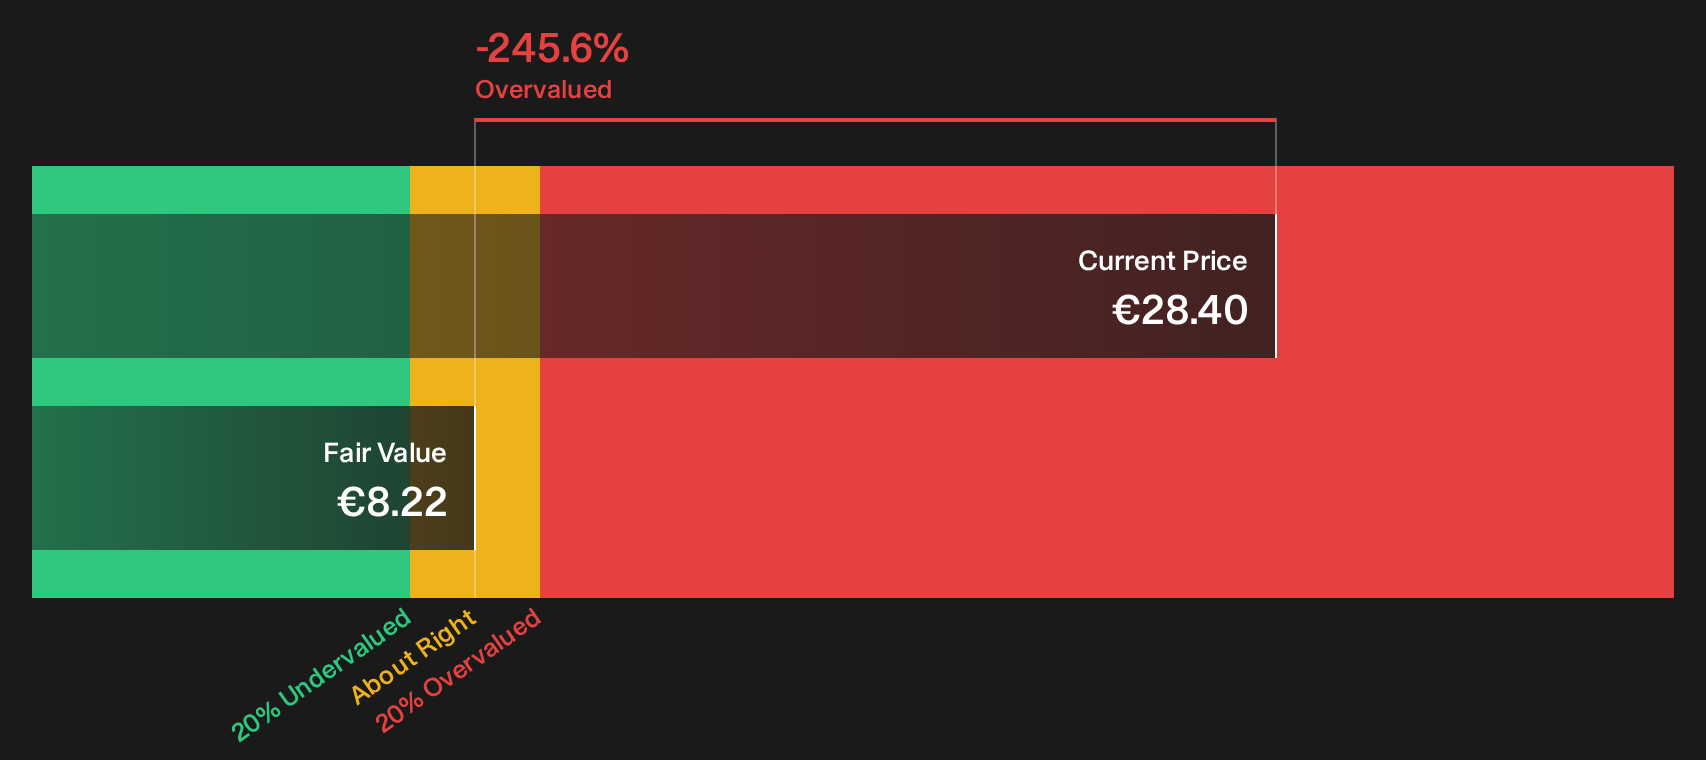
The low P/S ratio paints Biotest as cheap on sales, yet the SWS DCF model points the other way. On that framework, an estimated fair value of about €8.22 per share sits far below the current €28.4 price. This implies the stock screens as overvalued on cash flow assumptions.
That clash between a revenue based discount and a cash flow based premium forces a simple question. Which risk matters more for you: paying up against the DCF output, or walking away from a low sales multiple that the market might eventually reward?
Look into how the SWS DCF model arrives at its fair value.
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Biotest for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on Biotest's valuation can feel messy, so do not wait for consensus to form before you look under the hood yourself. If potential downsides matter to your thesis, start by reviewing these 2 important warning signs.
Looking for more investment ideas beyond Biotest?
Do not stop at Biotest. Broaden your watchlist with a few focused stock ideas that match different risk levels, cash profiles, and balance sheet strengths.
- Target potential mispricing by scanning companies that pass strict quality and valuation filters using the 194 high quality undervalued stocks.
- Prioritise resilience by reviewing a list of solid balance sheet and fundamentals (207 results) that can help you focus on businesses with financial room to move.
- Hunt for off-the-radar opportunities that still show strong fundamentals through a curated pool of 611 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com