
Is EMA Drug Rejection Altering The Investment Case For Omeros (OMER)?
- Omeros reported that the EMA’s Committee for Medicinal Products for Human Use maintained a negative opinion on narsoplimab for TA-TMA in Europe after re-examination, limiting near term access to an approved therapy in that region, while YARTEMLEA remains available in the U.S. for patients aged two and older.
- The firm plans to end its European compassionate-use program to prioritize growing U.S. commercial demand for YARTEMLEA. This concentrates resources on an active revenue channel but leaves European TA-TMA physicians without an approved treatment option.
- We will now look at how Omeros’ investment narrative is affected by the EMA rejection of YARTEMLEA for European TA-TMA.
Omeros Investment Narrative Recap
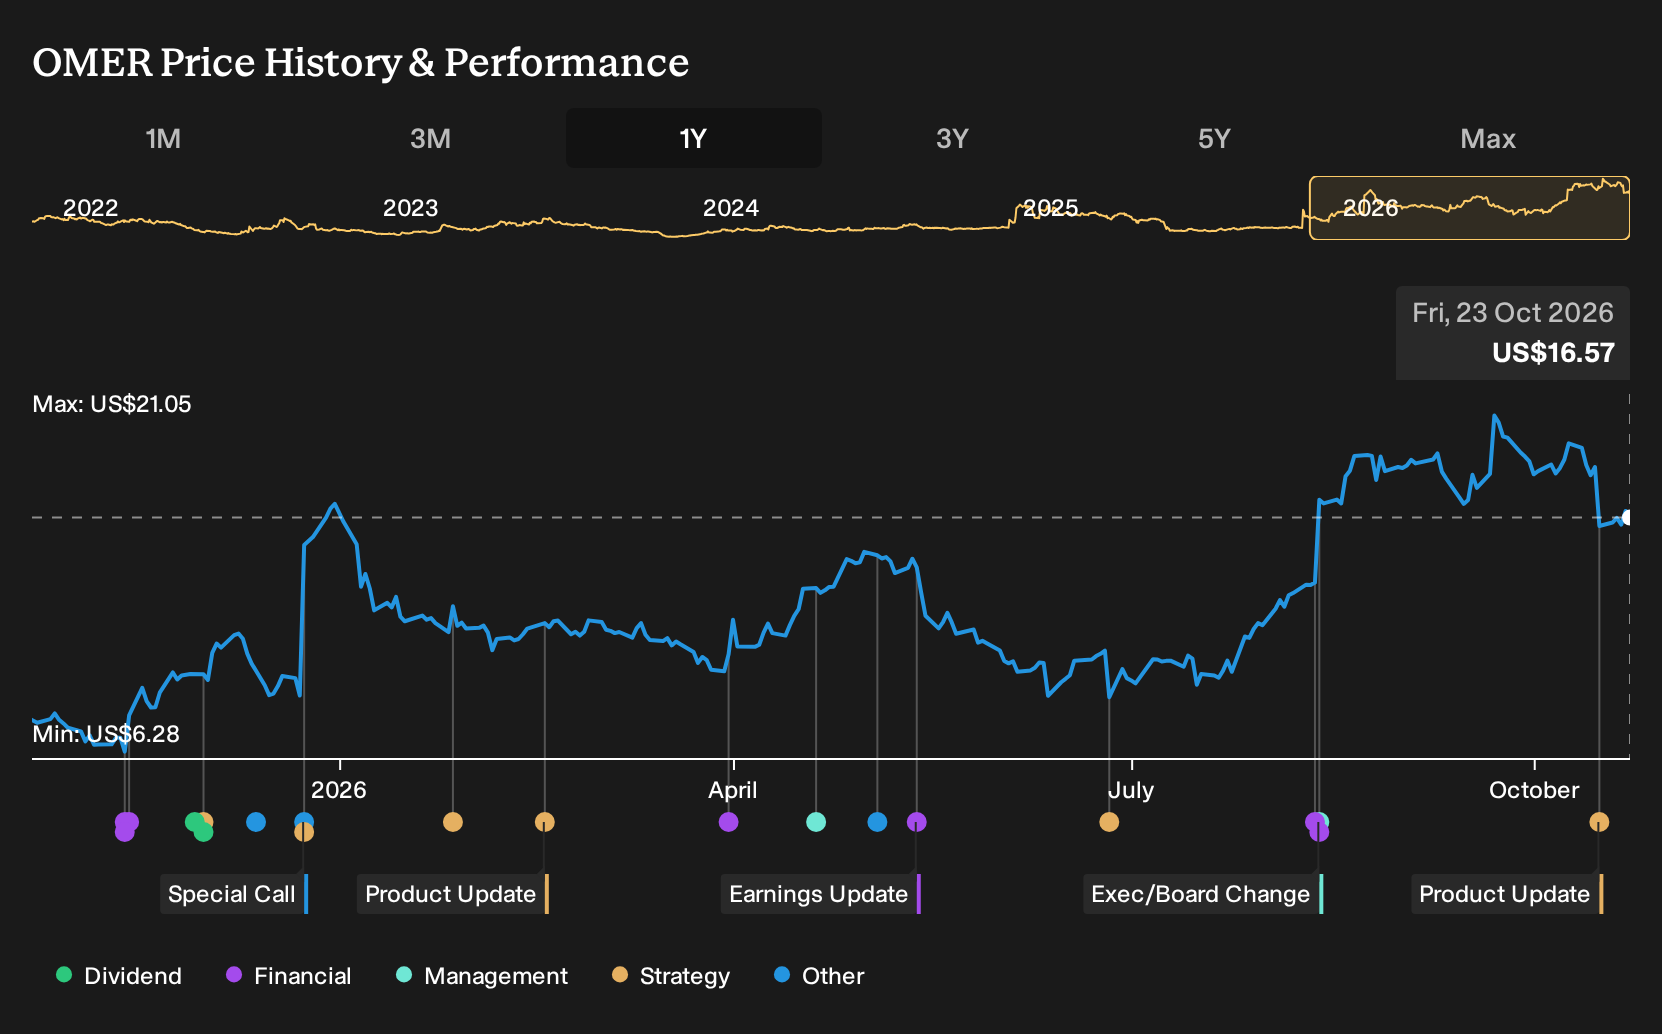
To own Omeros, you need to buy into a focused complement biology story in which YARTEMLEA funds a broader MASP 2 and MASP 3 pipeline over time. The EMA rejection keeps that vision concentrated on the U.S. for now, so the near term operating picture is about execution in one key geography rather than two.
The short term swing factor is how quickly U.S. TA TMA use of YARTEMLEA can build against a rare disease base. The biggest risk remains liquidity and funding if YARTEMLEA uptake, Novo Nordisk cash flows, or pipeline timelines do not track expectations, especially with negative equity and debt not well covered by operating cash flow.
The most relevant development is the FDA approval of YARTEMLEA for TA TMA patients aged two and older in the U.S., contrasted with the recent EMA decision. That split puts commercial weight squarely on the American market at the same time Omeros plans to end European compassionate use to prioritize U.S. supply.
For catalysts, investor attention naturally gravitates to early launch execution, payer access, and transplant center adoption in the U.S. The EMA outcome also increases the importance of other MASP 2 assets such as OMS1029 and planned trials in ARDS and high risk pediatric TA TMA, because those programs help reduce reliance on a single approved product over time.
Omeros' current analyst setup points to revenues of $375.5 million and earnings of $165.9 million by 2029, based on an assumed 113.8% yearly revenue growth rate and an earnings move of about $49.4 million from $116.5 million today.
Uncover why Omeros' fair value indicates a 66% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
One alternate Omeros lens puts much more weight on early YARTEMLEA launch traction. The most optimistic analysts were penciling in about $474.8 million of revenue and $225.8 million of earnings by 2029, well above the $375.5 million and $165.9 million consensus. With the EMA setback, those views are likely to be revisited rather than ignored.
Explore another Omeros fair value estimate, including one that suggests as much as 464% upside from the current price!
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Omeros research is our analysis highlighting 4 key rewards and 4 important warning signs that could impact your investment decision.
- See our latest analysis for Omeros. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Omeros' overall financial health at a glance.
Looking for more investment ideas beyond Omeros?
If the Omeros story has sharpened your view on risk, reward, and balance sheet strength, it can help to line it up against a wider watchlist. Use the Simply Wall St Screener to quickly surface other candidates that match the kind of financial profile you want to research next.
- If capital preservation sits high on your list, check out a curated group of stocks screened for resilience and lower risk profiles through the 30 resilient stocks with low risk scores.
- Income focused investors who want payouts backed by fundamentals can review a hand picked set of high yield payers via the 5 dividend fortresses.
- For those hunting for strong businesses that receive less attention, scan a focused group of financially robust outliers using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com