
Aker BP (OB:AKRBP) Reports Stronger Q3 Volumes, Is The Upside Already Priced In?
Aker BP’s Q3 2026 operating update
Aker BP (OB:AKRBP) put fresh operational data on the table in mid October, tying third quarter 2026 production and sales volumes to new gas and condensate satellites in the Norwegian Sea.
The operational update comes amid strong recent gains for Aker BP. The company has recorded a 30-day share price return of 12.77% and a year-to-date share price return of 51.25%, while the 1-year total shareholder return of 61.48% indicates momentum that investors are still pricing into the story.
Scan Aker BP’s momentum against other energy plays by reviewing the hand picked list of solid balance sheet and fundamentals (207 results) in the same space.
The recent surge in Aker BP, set against modest revenue and net income growth, raises a simple question. Are investors paying up for sturdier operations or for a mood shift around the stock’s story and its valuation going forward?
Most Popular Narrative: 17% Overvalued
Aker BP last closed at NOK393.10 against a narrative fair value of NOK337.19. The widely followed storyline assumes the current price already builds in richer expectations than the underlying model, even after factoring in its project pipeline and earnings profile.
Aker BP aims to sustain production above 500,000 barrels per day beyond 2030, driven by their 2 billion barrel opportunity and projects like Yggdrasil and Johan Sverdrup. This supports long-term revenue growth through extended production capacities.
See why 43 investors see Aker BP as 17% overvalued.
Result: Fair Value of NOK337.19 (OVERVALUED)
Still, Aker BP’s heavy reliance on key assets like Johan Sverdrup, along with the prospect of higher emissions costs, could pressure profitability and unsettle the current valuation story.
Find out about the key risks to this Aker BP narrative.
Another View: Aker BP Through A Cash Flow Lens
The analyst narrative describes Aker BP as overvalued at NOK393.10 versus a NOK337.19 fair value, yet the SWS DCF model points in the opposite direction. On that framework, the shares trade below an estimated future cash flow value of NOK625.78, which implies a very different risk reward balance. Which story do you trust more: earnings multiples or long term cash flows?
For a closer look at how that cash flow figure is built, review the Look into how the SWS DCF model arrives at its fair value..
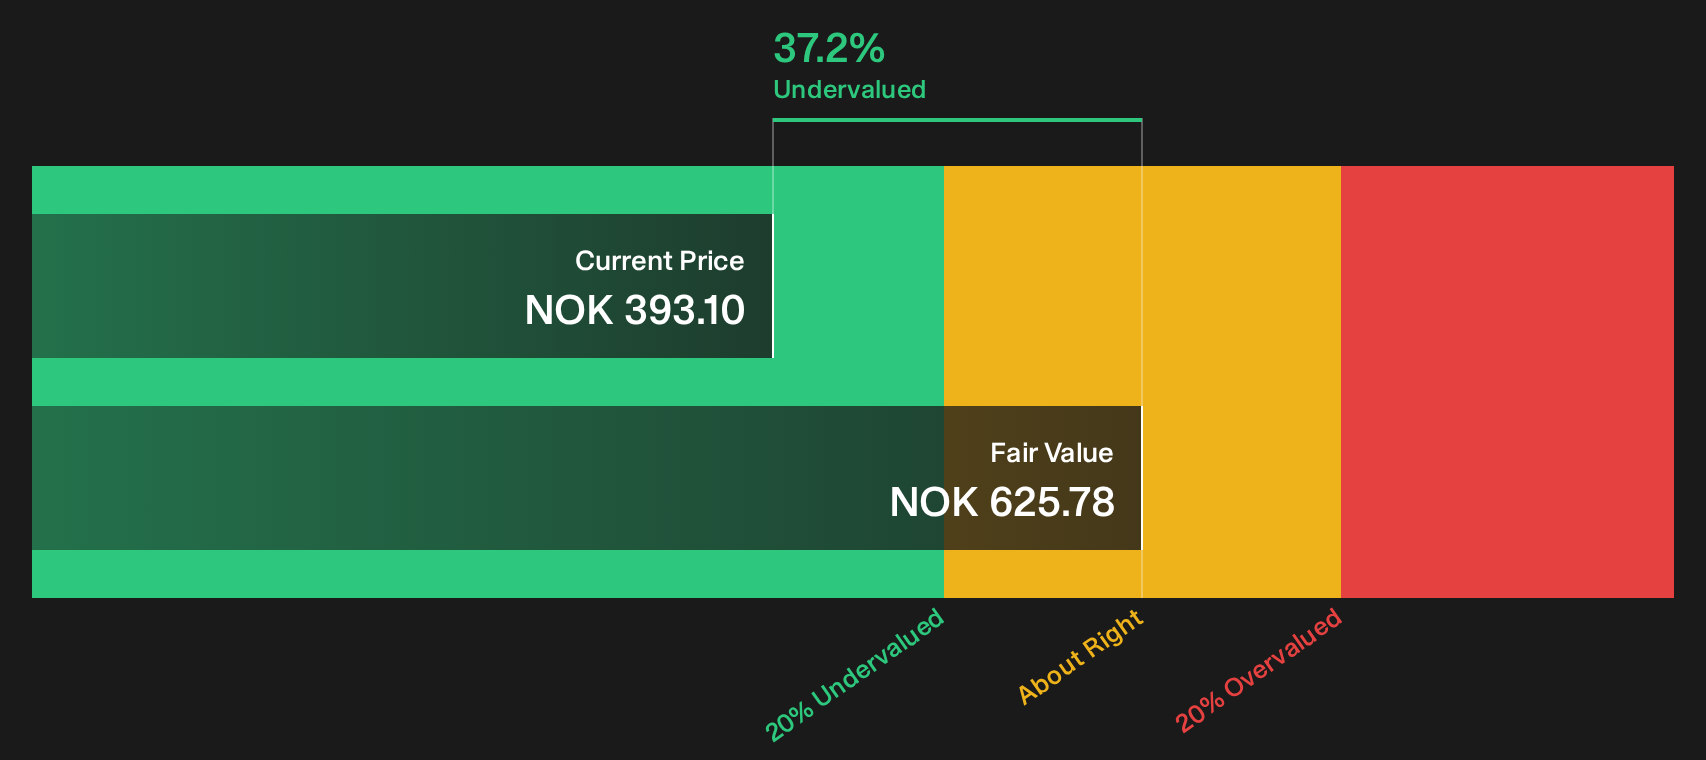
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Aker BP for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If the mixed messages on Aker BP leave you unsure, that is the point. Consider acting while sentiment is still split and weigh up the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Aker BP?
If Aker BP has sharpened your focus on valuation and risk, you can extend that momentum into a broader watchlist using targeted stock ideas built from the Simply Wall St Screener.
- Target potential mispricings by scanning a curated set of 194 high quality undervalued stocks that pair stronger fundamentals with prices that may not fully reflect them yet.
- Strengthen your income stream by reviewing 230 dividend fortresses that combine higher yields with business profiles focused on sustaining regular payouts.
- Dial down portfolio stress by assessing 221 resilient stocks with low risk scores chosen for sturdier balance sheets and lower overall risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com