
Barratt Redrow (LSE:BTRW) Has The Market Asking A Bigger Question
The recent combination of Barratt Redrow (LSE:BTRW) with Redrow, along with the resulting cost synergies, has become a key focus for investors watching how operational efficiencies feed through to earnings and cash generation.
Recent price action shows that momentum in Barratt Redrow has been picking up in the short term, with 1-day, 7-day, and 90-day share price returns of 1.37%, 4.68%, and 11.29% respectively. However, the year-to-date share price return is still down 13.88%, and the 1-year total shareholder return has fallen 18.46%. The stock has been trying to recover from a tougher longer-term backdrop as investors reassess the combined group after the Redrow deal.
Compare Barratt Redrow's recent swing in returns with hand-picked peers by scanning 8 high quality undervalued stocks, which also pair earnings power with balance sheets built to handle housing cycle stress.
Barratt Redrow now looks like a bigger, more efficient housebuilder on paper after the Redrow deal. The real test is whether that story is already fully reflected in the share price.
Most Popular Barratt Redrow Narrative: 3% Undervalued
On the numbers, the narrative fair value of £3.36 sits only slightly above Barratt Redrow’s last close at £3.26. This puts the focus squarely on whether integration synergies and cash returns can really support that small gap.
The combination of Barratt Redrow and Redrow has moved from identifying to delivering the targeted £100m of annual cost synergies, with about £73m already reflected in FY26 results and around £95m expected to flow through the FY27 income statement, which directly supports net margins and earnings.
See why 68 investors see Barratt Redrow as 3% undervalued.
Result: Fair Value of £3.36 (UNDERVALUED)
Still, if build cost inflation runs ahead of the planned £100m synergies, or if safety remediation cash outflows rise beyond the £1.05b provision, that narrative could crack.
Find out about the key risks to this Barratt Redrow narrative.
Another View: Barratt Redrow Through The Cash Flow Lens
The fair value narrative at £3.36 paints Barratt Redrow as modestly undervalued on earnings, yet the SWS DCF model points the other way. On that cash flow view, the shares at £3.26 sit above an estimated value of £2.08, which frames the stock as overvalued instead. Which yardstick do you trust more: earnings or cash generation?
Look into how the SWS DCF model arrives at its fair value.
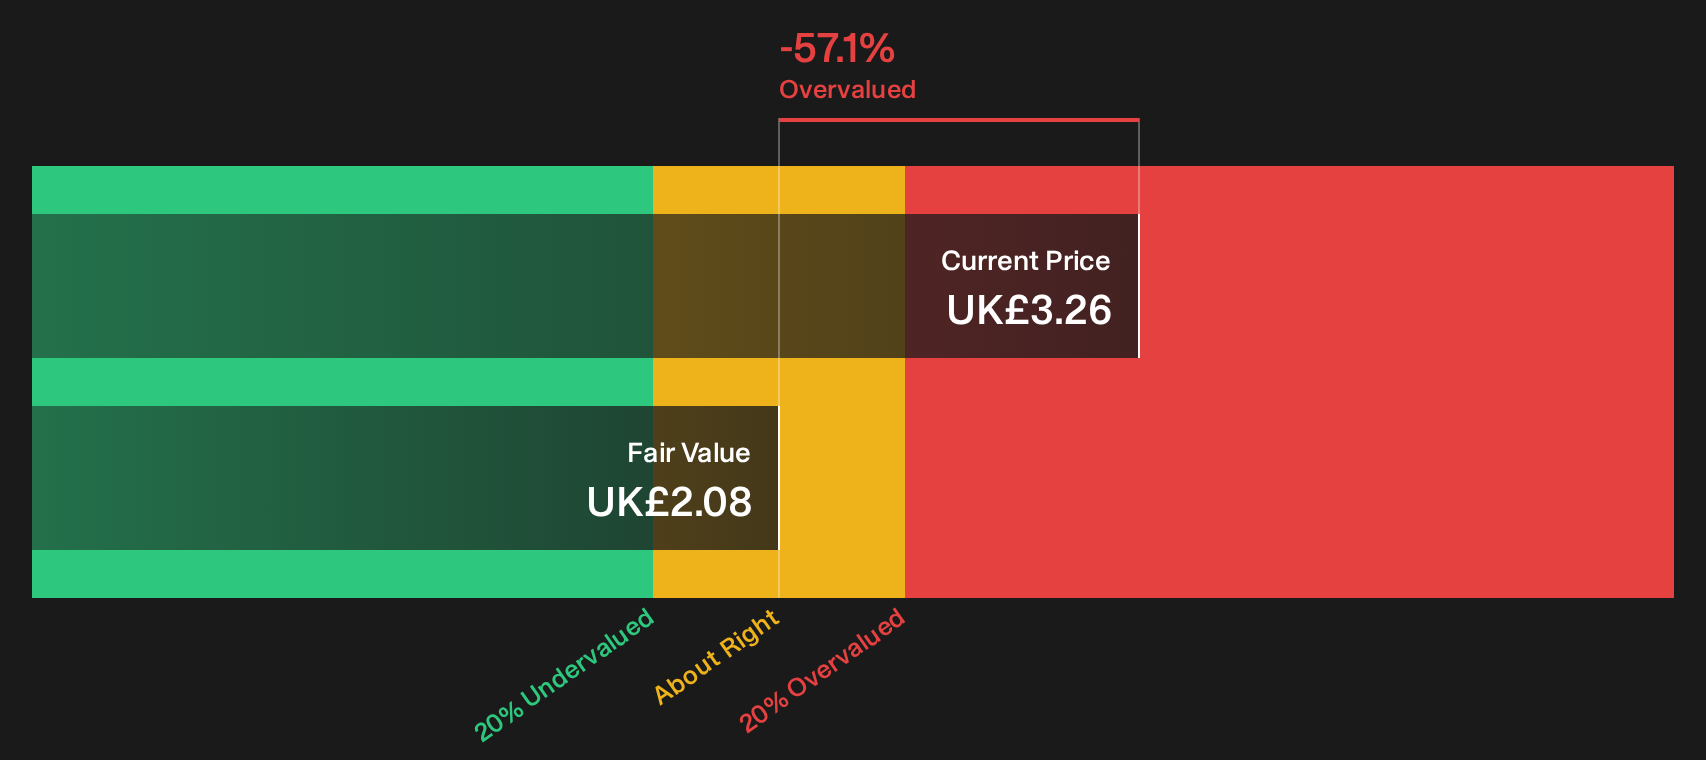
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Barratt Redrow for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 8 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
With sentiment on Barratt Redrow pulled between fair value models and market worries, it helps to test those mixed signals against the underlying data yourself. To see the specific rewards our analysis has flagged and decide how they stack up in your view, start with the 2 key rewards.
Looking For More Investment Ideas Beyond Barratt Redrow?
If Barratt Redrow has sharpened your focus on valuation and quality, you can broaden your watchlist with a few targeted screens that surface different types of opportunities.
- Target reliable income first by reviewing companies screened as potential 5 dividend fortresses for investors who want yield backed by fundamentals.
- Spot potential mispricing by scanning a curated set of 5 high quality undiscovered gems before the crowd pays closer attention.
- Prioritise resilience by filtering for a list of solid balance sheet and fundamentals (9 results) so you focus on businesses with financial foundations built to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com