
Is Eni (BIT:ENI) Overvalued On Strong Earnings And Higher Shareholder Returns?
What Eni’s latest earnings signal for shareholders
Eni (BIT:ENI) just paired a sharp jump in third quarter net profit and revenue with a higher production outlook, an extraordinary dividend and a larger share buyback, directly tying operating performance to cash returns.
That earnings surprise has landed on top of a powerful run in the shares, with the Eni share price up strongly this year and a year-to-date share price return of 68.99% feeding into a five year total shareholder return of 202.31%. This pattern suggests momentum has been building as investors reassess both cash generation and risk around the business.
Scan how Eni’s capital returns compare with other cash generative energy plays by reviewing the hand picked 221 resilient stocks with low risk scores in the sector.
After a 69% year to date share price gain and richer cash returns, Eni now asks investors a simple question: Does the current valuation still compensate for project and execution risk from here?
Most Popular Narrative: 3% Overvalued
Against Eni’s last close at €27.65, the most followed narrative pegs fair value at €26.87, using an 8.69% discount rate and assuming the current share price already reflects upgraded cash flow and payout plans.
The current valuation, which this narrative holds is fairly valued and bearish, implies the market is already pricing in Eni’s upgraded cash flow guidance, rising shareholder payouts and structural growth options, without assigning a premium for further upside.
See why 76 investors see Eni as 3% overvalued.
Result: Fair Value of €26.87 (OVERVALUED)
Still, if Plenitude funding drags on cash conversion or Versalis slips back into deeper losses, the Eni narrative that investors rely on could quickly look fragile.
Find out about the key risks to this Eni narrative.
Another View on Eni’s Valuation
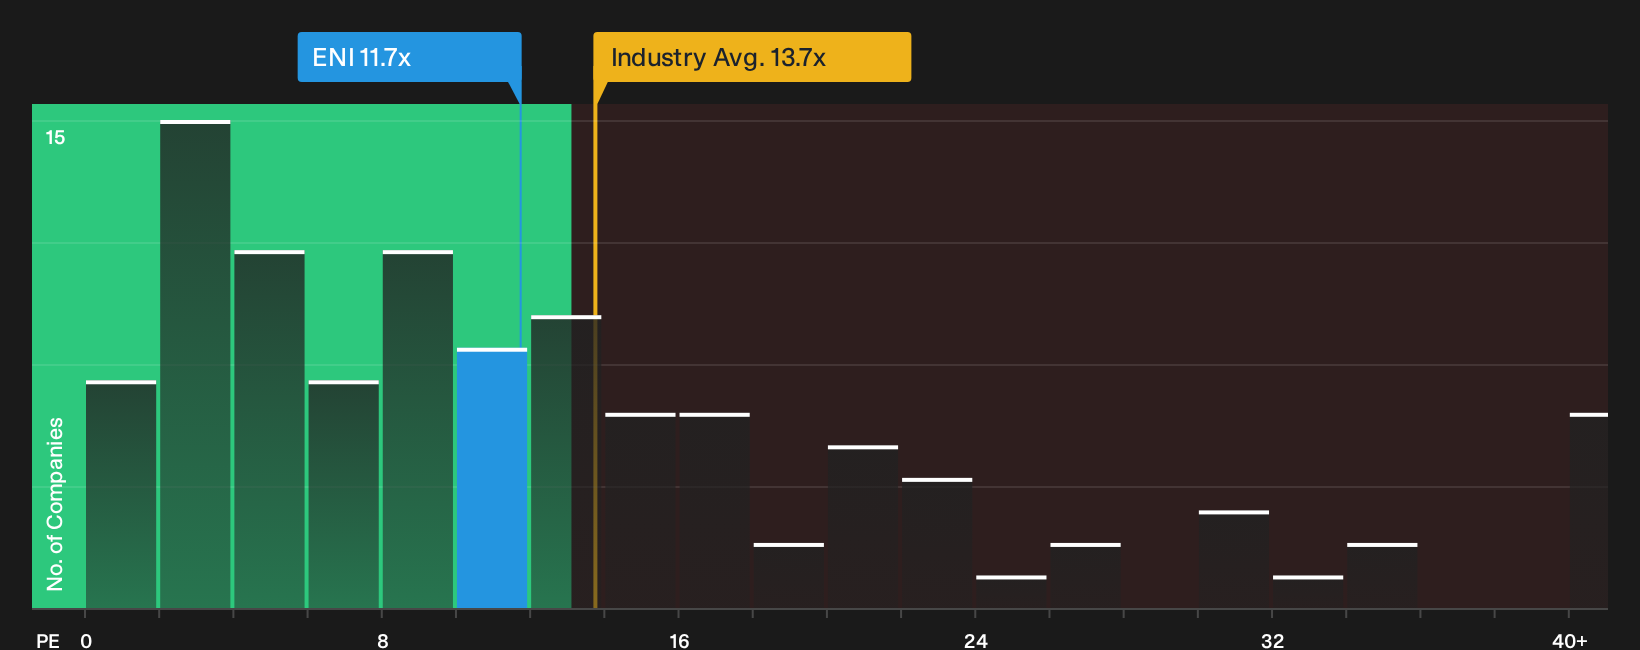
Analysts see Eni as about 3% overvalued against a €26.87 fair value, yet the P/E picture looks different. At 11.7x earnings, the shares trade below both the European Oil and Gas industry on 13.7x and peers on 13.9x, and under a fair ratio of 16.7x. Is the market underpricing execution risk or underestimating future earning power?
To see how these valuation gaps stack up in practice, including what that fair ratio might mean if sentiment shifts, See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals on Eni so far. Act while the data is fresh and weigh both sides of the story by checking the 3 key rewards and 2 important warning signs
Looking for more investment ideas beyond Eni?
Do not stop at just one opportunity. A broader watchlist can help you spot patterns, pressure test your thesis, and avoid relying on a single story.
- Start with proven balance sheets and let the data guide you toward resilient businesses through the list of solid balance sheet and fundamentals (207 results).
- Hunt for quality at a discount and pressure test valuation assumptions using the 194 high quality undervalued stocks.
- Target income-focused opportunities and compare payout strength with the 229 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com