
Is Himax Technologies (HIMX) Undervalued After Its Alibaba Qwen Glasses Win?
Himax Technologies (NasdaqGS:HIMX) is back in focus after its WiseEye ultralow power AI processor was selected for Alibaba’s new Qwen Glasses N1, where it powers always-on visual sensing in the smart glasses.
Recent trading tells a mixed story. The share price has risen 32.71% year to date to US$11.32, yet the 30 day share price return is down 21.61%. At the same time, total shareholder return over three and five years sits at 133.67% and 45.67% respectively, which hints that investors are weighing long term traction, such as the Alibaba smart glasses win, against shorter term volatility.
Scan other AI hardware players riding similar demand with a curated set of 55 AI infrastructure stocks to compare against Himax Technologies’ smart glasses exposure.
Bulls see Himax Technologies as an AI wearables supplier on sale after a sharp pullback. Bears view it as hype ahead of fundamentals. Which side do the current valuation markers support next?
Most Popular Narrative: 63% Undervalued
On the most followed view, Himax Technologies screens materially cheaper than a $30.20 fair value, yet the last close is $11.32, which puts more weight on near term swings than the long range story analysts are working with.
Rising contribution from non driver, AI and optical products, which reached 20.2% of Q2 2026 revenue and are targeted to approach 30% of sales in 2027, gives Himax Technologies more exposure to higher margin categories and can gradually shift the earnings mix away from traditional driver ICs.
See why 58 investors see Himax Technologies as 63% undervalued.
Result: Fair Value of $30.20 (UNDERVALUED)
Still, the bullish Himax Technologies story leans heavily on aggressive analyst forecasts and leaves little margin for error if sentiment or valuation multiples reset.
Find out about the key risks to this Himax Technologies narrative.
Another View: What Multiples Say About Himax Technologies
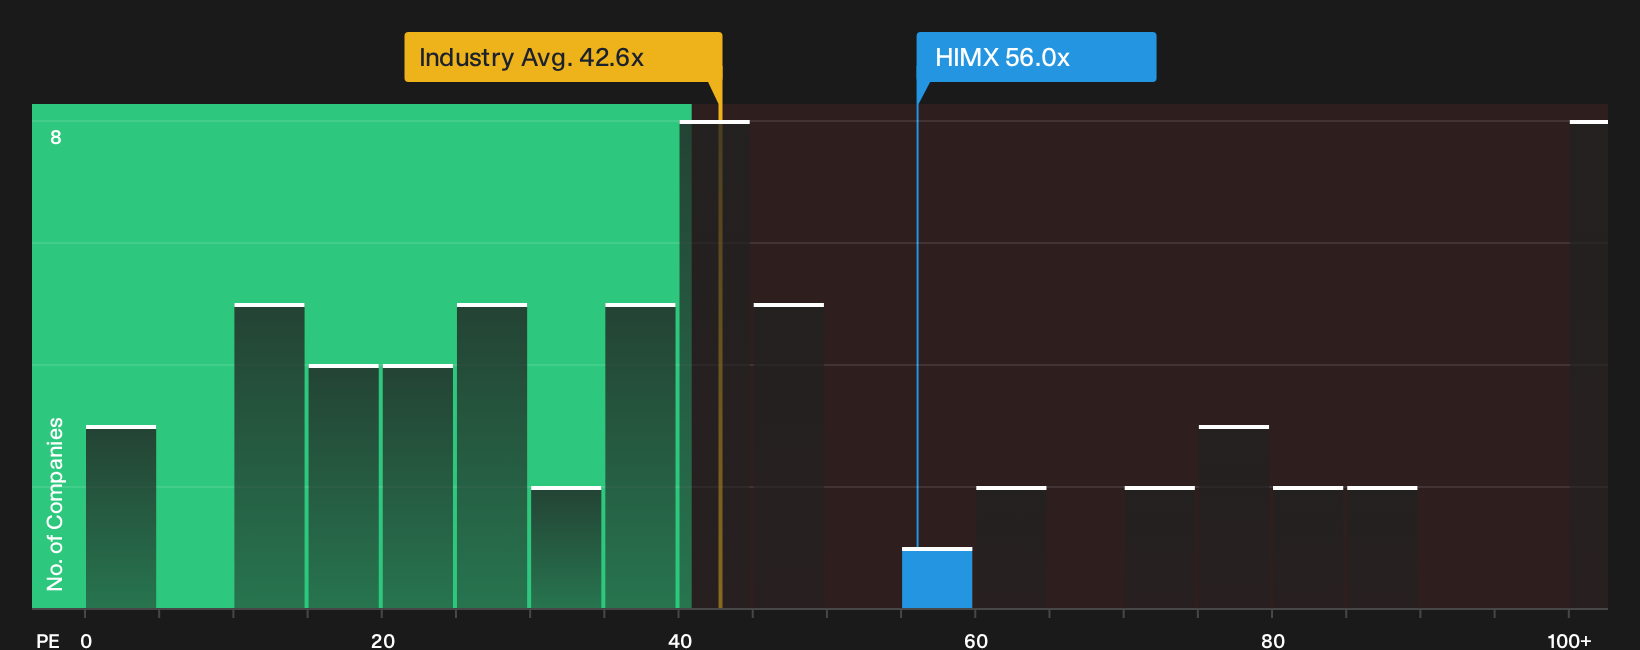
The headline story paints Himax Technologies as deeply undervalued against a $30.20 fair value, yet the current P/E of 56x tells a tougher story. That ratio is higher than the US Semiconductor industry at 42.6x, above direct peers at 47.5x, and above a fair ratio of 48.8x that the market could eventually lean toward.
If sentiment shifts away from aggressive growth forecasts, that gap in P/E levels suggests more valuation risk than the bullish target implies and raises a simple question for investors: Is this a mispriced AI and automotive supplier, or just a richly valued growth story that needs everything to go right for years?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on Himax Technologies so far. If you want your view grounded in the same data, start with the 1 key reward and 2 important warning signs.
Looking for more investment ideas beyond Himax Technologies?
If Himax Technologies has your attention, do not stop here. The real edge comes from lining it up against other focused opportunities that fit your style.
- Target potential bargains by scanning a curated 29 high quality undervalued stocks that pairs quality fundamentals with prices that may not fully reflect them yet.
- Prioritize resilience by reviewing a 30 resilient stocks with low risk scores that screens for businesses with steadier profiles and lower overall risk scores.
- Get ahead of the crowd by filtering through a 21 high quality undiscovered gems that highlights high quality companies still flying under most investors’ radar.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com