
ON Semiconductor (ON) Just Drew Fresh Attention, So What Is The Market Missing?
ON Semiconductor (ON) drew fresh attention after revealing that Sungrow will use its EliteSiC hybrid power modules and high-density power integrated modules in the new PowerTitan 3.0 utility-scale energy storage platform.
The Sungrow win lands at an interesting moment for ON Semiconductor. The share price has eased in the short term, with a 1-month share price return down 6.41% and a 3-month share price return down 18.86%. At the same time, the year-to-date share price return sits at 27.43% and the 1-year total shareholder return is 42.48%, which indicates that longer term momentum has been stronger than recent trading suggests.
Scan for other potential beneficiaries of the same energy storage trend by checking the hand-picked 42 power grid technology and infrastructure stocks that could be riding similar demand for high-efficiency grid technology.
ON Semiconductor has a clear role in high-efficiency power and sensing, yet the recent pullback raises a sharper issue. Are you now paying a fair price for that strength or still accepting a premium story?
Most Popular Narrative: 31% Undervalued
ON Semiconductor last closed at $72.25, while the most followed narrative points to a fair value of $104.46. This frames the recent pullback as a potential gap between story and price rather than just a weak patch of trading.
Rapid growth in AI data center infrastructure, combined with ON Semiconductor's claim to support the full power path from grid to processor and early traction with platforms such as NVIDIA MGX, AWS power systems and Chinese providers, underlies management's expectation that AI data center revenue will more than double in 2026 versus 2025 and scale at 50% or faster over several years, which is likely to be a key driver of overall revenue and earnings growth.
See why 128 investors see ON Semiconductor as 31% undervalued.
Result: Fair Value of $104.46 (UNDERVALUED)
Still, the ON Semiconductor story can break if auto demand stays soft for a longer period or if the Synaptics deal delivers less synergy than expected.
Find out about the key risks to this ON Semiconductor narrative.
Another View: What Multiples Say About ON Semiconductor
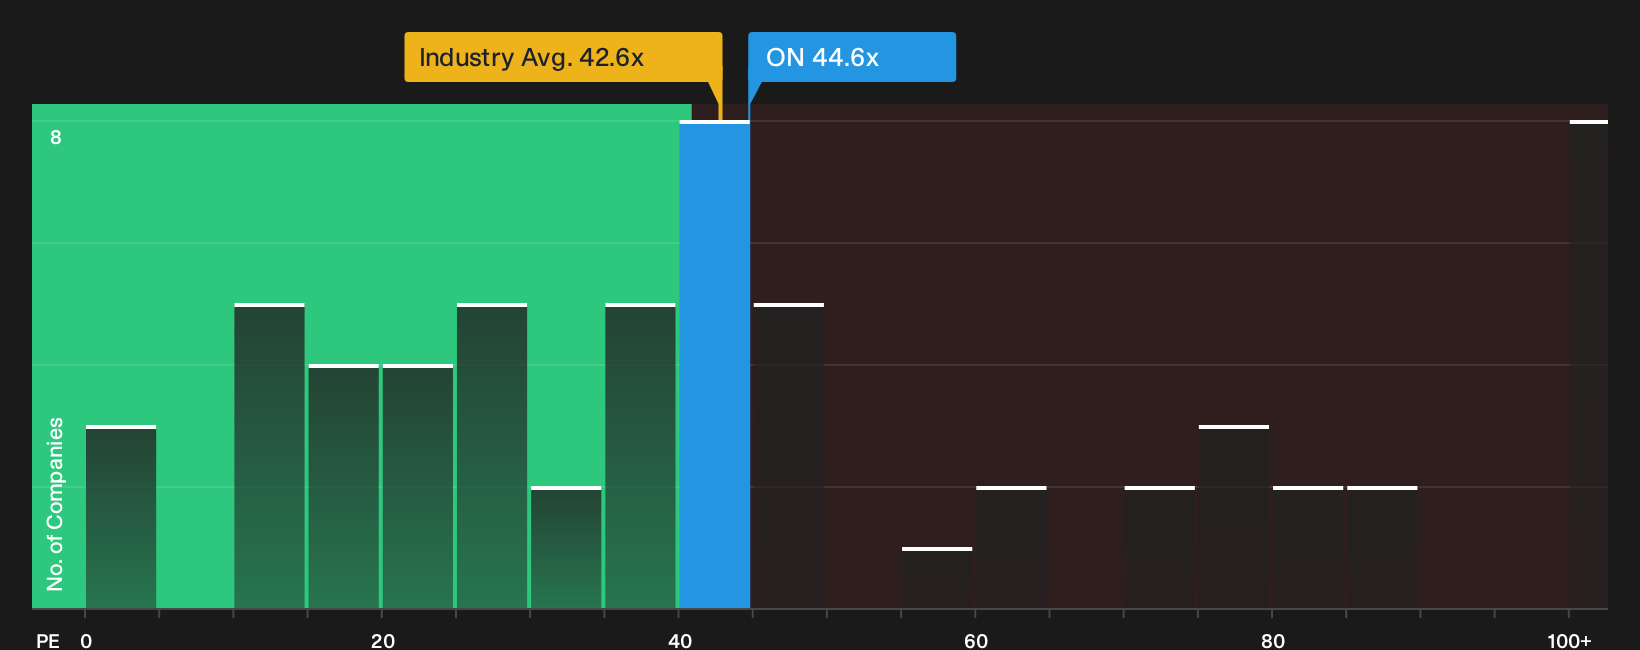
There is a different read on ON Semiconductor when you look at simple earnings multiples instead of fair value models. The stock trades on a P/E of 44.6x, which is higher than the US Semiconductor industry at 42.6x and above its own fair ratio of 38.2x, yet below a much richer peer average of 82.5x. That mix of numbers points to some valuation risk if expectations slip, even though it looks cheaper than many direct rivals. Which signal you lean on depends on how confident you are in the earnings path baked into the story.
See what the numbers say about this price in our valuation breakdown, and how ON Semiconductor screens against peers based on this same measure, in the See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around ON Semiconductor can feel confusing, so move fast, review the numbers for yourself, and weigh the 2 key rewards and 2 important warning signs.
Looking for more ON Semiconductor investment ideas?
ON Semiconductor is only one part of the opportunity set, so broaden your field of vision and let a few focused screeners spark your next move.
- Spot potential mispricings early by scanning companies that combine strong fundamentals with attractive valuations through the 29 high quality undervalued stocks.
- Strengthen your income stream by reviewing businesses offering higher-yield payouts in the 5 dividend fortresses.
- Cut concentration risk by searching for financially resilient companies using the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com