
Why Ebro Foods (BME:EBRO) Is Getting Attention Today
Garofalo’s 35.9% sales increase in Spain over two years, together with a new premium campaign with chef Jordi Cruz, has pushed Ebro Foods (BME:EBRO) into sharper focus for valuation minded investors.
The current share price of €18.52 comes after a modest but positive run, with a 90-day share price return of 1.76% and a 1-year total shareholder return of 5.39%. Together, these figures point to steady rather than explosive momentum as investors reassess Ebro Foods around a P/E of roughly 12.8x and the stronger Garofalo performance in Spain.
Scan how Ebro Foods compares with other established food producers by reviewing our hand picked group of list of solid balance sheet and fundamentals (207 results).
At around €18.52, Ebro Foods trades at a P/E that sits below the broader food sector and at a discount to analyst targets. Is this caution a bargain or a warning sign as Garofalo’s gains build?
Price-to-Earnings of 12.8x: Is it justified?
Ebro Foods looks cheap on the surface, with a P/E of 12.8x against a current share price of €18.52 and earnings that have been growing. That multiple lines up with a business that is expanding, but not rapidly, which is consistent with its recent profit and revenue trends.
The P/E ratio compares what investors pay for each euro of current earnings. For a branded food group like Ebro Foods, which operates across rice, pasta and prepared meals, this measure often reflects how durable the profit base appears and how confident the market is about future cash generation.
At 12.8x earnings, the stock trades below both the European food industry average of 15.1x and a peer group average of 14.6x. That is a clear valuation gap. It also sits under an estimated fair P/E of 15.2x, which signals a level the market could move towards if sentiment around earnings quality and growth were to align with that fair ratio.
Explore the SWS fair ratio for Ebro Foods.
Result: Price-to-Earnings of 12.8x (UNDERVALUED)
Still, a weaker rice or pasta cycle, or slower Garofalo traction outside Spain, could cap how far the market is willing to re-rate Ebro Foods.
Find out about the key risks to this Ebro Foods narrative.
Another view on Ebro Foods’ value
The P/E points to an undervalued Ebro Foods. The SWS DCF model goes even further, with an estimated future cash flow value of €41.07 per share versus the current €18.52. That gap suggests investors are heavily discounting long term cash generation. Is that caution justified or overdone?
Look into how the SWS DCF model arrives at its fair value.
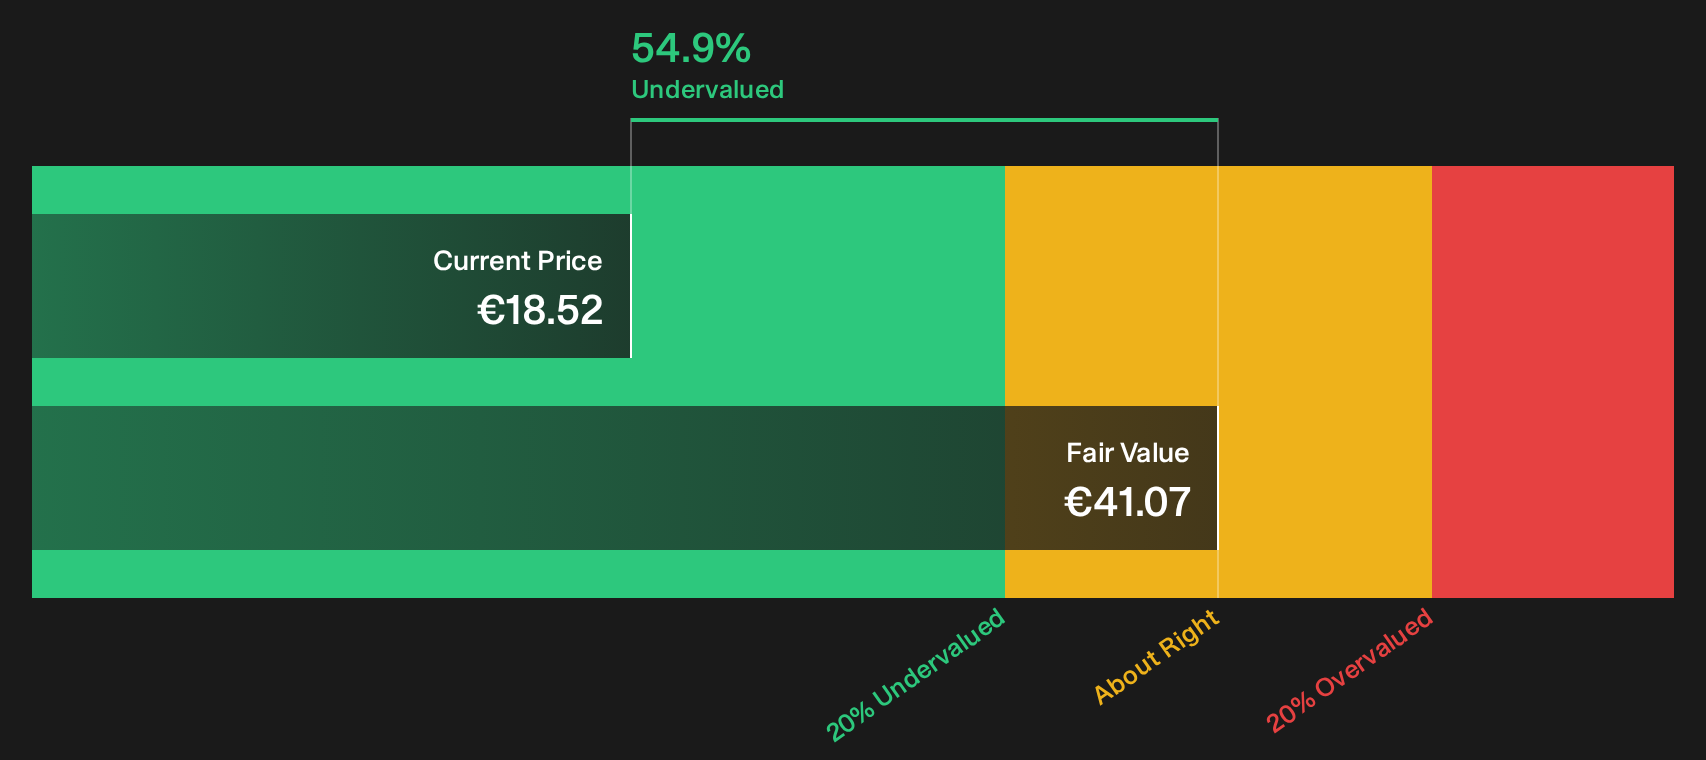
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Ebro Foods for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 194 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Ebro Foods now looks like a puzzle with both clear positives and clear question marks, so act while the data is fresh and pressure test the story yourself. To see the mix of caution and optimism in one place, review the 3 key rewards and 1 important warning sign
Looking for more investment ideas beyond Ebro Foods?
If you stop with Ebro Foods, you risk missing other opportunities that could fit your goals just as well or even better.
- Target resilient compounding potential by screening for companies that combine low leverage with strong fundamentals using our 221 resilient stocks with low risk scores.
- Spot potential mispricings early by scanning for quality businesses trading below what their financial strength suggests in the 194 high quality undervalued stocks.
- Build an income focused watchlist by filtering for consistent payers with higher yields through the 229 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com