
Does Nutrition Spin Off Change The Bull Case For Fresenius (XTRA:FRE)?
- Fresenius SE KGaA has reshaped its leadership for Fresenius Kabi after October 2026, with Dr. Marc-Alexander Mahl joining the Management Board to oversee Kabi and Pierluigi Antonelli departing, while the Nutrition operations become a standalone unit under Sébastien Guery.
- The decision to carve out Nutrition as an independent business unit under Guery, while Mahl retains broad Kabi and Pharma oversight, indicates a clearer operational focus on two distinct areas within the Fresenius Kabi portfolio.
- We will now assess how Fresenius SE KGaA's investment narrative might shift as Nutrition gains standalone status under the expanded Kabi leadership.
See how Fresenius SE KGaA’s shake-up in Kabi and Nutrition compares with other healthcare groups repositioning for growth by reviewing our curated list of 124 healthcare AI stocks.
Fresenius SE KGaA Investment Narrative Recap
To own Fresenius SE KGaA, you need to buy into Kabi and Helios as the main earnings engines, with Kabi’s Biopharma, Nutrition and MedTech platforms carrying a lot of the future uplift. The near term swing factor is still how quickly these areas scale while cost inflation and tender pressure, especially in China and nutrition, stay manageable.
This management reshuffle looks more operational than thesis changing. The biggest immediate risk remains that wage, energy and supply chain costs outpace pricing and efficiency gains, which would squeeze margins. If that happens alongside weaker procurement outcomes in key markets, the earnings path that many investors have in mind becomes harder to reach.
The most relevant development for this board change is Kabi’s growth platform progress. Biopharma, Nutrition and MedTech together delivered 12% organic revenue growth and a 17.9% EBIT margin in Q2 2026, which is where many investors are looking for incremental earnings power. Fresenius SE KGaA is effectively putting long time Pharma leader Marc Alexander Mahl fully in charge of that engine.
Separating Nutrition under Sébastien Guery, who already runs that activity, lines up with its growing importance in the Fresenius Kabi mix. Execution now hinges on keeping that 12% organic growth profile and high segment margin intact while scaling biosimilars and new products. Any wobble here, or in tender exposure in China, would directly affect the key catalysts investors are watching.
Fresenius SE KGaA's current analyst narrative points to revenues of €26.9 billion and earnings of €2.5 billion by 2029, based on an assumed 4.9% yearly revenue growth rate and an earnings increase of about €0.9 billion from €1.6 billion today.
Uncover how Fresenius SE KGaA's fair value indicates a 21% potential upside to its current price that may not last much longer.
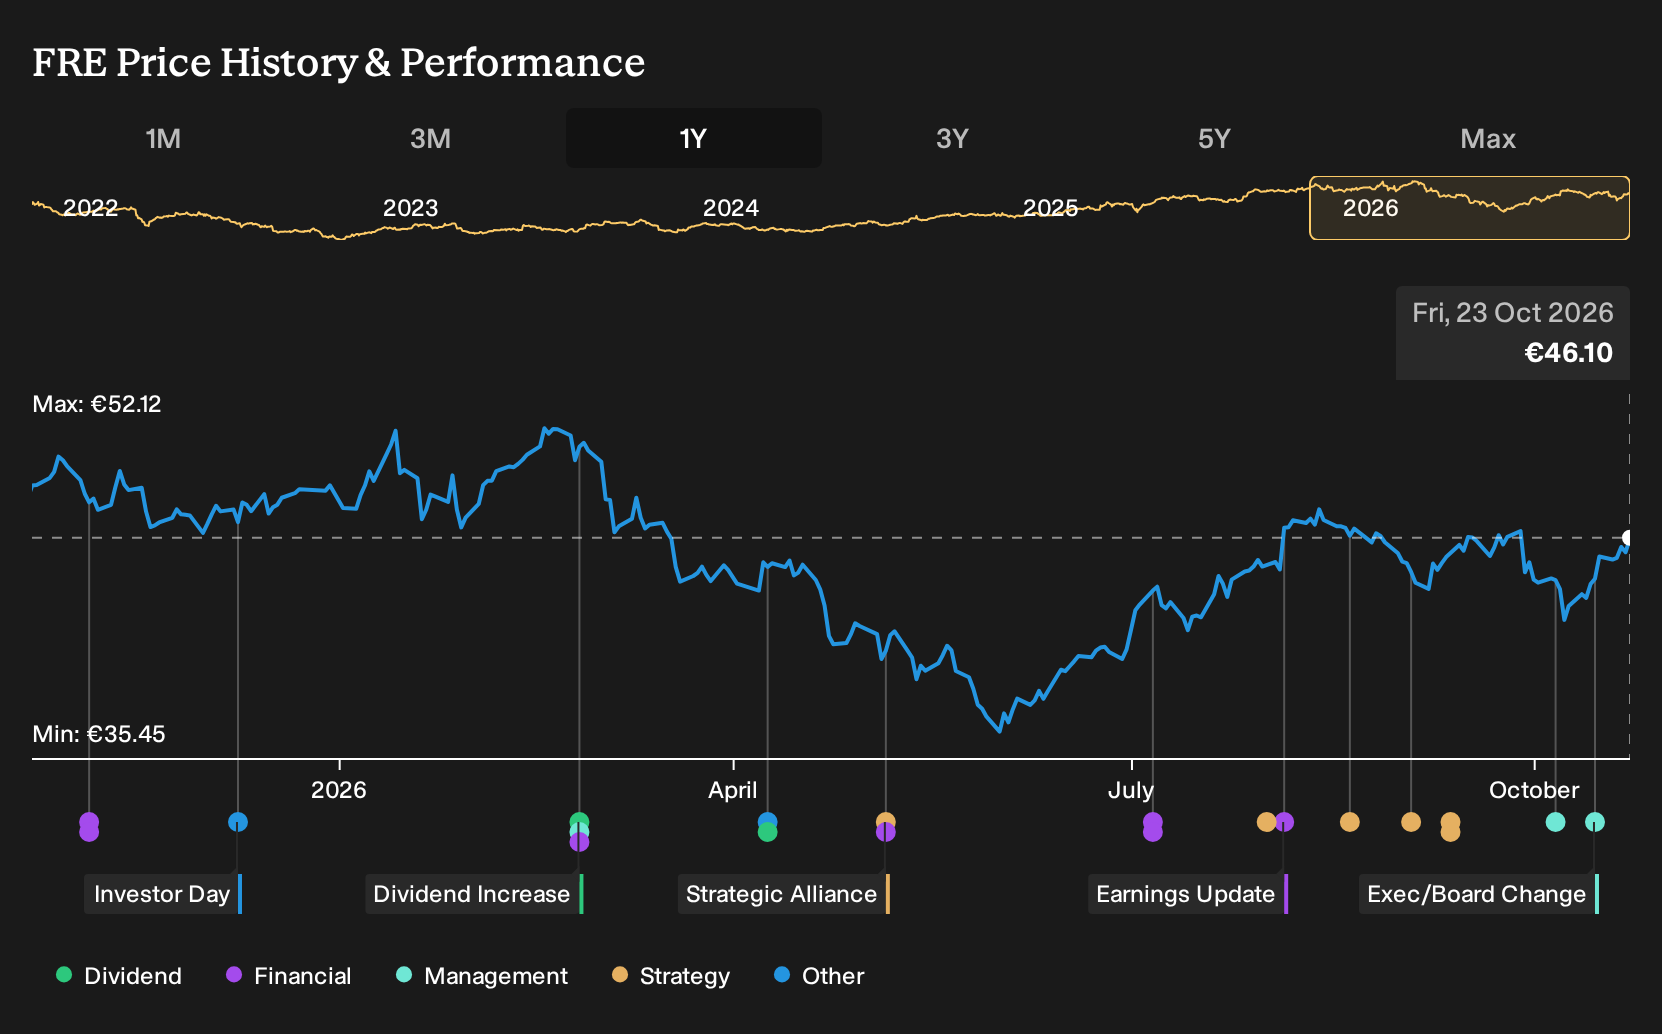
Exploring Other Perspectives
Fair value estimates on Fresenius SE KGaA from the Simply Wall St Community span roughly €55.59 to €124.97 across 2 individual assessments, which shows how far apart private investors can be on the same stock. This board reshuffle and Nutrition carve out could influence how earnings expectations are viewed, so explore several viewpoints before forming your own stance.
Explore another Fresenius SE KGaA fair value estimate, including one that suggests it could be worth just €55.59!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider your own analysis and judgment.
- A great starting point for your Fresenius SE KGaA research is our analysis highlighting 3 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Fresenius SE KGaA. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Fresenius SE KGaA's overall financial health at a glance.
Looking For More Ideas Beyond Fresenius SE KGaA?
If the Fresenius SE KGaA story has you rethinking your portfolio mix, it can help to scan a wider field of candidates and pressure test your thesis against how other businesses score on quality, valuation and risk.
- For investors who want potential bargains with solid fundamentals, start with 194 high quality undervalued stocks that combine healthier balance sheets with pricing that may look appealing on common valuation checks.
- If capital preservation matters just as much as return, narrow the universe to 221 resilient stocks with low risk scores that screen well on financial stability and lower risk scores.
- For those hunting for underfollowed stories, consider 612 high quality undiscovered gems where fundamentals look strong but market attention still appears limited.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com