
ZoomInfo Technologies (GTM) Expands Its AI Integrations, Is A 56% Undervalued View Justified?
ZoomInfo Technologies (GTM) has rolled out a cluster of AI-focused integrations, including a native connector with Exa, Salesforce’s Hunter agent partnership, Workbounce-powered GTM.AI extensions, and an n8n node, expanding where its B2B data can actually be used.
For context, ZoomInfo Technologies shares have bounced hard in the short term, with a 41.23% 90 day share price return and a 16.00% 30 day share price return, yet total shareholder return is still down 60.93% over one year and 93.53% over five years. This signals recent momentum building against a much weaker longer term record as these AI and agentic partnerships land.
Scan how ZoomInfo Technologies compares with other AI-focused automation plays by reviewing the hand-picked 55 AI infrastructure stocks that powers next generation enterprise workflows.
Bulls view ZoomInfo Technologies as a reset AI infrastructure play after a steep multi year slide. Bears see a structurally impaired data vendor in a crowded field. Which story does the current valuation appear to support?
Most Popular Narrative: 56% Undervalued
Against a last close of $4.35, the most followed narrative puts ZoomInfo Technologies at a Fair Value of $9.99, framing today's move as a bet on cash generation and cost discipline more than top line acceleration.
The acquisition of DoubleO.ai and the focus on orchestrating multi agent workflows around proprietary go to market data create room for ZoomInfo Technologies to charge for higher value decisioning and automation rather than only raw data access, which could affect average contract value and operating margins.
See why 9 investors see ZoomInfo Technologies as 56% undervalued.
The narrative leans on a 12.51% discount rate and assumes earnings swing from a loss of $541.0 million to $366.1 million by 2029, with profit margins moving from deeply negative to 29.8%. It also factors in share repurchases that would reduce the share count and concentrate any future earnings on fewer shares, which can materially change per share metrics even if total profit only tracks analyst expectations.
Investors weighing that story against ZoomInfo Technologies' history of losses and a forecast 1.8% annual revenue decline over the next three years are essentially deciding whether a leaner cost base, workflow centric AI products, and capital returns can offset pressure on traditional seat based contracts. The gap between the current $4.35 price, the $4.58 consensus target, and the $9.99 Fair Value used in this thesis reflects how differently the market and the bullish cohort currently score those execution risks.
Result: Fair Value of $9.99 (UNDERVALUED)
Still, the bullish ZoomInfo Technologies story can unravel if net revenue retention stuck at 89% signals deeper churn, or if AI driven alternatives further pressure contract values.
Find out about the key risks to this ZoomInfo Technologies narrative.
Another View: ZoomInfo Technologies Through A Simple Sales Multiple
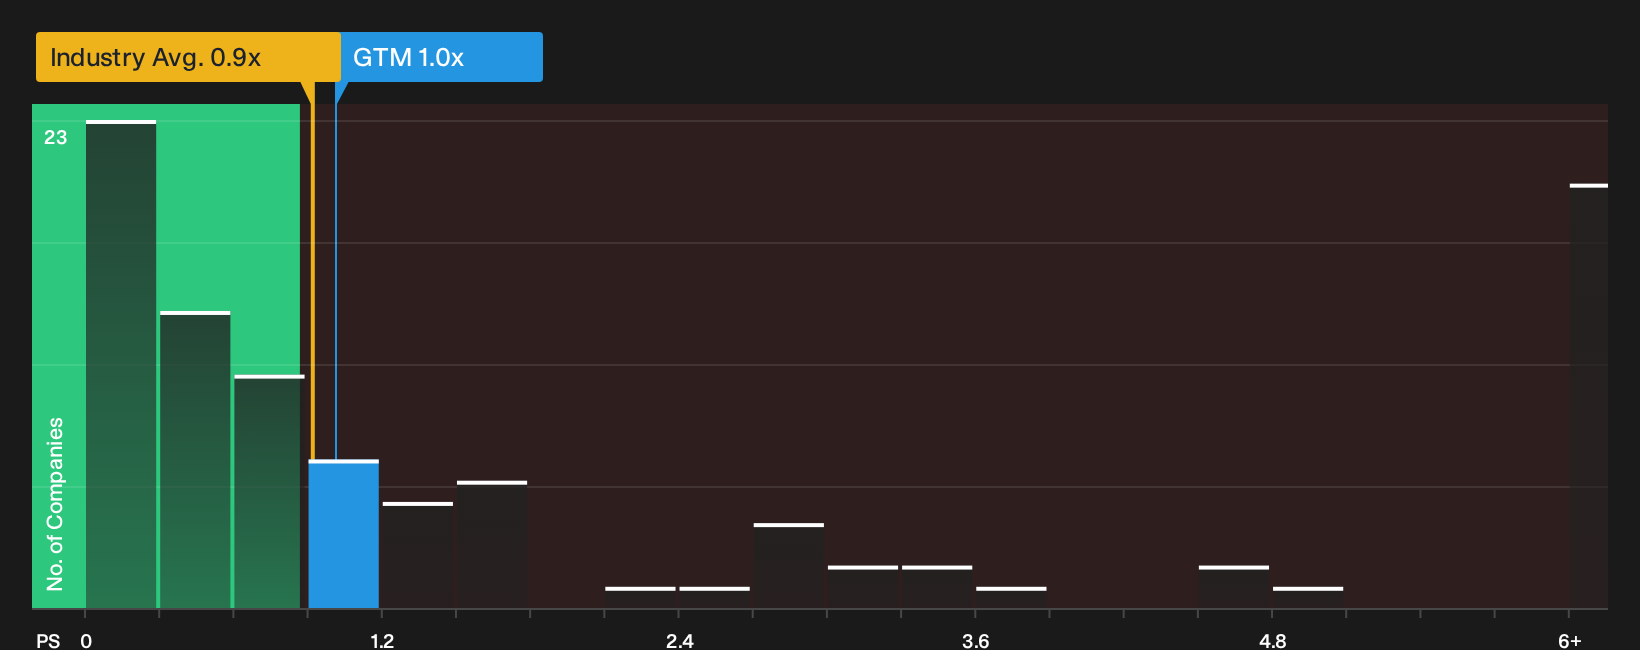
The story looks different once price is compared to sales. ZoomInfo Technologies trades on a P/S of roughly 1x, while peers in US Interactive Media and Services average about 0.9x and the fair ratio sits higher at 1.1x. Is that small gap a cushion or a warning for you?
To see how that P/S profile fits into a fuller valuation picture and where the numbers could shift next, take a look at See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around ZoomInfo Technologies are clear, with investors split between risk and recovery, so move quickly, review the numbers, and weigh both the 2 key rewards and 1 important warning sign
Looking for more investment ideas beyond ZoomInfo Technologies?
If ZoomInfo Technologies has sharpened your focus on valuation, do not stop here. Broaden your watchlist with a few targeted idea generators built around clear fundamentals.
- Target potential mispricing by scanning 29 high quality undervalued stocks that combine strong fundamentals with room for sentiment to catch up.
- Build staying power into your portfolio by reviewing a list of solid balance sheet and fundamentals (24 results) that can better handle tough conditions.
- Get ahead of the crowd by checking a curated pool of 21 high quality undiscovered gems before attention and pricing fully catch up.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com