
Stagwell (STGW) Expands Its Europe Growth Team, Is The Valuation Case Still Convincing?
Why this leadership move at Stagwell matters for investors
Stagwell (STGW) just reshaped its European leadership, appointing Nagmeh Taheri as Chief Growth Officer for Media & Commerce in Stagwell Europe, with a brief to drive new business across the region.
The hire comes after a series of launches in the Media & Commerce segment, including Stagwell Media and new tools on the Stagwell Media Platform. Together, these developments signal management attention on scaling European media capabilities.
Recent leadership and product moves come alongside a strong run in the Stagwell share price, which has a 30 day share price return of 7.93% and an 89.85% year to date share price return. The 3 year total shareholder return of 111.79% points to longer term momentum that investors are still weighing.
Scan how Stagwell's momentum and leadership refresh compares with other media and marketing players by reviewing our hand picked 21 high quality undiscovered gems in the sector.
Stagwell shares have run hard while still trading below both analyst targets and some intrinsic value estimates. Does that gap point to lingering caution, or does it suggest a genuine margin of safety before fair value closes in?
Most Popular Narrative: 16.2% Undervalued
The most followed narrative estimates Stagwell's fair value at $10.71, above the last close of $8.98. This framing puts recent leadership moves in a valuation context that assumes meaningful progress in earnings and cash flow over time.
Expansion and integration of proprietary digital and martech platforms (such as Code and Ink, and the "machine") are creating higher-margin, recurring revenue streams and improving operational efficiencies, which should drive net margin expansion.
Effective execution on tech-driven cost savings and operational synergies, including automation and back-office consolidation, is already resulting in improved free cash flow and lower leverage, which should boost earnings and support shareholder value via buybacks.
See why 6 investors see Stagwell as 16% undervalued.
Result: Fair Value of $10.71 (UNDERVALUED)
Still, the bullish Stagwell story leans heavily on better media execution and smooth integration of past acquisitions, and any stumble there could quickly challenge that 16.2% undervaluation case.
Find out about the key risks to this Stagwell narrative.
Another View: What Stagwell's P/E Is Telling You
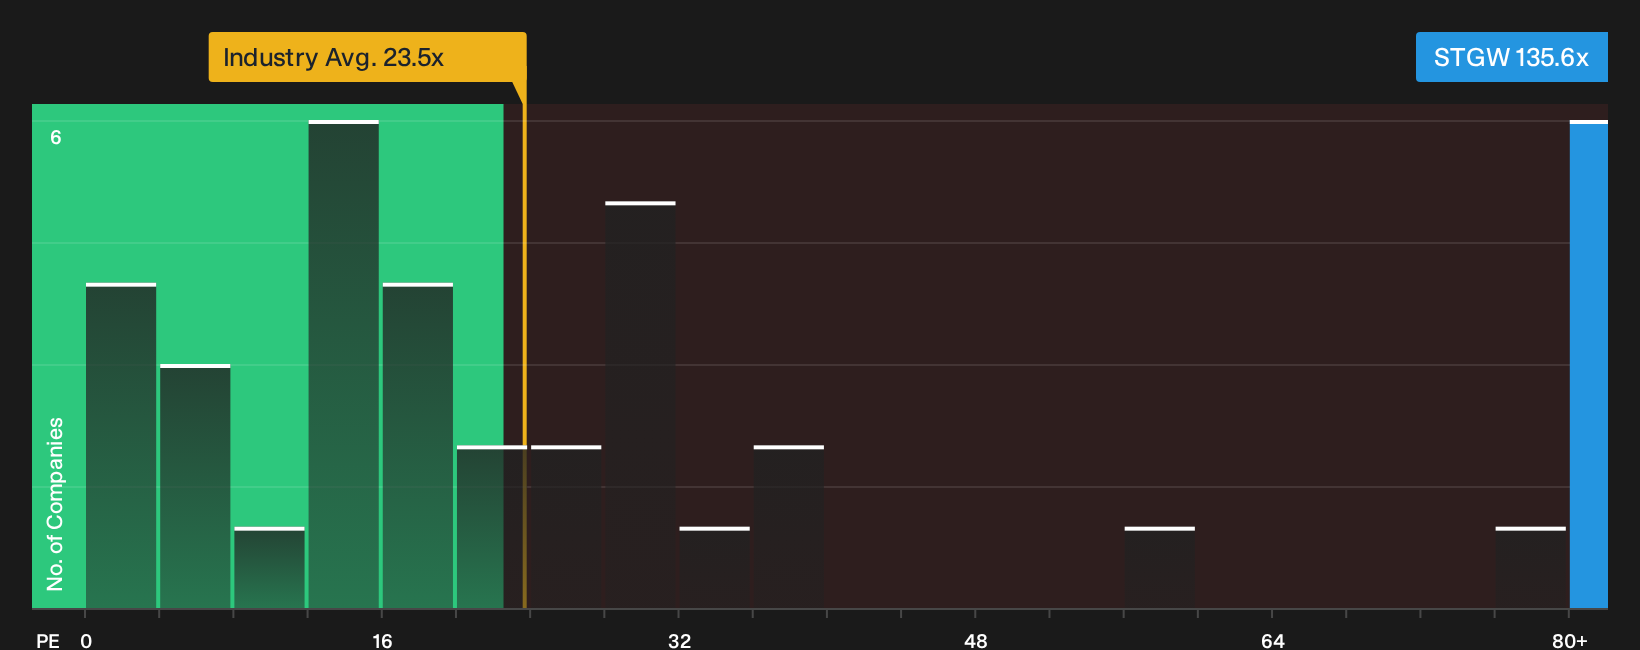
The first narrative leans on future earnings and fair value at $10.71. A different lens looks at what investors are already paying today. Stagwell trades on a P/E of 135.6x, compared with 23.5x for the US Media industry and 36.8x for peers.
That gap is wide. The fair ratio sits at 31.4x, far below the current multiple. For holders, this points to meaningful valuation risk if sentiment shifts toward that fair ratio. The key question is whether future execution can keep investors comfortable paying such a premium.
See what the numbers say about this price, find out in our valuation breakdown. See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed on the story so far and wondering whether current enthusiasm around Stagwell is justified. Act quickly, examine both sides of the data carefully, and rigorously pressure test the 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Stagwell?
Do not stop your research with Stagwell. Broaden your watchlist with focused screens that surface different types of opportunities other investors may be ignoring.
- Target future upside potential by reviewing companies flagged as high quality yet still priced for value using our 29 high quality undervalued stocks.
- Strengthen your income stream by scanning for payouts that may offer resilience with the 5 dividend fortresses.
- Reduce portfolio stress by concentrating on financially sturdy businesses through the list of solid balance sheet and fundamentals (24 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com