
Top 3 Undervalued Stocks To Watch In October 2026
Energy costs are back in focus as higher oil prices and geopolitical risks keep inflation pressures alive, and that pushes investors to pay closer attention to what truly drives resilience. Reliable cash generation quietly matters more when money is not free and borrowing stays expensive. In this piece, you will see three stocks where current prices sit below their estimated cash flow value, based on SWS DCF work.
The three ideas highlighted below are only a sample, with the full screen surfacing 89 more businesses where discounted cash flow work points to similarly interesting risk reward setups that are not covered here. To see the broader field, head straight into the Undervalued Stocks Based On Cash Flows screener to identify, filter and analyze the cash flow stories that fit your own criteria.
NVIDIA (NVDA)
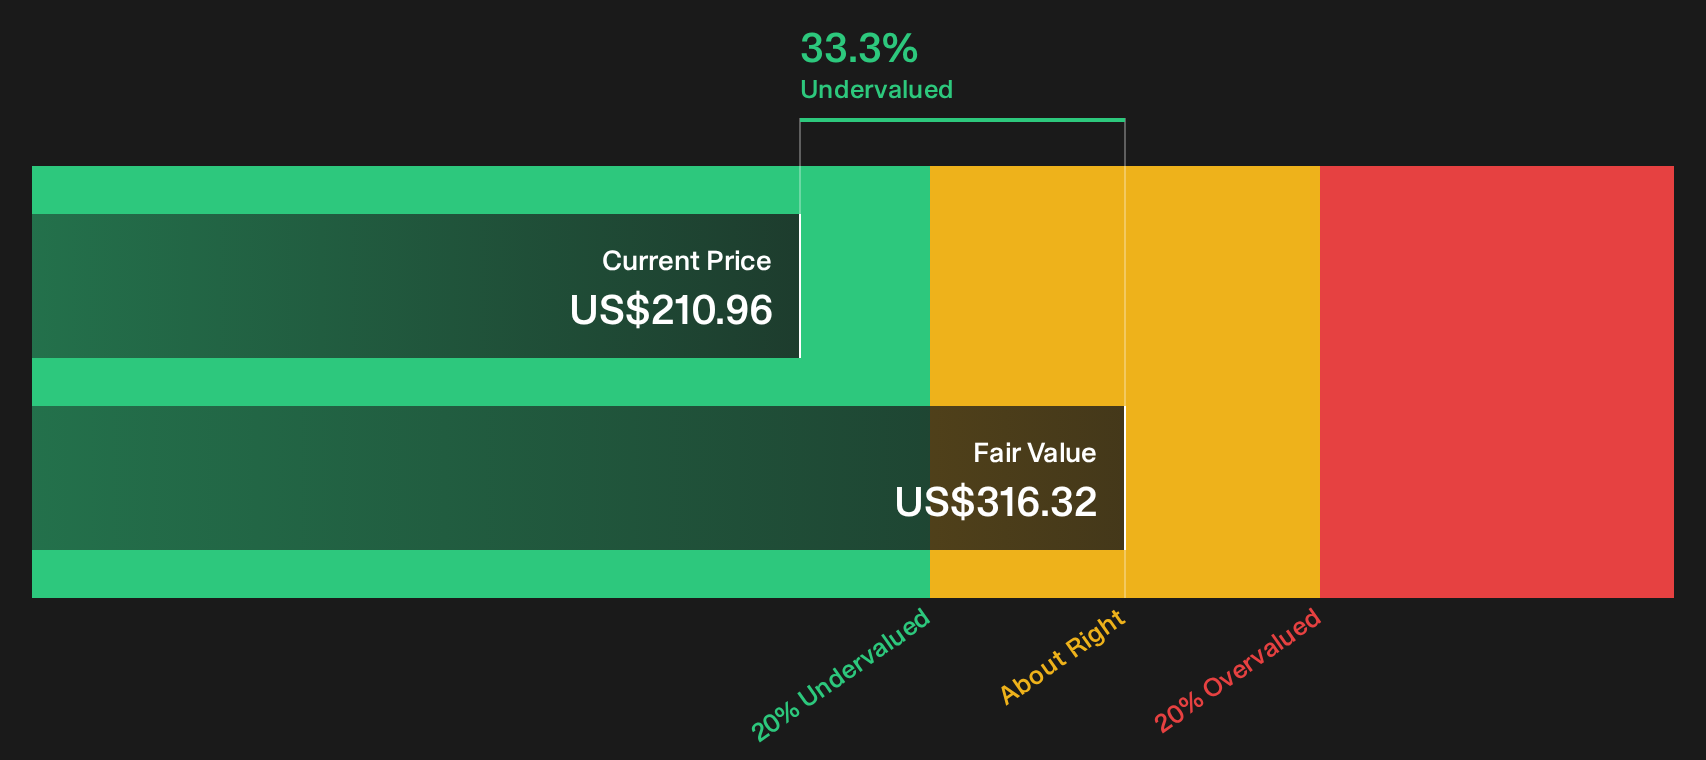
NVIDIA is best known for AI chips that power data centers, gaming rigs, and advanced automotive systems, with the Compute & Networking segment generating about US$275.4b in revenue against US$27.6b from Graphics, and the business valued at roughly US$5,094.1b by market cap.
For this screener, NVIDIA matters because its AI data center hardware and software are tightly linked to cash-generating workloads, yet the stock is still being priced below SWS’s estimate of its cash flow value. This puts a spotlight on how durable that advantage really is.
"Uptake of an open-source/cheaper/better platform than Nvidia's CUDA would heavily undermine Nvidia's moat and enable any sizeable firm to directly engage semiconductor manufacturers, such as TSMC, to produce their own chips, stealing away Nvidia's high margin products."
What happens to those rich margins and the whole cash flow story if a single key assumption about the software grip on AI shifts?
If that software grip is what you are really testing, read the full narrative for NVIDIA to see how Nvidia's moat, cash flows and competition story could be decoupling.
Berkshire Hathaway (BRK.A)
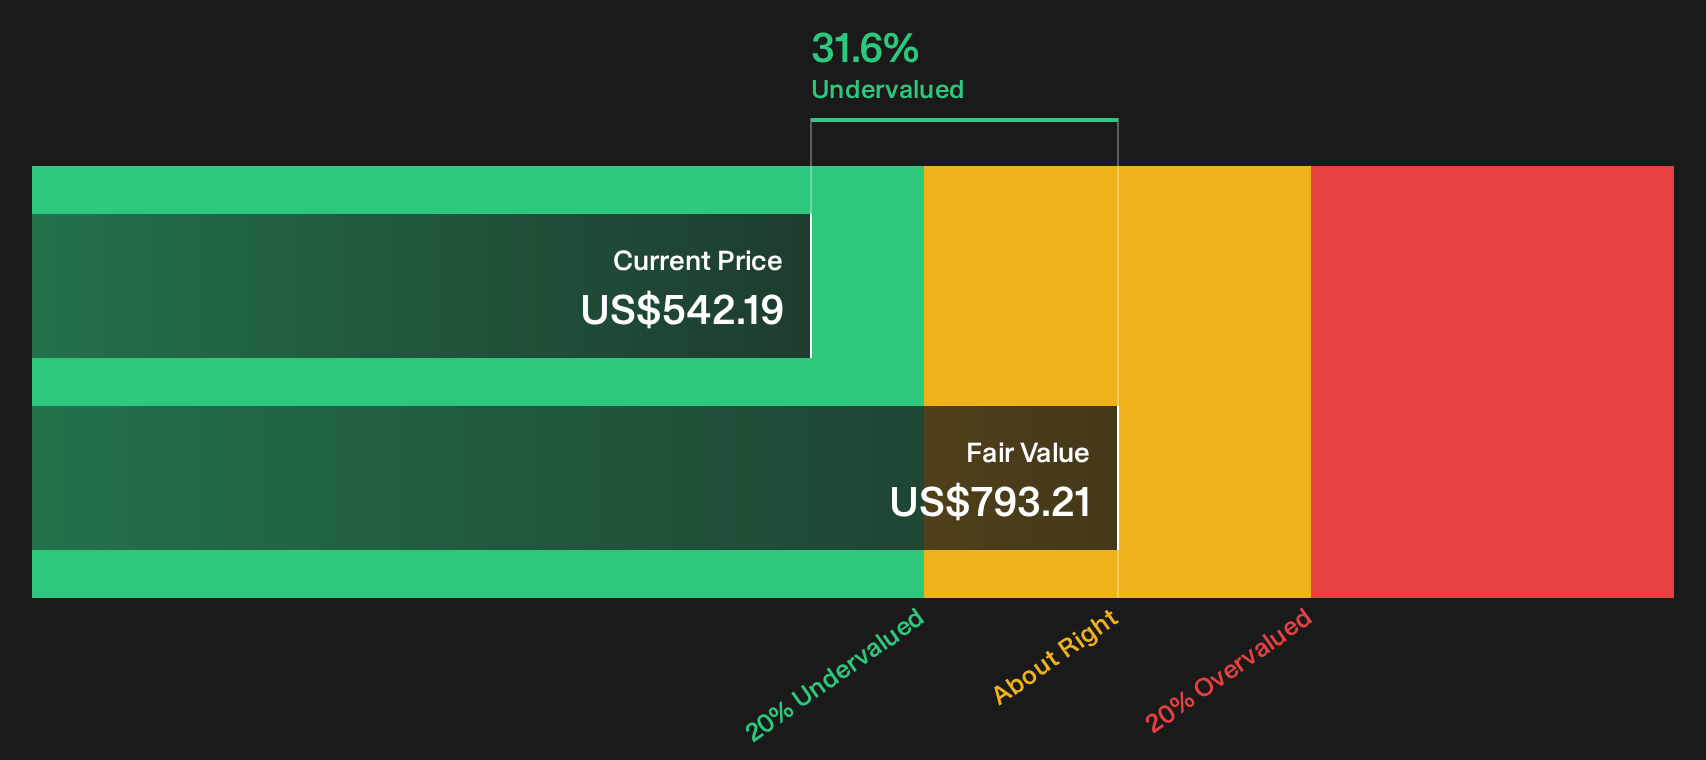
Berkshire Hathaway is a sprawling conglomerate built around insurance operations that generate significant underwriting and investment cash flows, feeding the broader collection of rail, energy, manufacturing, retail and services businesses that together produce well over US$300b in annual revenue and support a roughly US$1.16t market value.
"The cash fortress: Berkshire's cash and short-term Treasuries hit a staggering, record-breaking $397.4 billion."
What that cash pile actually earns and how aggressively Berkshire Hathaway chooses to redeploy it could quietly influence long term cash-flow power.
Those choices are exactly what the full narrative for Berkshire Hathaway unpacks, revealing how Berkshire Hathaway’s cash fortress could accelerate opportunity or quietly mask emerging risks.
Netflix (NFLX)
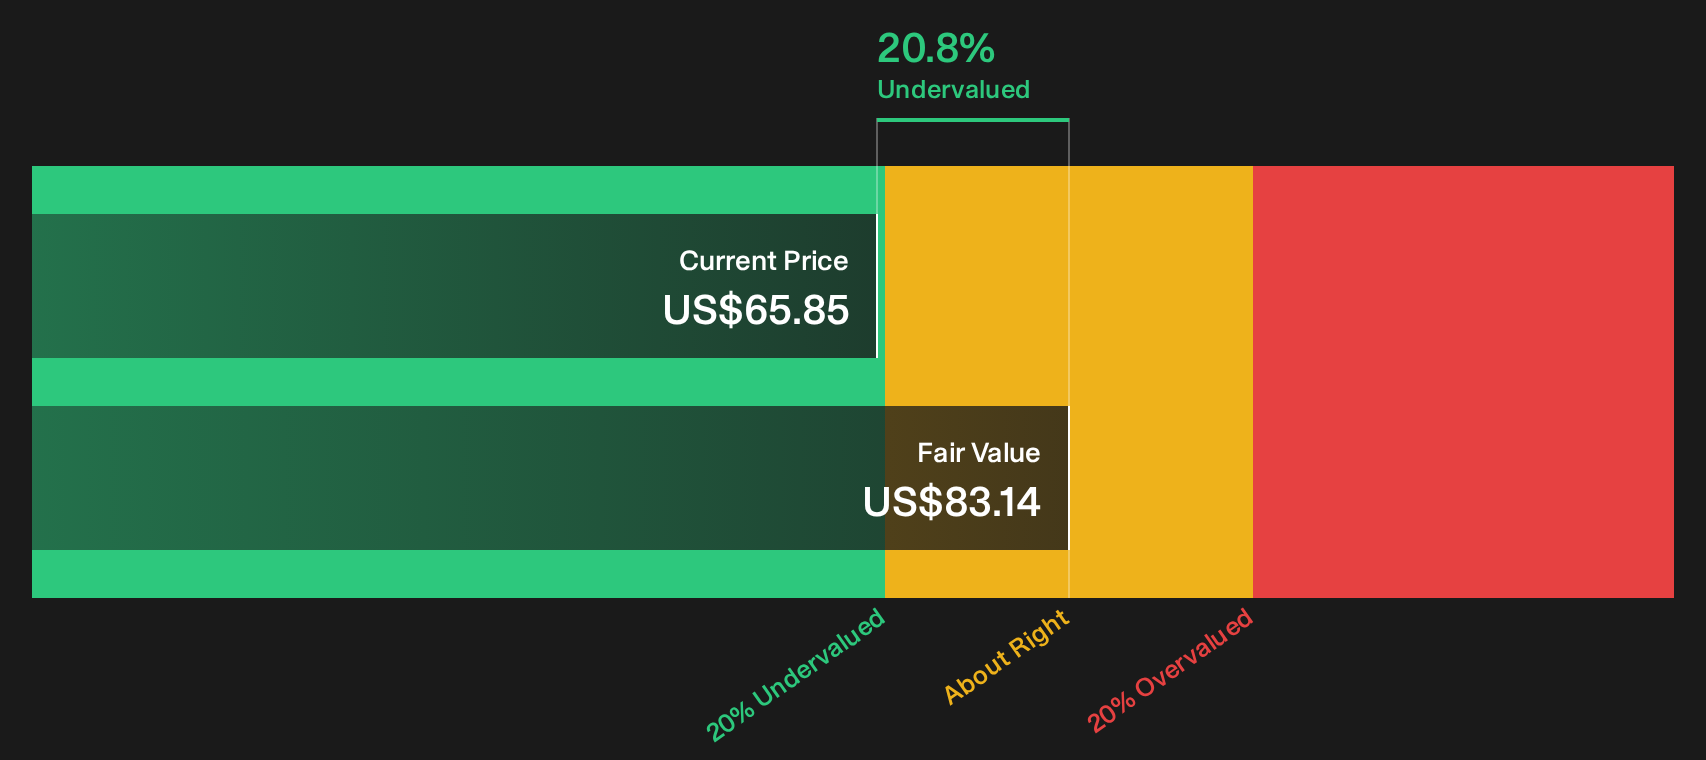
Netflix runs a global streaming platform built on monthly subscriptions, where recurring membership payments drive the cash flows that matter for this screener. The business generated about US$49.7b from its streaming entertainment service and carries a market value near US$270.4b.
For value hunters focused on cash flow, Netflix offers something different from one-off box office hits. This is a subscription engine built on recurring payments, bundled content, and an ads tier that all feed into how much free cash the service can generate over time.
"The bull case is still very real, but it needs more than a good quarter. It needs proof that ads become economically meaningful, that pricing remains sticky, and that margin expansion can continue without damaging engagement."
What really decides the outcome is how one quiet pressure on its business model tilts the balance between healthy growth and squeezed profitability.
If that pressure point matters for your portfolio, read the full narrative for Netflix to see whether Netflix’s model is quietly stalling or setting up for accelerating cash generation.
Seeking Alternatives Before The Crowd Moves
Fresh ideas do not wait. Breakout momentum, dropping entry windows, and under-the-radar-for-now opportunities can be gone once everyone is watching, so act now.
- Spot reliable cash engines and let the list of solid balance sheet and fundamentals (24 results) guide you toward companies where strong finances back the story before momentum starts flying.
- Chase early strength in income payers and use the 5 dividend fortresses to find yield-heavy candidates before their payouts get fully caught in the spotlight.
- Track future-facing infrastructure and scan the 42 power grid technology and infrastructure stocks for potential winners in grid upgrades while the theme is still building quietly.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com