
Is YIT Oyj (HLSE:YIT) Fully Valued After Its Kupittaa Core Project Expansion?
YIT Oyj (HLSE:YIT) just agreed with the City of Turku on extra work for the long running Kupittaa Core project, expanding street, utility and public space construction in the area.
YIT Oyj’s latest Kupittaa extension lands at a time when momentum in the share price has been rebuilding, with the stock up 43.46% on a 90 day share price return and a 53.78% total shareholder return over the past year, even though the 5 year total shareholder return is slightly down at 4.69%.
Spot opportunities similar to YIT Oyj's Kupittaa project momentum by scanning our hand picked 612 high quality undiscovered gems that are building value on strong underlying fundamentals.YIT Oyj’s surge around the Kupittaa project puts a simple tension on the table. Are investors finally catching up with the underlying business, or has sentiment simply run ahead of what the valuation supports?
Most Popular Narrative: 3% Overvalued
Analysts currently place YIT Oyj’s fair value at €4.16, just under the recent €4.28 close. This suggests expectations are already demanding given the latest Kupittaa news and wider project wins.
Strong momentum in the Infrastructure segment, including a robust order book (20 months of work secured) and focus on complex, sustainability-focused projects, is expected to enhance recurring revenues and support long-term margin improvement. Strategic investments in operational efficiency, such as improved supply chain and customer insight tools, combined with a growing focus on green, energy-efficient construction, provide a competitive advantage that should support higher net margins and earnings resilience amidst sector digitalization and sustainability trends.
See why 6 investors see YIT Oyj as 3% overvalued.
The widely followed narrative builds that €4.16 value using a 9.05% discount rate and assumes YIT Oyj can move from a loss of €75.0 million today to earnings of €98.1 million by 2029, with margins shifting from a negative 4.3% to about 4.0%. To make those cash flows line up with the current consensus, the shares would need to trade on a future P/E of 12.7x, which is well below the current 26.4x level for the wider GB Consumer Durables space.
Investors weighing the Kupittaa extension and the broader pipeline against this setup are really judging whether those long dated projects and residential launches justify paying a price that already sits a little above that €4.16 narrative fair value. The more confidence you have in the 12.1% annual revenue growth assumption and the margin repair, the more that small 3% premium to fair value might look acceptable. Any doubts about project timing, debt costs or Finnish housing demand make that premium harder to defend.
Result: Fair Value of €4.16 (OVERVALUED)
Still, that story frays quickly if Finnish housing demand stays weak, or if YIT Oyj’s high net debt and gearing keep financing costs biting into profits.
Find out about the key risks to this YIT Oyj narrative.
Another View: What YIT Oyj’s Sales Multiple Is Saying
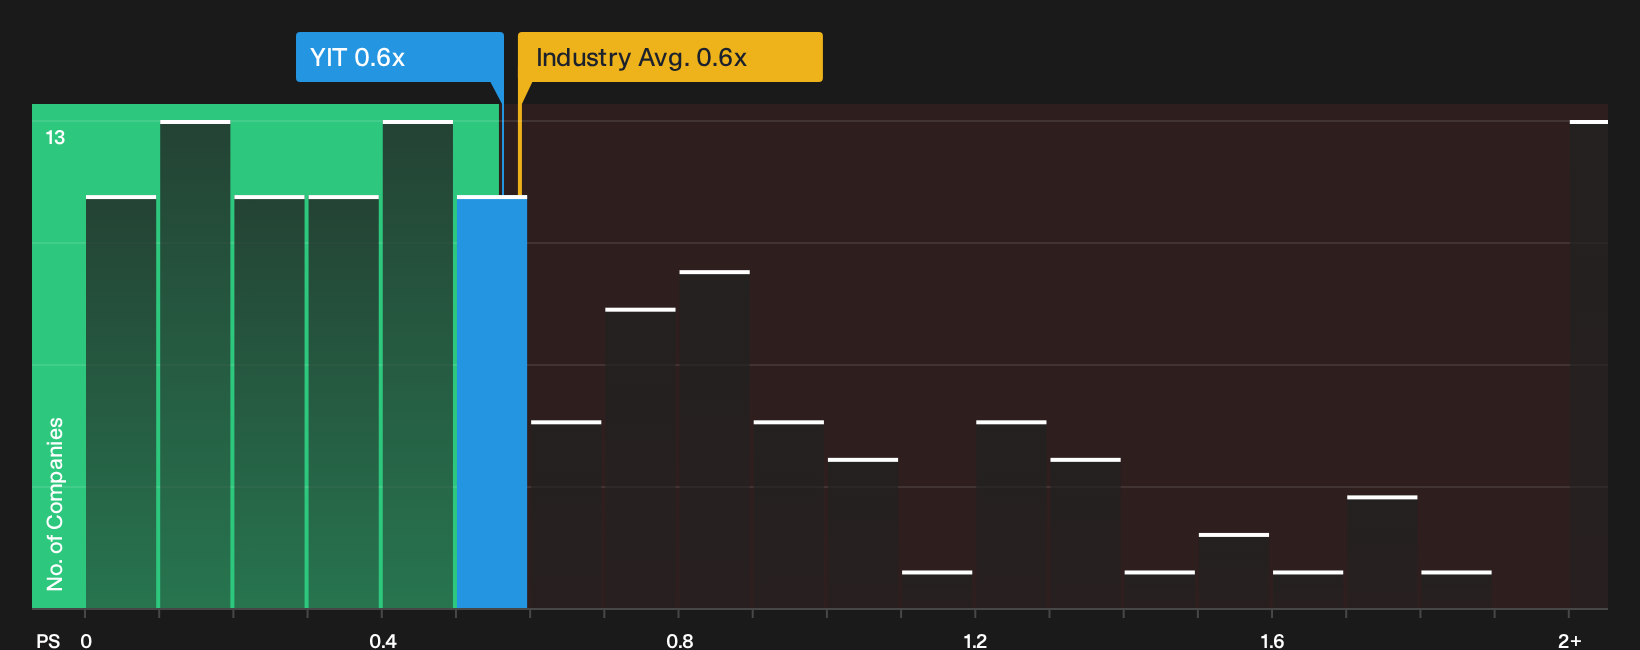
That 3% premium to the €4.16 fair value sits awkwardly next to how the market prices YIT Oyj’s sales. On a P/S of 0.6x, the stock trades well below peers at 1.8x and far under a fair ratio of 3.2x. Is the discount pointing to risk that the DCF misses, or to opportunity the consensus is not fully recognising?
See what the numbers say about this price in our valuation breakdown See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages in the YIT Oyj story so far, right? If you want to move fast and judge the balance of risk and upside for yourself, start by weighing the 2 key rewards and 2 important warning signs.
Looking for more investment ideas beyond YIT Oyj?
Do not stop with a single stock. Broaden your watchlist with fresh ideas that match your risk tolerance, return goals and time horizon so you are not relying on one story.
- Target higher potential upside by scanning a curated set of smaller companies through the 122 elite penny stocks with strong financials that combine growth ambition with more disciplined financial profiles.
- Prioritise value and quality together by reviewing the 194 high quality undervalued stocks that pair stronger cash generation with pricing that still reflects a discount.
- Aim for steadier compounding by tracking the 229 dividend fortresses that focus on higher yields backed by resilient cash flows.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com