
The Call NOV Bulls Got Right
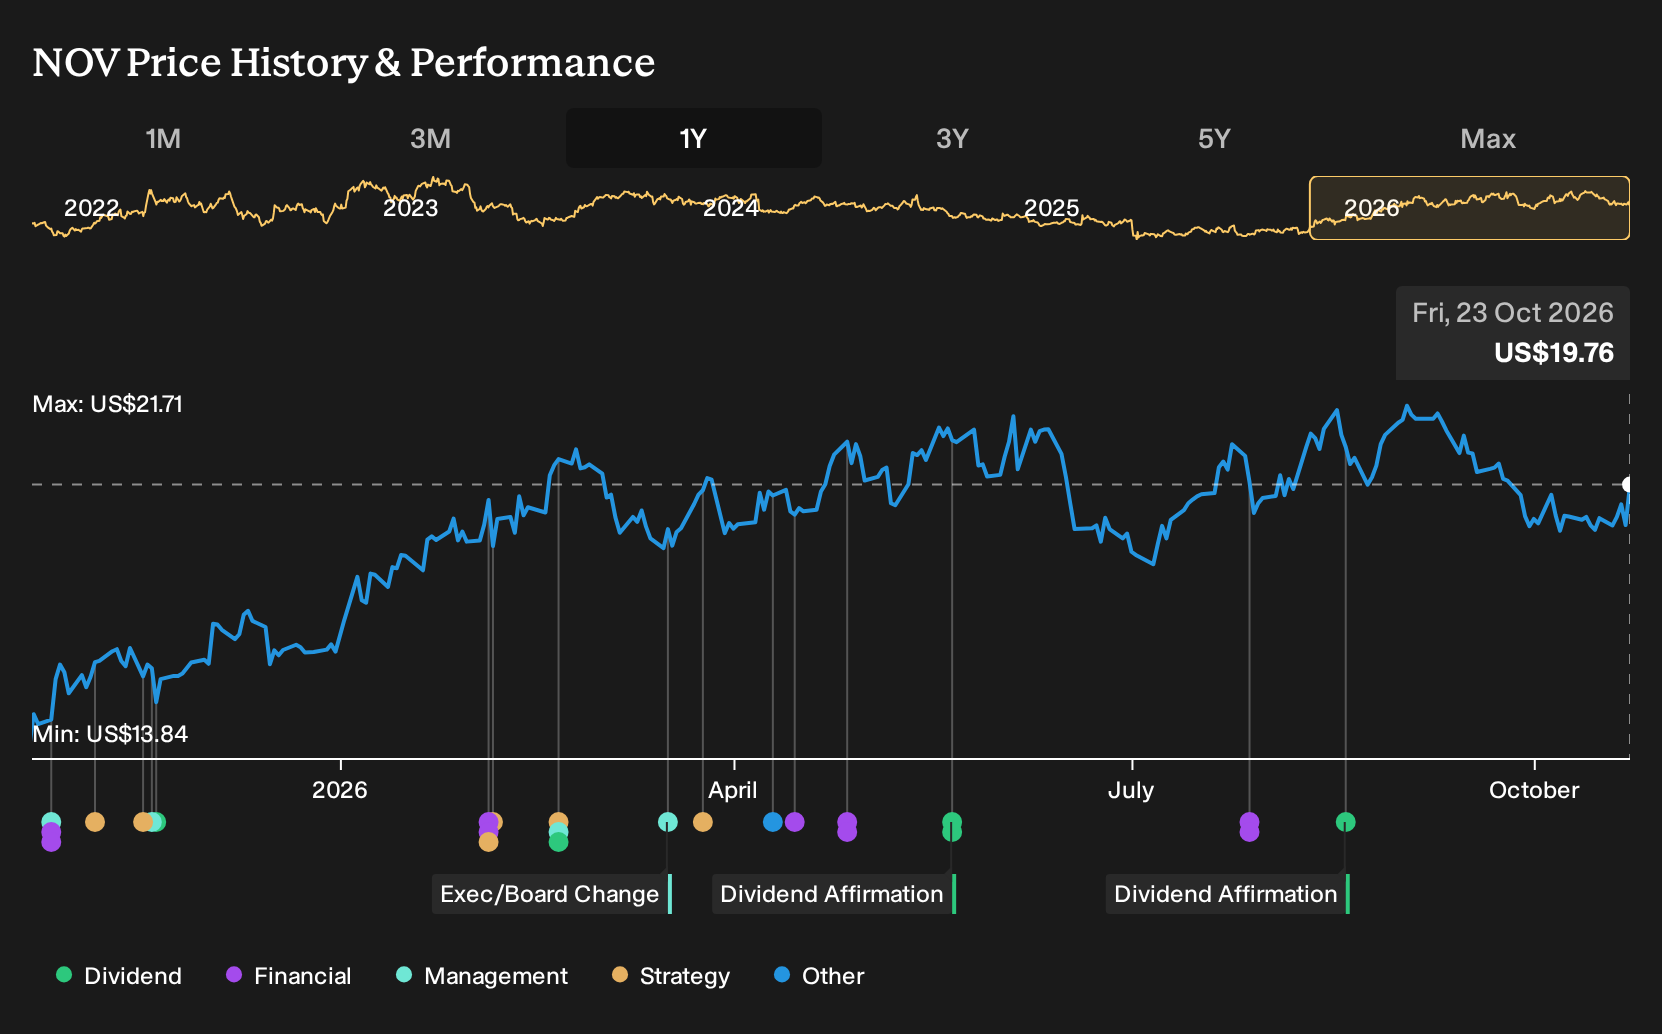
NOV’s recent contract to supply flexible pipe for Equinor’s first NCS2035 tieback projects put a very specific product line in the spotlight, even as quarterly results showed revenue and profit moving in different directions and margins edging higher. Investors who held NOV over the past year are up 46.0%, including dividends. If you were deciding back on 23 October 2025, what would you have needed to believe about offshore orders, decarbonization risk, and future margins?
On Simply Wall St, a Narrative is an investor's thesis written down: the reasoning, plus the numbers it rests on. Run those numbers and you get an estimated Fair Value.
The easy part of this move is behind NOV. Zero in on 29 high quality undervalued stocks for companies trading below our estimates.
The Two Stories NOV Investors Had To Weigh
The shares cost US$14.08 at the start of the period, and you were choosing between two very different stories about where NOV might be heading.
On the bullish side, the Narrative set Fair Value at US$15.38 and leaned on offshore and international activity. It assumed revenue growth of 0.7% a year and a profit margin reaching 6.1%, with NOV earning that on a future P/E of 11.6x.
The bearish story put Fair Value at US$11 and focused on decarbonization risk. It argued that heavy exposure to traditional oilfield equipment could mean declining order volumes and shrinking profitability if oil demand fell over time.
What The Results Changed For The NOV Thesis
NOV’s Q2 2026 report showed revenue at US$2,134m versus US$2,188m a year earlier, while net income ticked up from US$108m to US$112m and net margin moved from 4.9% to 5.2%. That modest margin lift leans toward the bullish case that assumed higher profitability, although the softer top line and ongoing sector challenges kept the picture mixed rather than settled.
The takeaway for you is simple. When a story hinges on future margins, track net income and net margin side by side with revenue, and check whether profitability is improving because of genuine efficiency or just weaker sales volume.
What NOV's Recent Run Already Prices In
NOV now trades at US$19.76, after a 46.0% gain over the past year from US$14.08. The selected Narrative still places its Fair Value below that share price, which frames today’s level as already baking in a fair amount of execution progress.
The focus has shifted from demand risk to whether NOV can convert its offshore backlog and digital offerings into stronger margins and cash generation. A buyer today would need to believe that cash conversion and profitability improve despite tariffs, higher capital expenditure and softer shorter cycle activity.
"The main factor that has to go right is that NOV converts its offshore and international unconventional backlog, digital and robotics offerings, and cost reduction program into sustainably higher margins and cash generation, despite tariffs, softer shorter-cycle activity, and higher capital expenditure."
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all
Find Your Own Contrarian Opportunity
By the time a rally makes headlines, you are reading about returns someone else has already earned. Why not go straight to the source and look for your own contrarian opportunity? These three companies trade below our estimated value.
- Company 1 - 33% below our estimate - convert faster subsea tieback opportunities into higher margin, longer duration services contracts.
- Company 2 - 37% below our estimate - expand multidisciplinary consulting work as clients face denser technical, safety and regulatory questions.
- Company 3 - 24% below our estimate - embed AI assistants into core productivity software to deepen usage and subscription revenue.
Those are three of them. See the full list of 24 financially solid companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com