
Learn Why The Bull Case For Belimo Stock Could Change Following UBS Upgrade
- Belimo Holding is seeing data center related HVAC products take a larger share of its business, with these applications accounting for nearly a quarter of first half 2026 sales and drawing fresh attention to the company’s operating mix.
- UBS now frames Belimo’s higher margin data center portfolio as a key driver of its long term forecasts for organic sales and operating profitability, which puts a spotlight on whether this fast growing vertical can sustainably support the wider group’s cash generation.
- Next, the focus shifts to how Belimo Holding’s broader investment narrative lines up with UBS’s emphasis on higher margin data center demand.
Scan for other data center beneficiaries with stronger pricing power and cleaner balance sheets by reviewing our curated list of 55 AI infrastructure stocks alongside BELIMO Holding.
BELIMO Holding Investment Narrative Recap
To hold BELIMO Holding, you need to be comfortable with a business where a growing slice of the engine is data center related HVAC hardware. The appeal is clear: higher value valves, actuators and sensors for energy intensive facilities, plus retrofit work and a premium product mix. The key short term swing factor is whether this data center pipeline actually converts into orders at the pace investors expect.
The biggest operational risk is concentration. Data centers already make up a large share of new growth, so any slowdown in that build cycle or a shift in cooling technology could affect organic expansion and margins. FX and tariff exposure also weigh on near term profitability, although the UBS work mainly reframes expectations rather than changing those underlying risks.
The UBS upgrade is the announcement that matters most for this story because it explicitly ties Belimo Holding’s recent performance to a larger data center opportunity. UBS now models around 12% organic growth per year between 2026 and 2030 and a 25.6% adjusted operating margin by 2030, driven by a richer mix of higher margin data center products.
For investors, that analysis does not change operations on the ground, but it does sharpen the catalyst. Execution on data center projects, capacity expansion in key regions and delivery reliability now carry more weight in how the market interprets each set of results. At the same time, the 3 year share price gain of roughly 114% and DCF work that screens as stretched keep valuation risk very much in play.
BELIMO Holding’s current analyst narrative points to revenues of CHF 1.7b and earnings of CHF 331.3 million by 2029. This setup implies revenue growth of 12.3% per year and an earnings increase of about CHF 126 million from CHF 205.2 million today.
Discover why BELIMO Holding's fair value points to a 33% potential upside to its current price, an opportunity that could diminish quickly.
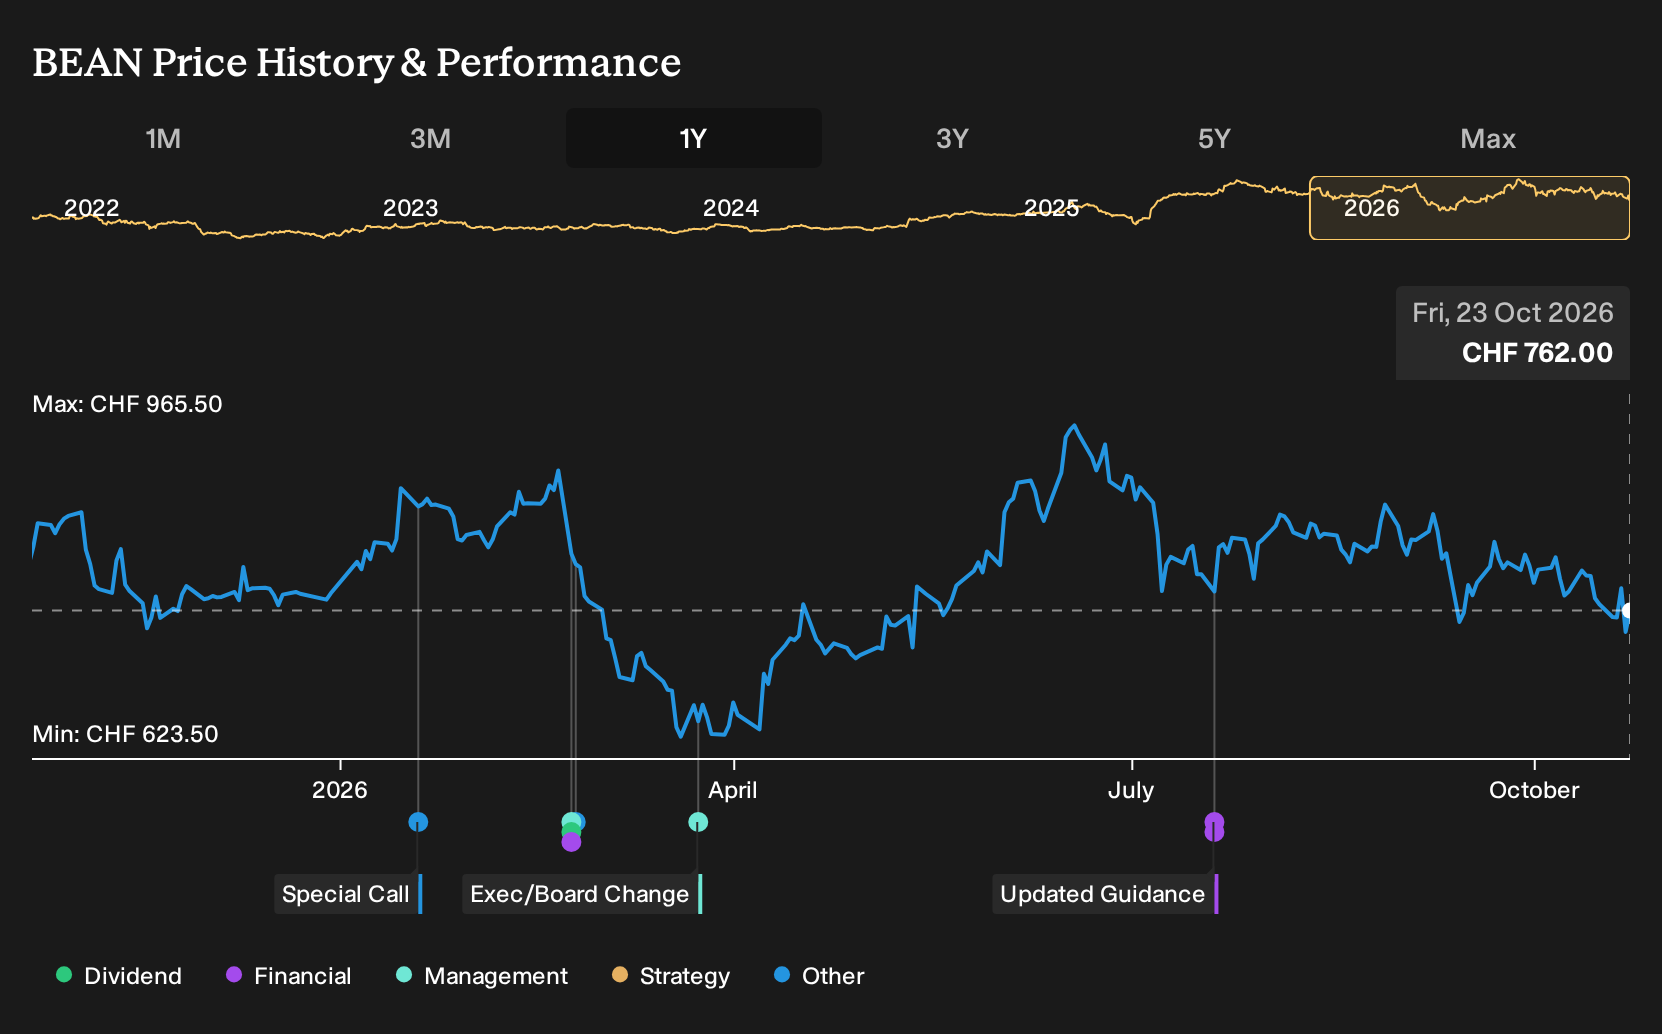
Exploring Other Perspectives
One alternate view puts Belimo Holding’s elevated CapEx front and center. You are told a heavier build out phase could cap free cash flow, which is why the lowest analysts only pencilled in CHF 1.8b of 2029 revenue and CHF 335.4 million of earnings before this UBS upgrade. That gap in opinion is wide. It is worth exploring several scenarios and deciding which story feels more realistic to you as fresh data center news is incorporated into future forecasts.
Explore 2 other BELIMO Holding fair value estimates, including one that suggests as much as 16% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis and judgement.
- A great starting point for your BELIMO Holding research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BELIMO Holding. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate BELIMO Holding's overall financial health at a glance.
Looking For More Investment Ideas Beyond BELIMO Holding?
If the BELIMO Holding story has you thinking about where data center demand, cash generation and balance sheet quality intersect, it can help to widen the lens and compare it with other listed businesses.
The Simply Wall St Screener lets you quickly filter for different traits so you can build a shortlist that matches your own risk tolerance and return goals.
- If durability and lower volatility matter most to you, start with 221 resilient stocks with low risk scores, which combines resilience scores with more measured price swings.
- Income focused investors might prefer cash returns today, so it could be worth reviewing 225 dividend fortresses, which aims to pair higher yields with underlying stability.
- For those hunting for overlooked stories with solid fundamentals, consider scanning 613 high quality undiscovered gems, which may not yet be widely followed by the market.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com