
Earnings Beat Could Reshape The Case For Selective Insurance Group Stock
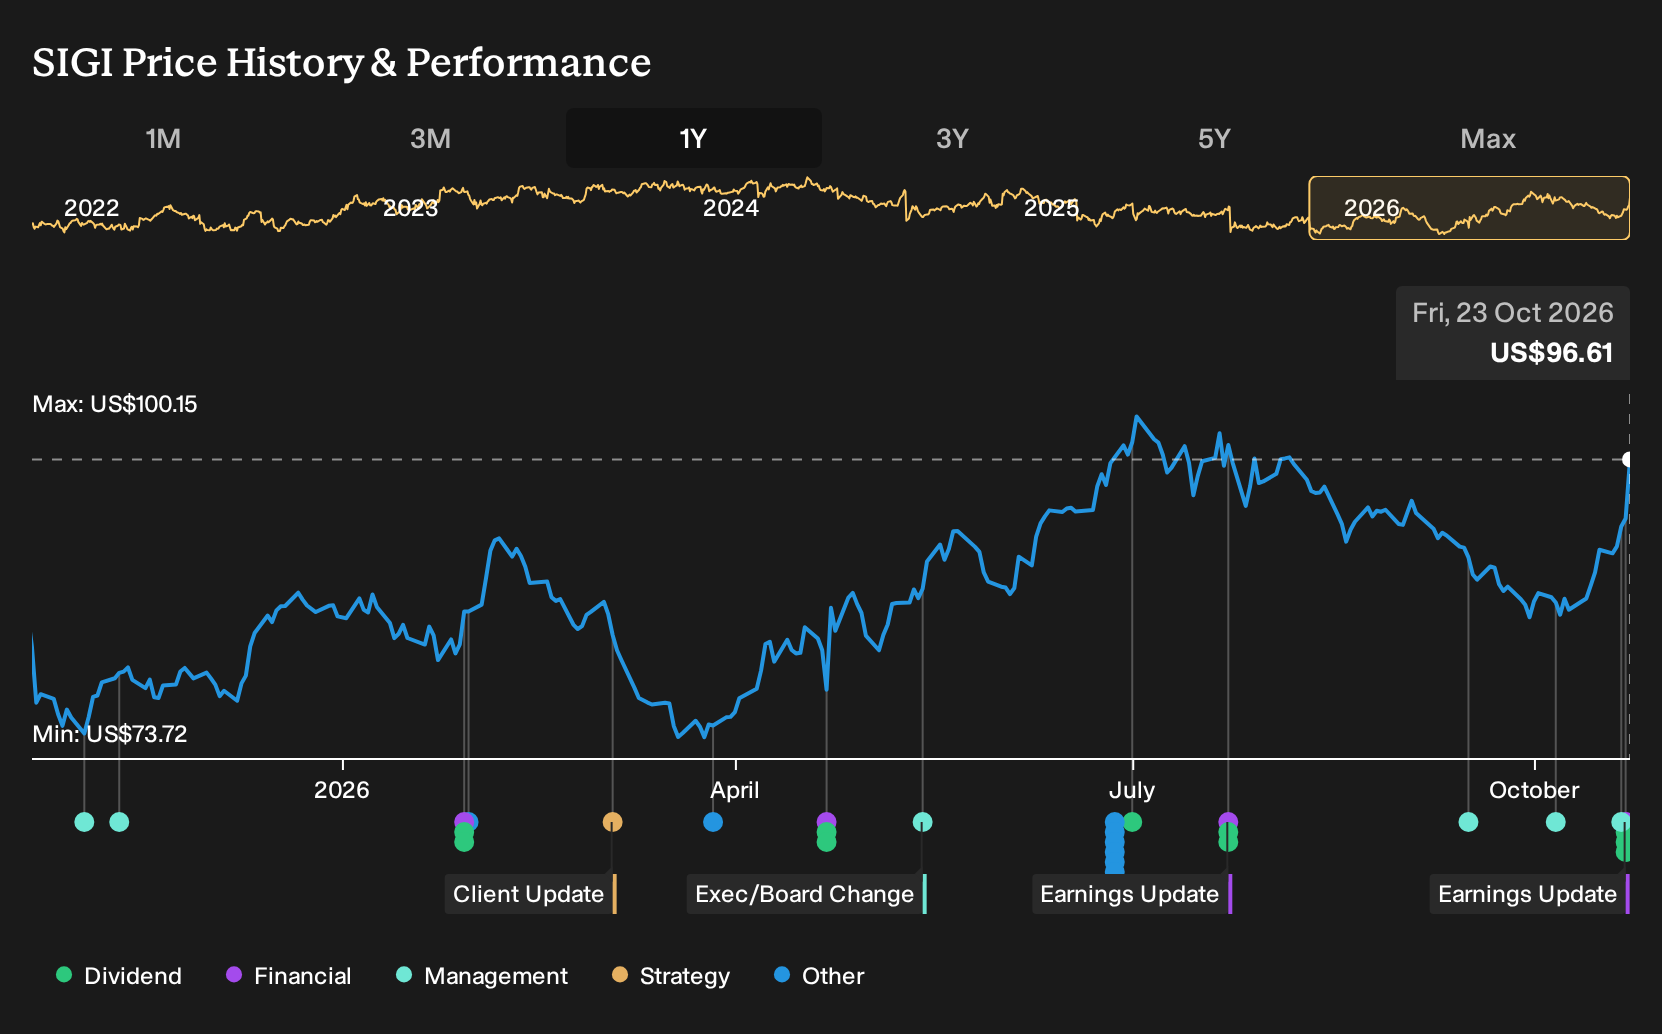
- Selective Insurance Group reported Q3 2026 revenue of US$1,326.3 million with net income of US$128.7 million and diluted EPS from continuing operations of US$2.11, alongside a 12% increase in its common dividend and a new US$200 million share repurchase authorization.
- Results for the first nine months of 2026 showed revenue of US$4,072.3 million and net income of US$355.7 million, which, combined with higher dividends and buybacks, describe how management is using earnings strength to return capital while still focusing on underwriting discipline and investment income.
- Next, the focus shifts to how Selective Insurance Group's higher dividend and new repurchase plan influence the existing investment narrative.
See how Selective Insurance Group's capital returns compare with other insurers by reviewing a curated set of 5 dividend fortresses that prioritize consistent payouts and balance sheet strength.
Selective Insurance Group Investment Narrative Recap
To own Selective Insurance Group, you need to believe disciplined underwriting, careful pruning of weaker books, and technology driven efficiency can offset high casualty loss trends and pressure on commercial auto severity. The latest quarter supports that idea, with a stronger combined ratio and higher net income even as Standard Commercial Lines premiums remain under pressure.
The near term catalyst still sits in execution on re underwriting and rate adequacy across casualty and auto, especially as prior year reserve noise can unsettle results. That risk has not gone away. Recent earnings suggest progress, but casualty severity, regulatory shifts and distribution changes remain the biggest operational overhangs to watch.
The 12% increase in the common dividend to US$0.48 per share is the headline capital return move from Selective Insurance Group. It comes alongside higher net income for both the quarter and first nine months of 2026, and adds to an investment case that already leaned on a reliable payout and earnings growth.
For catalysts, the higher dividend matters because it ties directly to cash generation from underwriting and investment income. It also raises the bar for sustaining profitability while management tightens underwriting in weaker cohorts. If casualty trends or regulatory costs bite harder, the commitment to a larger regular payout could limit flexibility elsewhere.
What The Current Forecasts Assume About Selective Insurance Group
Selective Insurance Group's analyst narrative points to revenues of US$5.5b and earnings of US$575.2 million by 2029, with earnings today at US$488.4 million and a fairly flat expected top line over the next 3 years. That implies earnings would increase by about US$86.8 million from current levels if those estimates prove accurate.
Uncover why Selective Insurance Group's fair value indicates a 5% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Two fair value estimates from the Simply Wall St Community span roughly US$102 to just over US$201, a wide bracket for the same Selective Insurance Group earnings stream. Those views sit beside fresh catalysts including dividend growth, buybacks, and new leadership. Use that spread as a prompt to compare multiple perspectives before committing fresh capital.
Explore another Selective Insurance Group fair value estimate, including one that suggests as much as 108% potential increase from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Selective Insurance Group research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Selective Insurance Group. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Selective Insurance Group's overall financial health at a glance.
Looking For More Investment Ideas Beyond Selective Insurance Group?
If the Selective Insurance Group story has sharpened your thinking about risk, income, and capital returns, you can use that same framework to scan a wider field of opportunities with the Simply Wall St Screener.
- If capital preservation sits high on your list, start with 30 resilient stocks with low risk scores to help keep drawdowns in check while still providing exposure to business growth.
- For investors looking for mispriced quality, broaden your watchlist with a carefully filtered 21 high quality undiscovered gems that combines solid fundamentals with limited market attention.
- If balance sheet resilience matters most to you, anchor your research in a list of solid balance sheet and fundamentals (25 results) so you can focus on companies with the financial strength to handle tougher conditions.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com