
HUTCHMED (China) (AIM:HCM) Closes GSK Licensing Deal, Is It A Bargain Or Fully Priced?
HUTCHMED (China) (AIM:HCM) has closed its exclusive development and license agreement with a GSK subsidiary for cancer drug candidate HMPL-A830, unlocking US$110 million upfront and potential future milestone and royalty income.
The licensing deal lands at a time when HUTCHMED (China)’s share price has gained 30.12% over the past 90 days, even though the 1-year total shareholder return is down 4.85% and the 5-year total shareholder return has declined 50.63%. As a result, recent momentum contrasts sharply with a much weaker long term record.
Scan how this GSK deal compares with other potential oncology opportunities by reviewing the hand-picked 8 healthcare AI stocks that are drawing attention for their work at the intersection of biotech and AI.
HUTCHMED (China) now trades at a steep discount to both analyst targets and some intrinsic value estimates after a sharp 90 day rebound. Is that caution sensible given its patchy shareholder record and new GSK deal?
Most Popular Narrative: 38% Undervalued
On the most followed view of HUTCHMED (China), the share price of £2.16 sits well below a narrative fair value of £3.46. The GSK licensing move therefore fits into an already optimistic long term story that leans on pipeline depth and international reach.
Launches and global expansion of FRUZAQLA, including strong growth outside China (notably in Japan and anticipation of further global rollouts), position the company to capture rising healthcare spending and broader reimbursement coverage, supporting robust top-line growth.
See why 6 investors see HUTCHMED (China) as 38% undervalued.
Result: Fair Value of £3.46 (UNDERVALUED)
Still, the HUTCHMED (China) story can unravel quickly if competition in key oncology markets tightens, or if regulatory decisions delay or constrain product uptake.
Find out about the key risks to this HUTCHMED (China) narrative.
Another View: What HUTCHMED (China)'s P/E Ratio Is Telling You
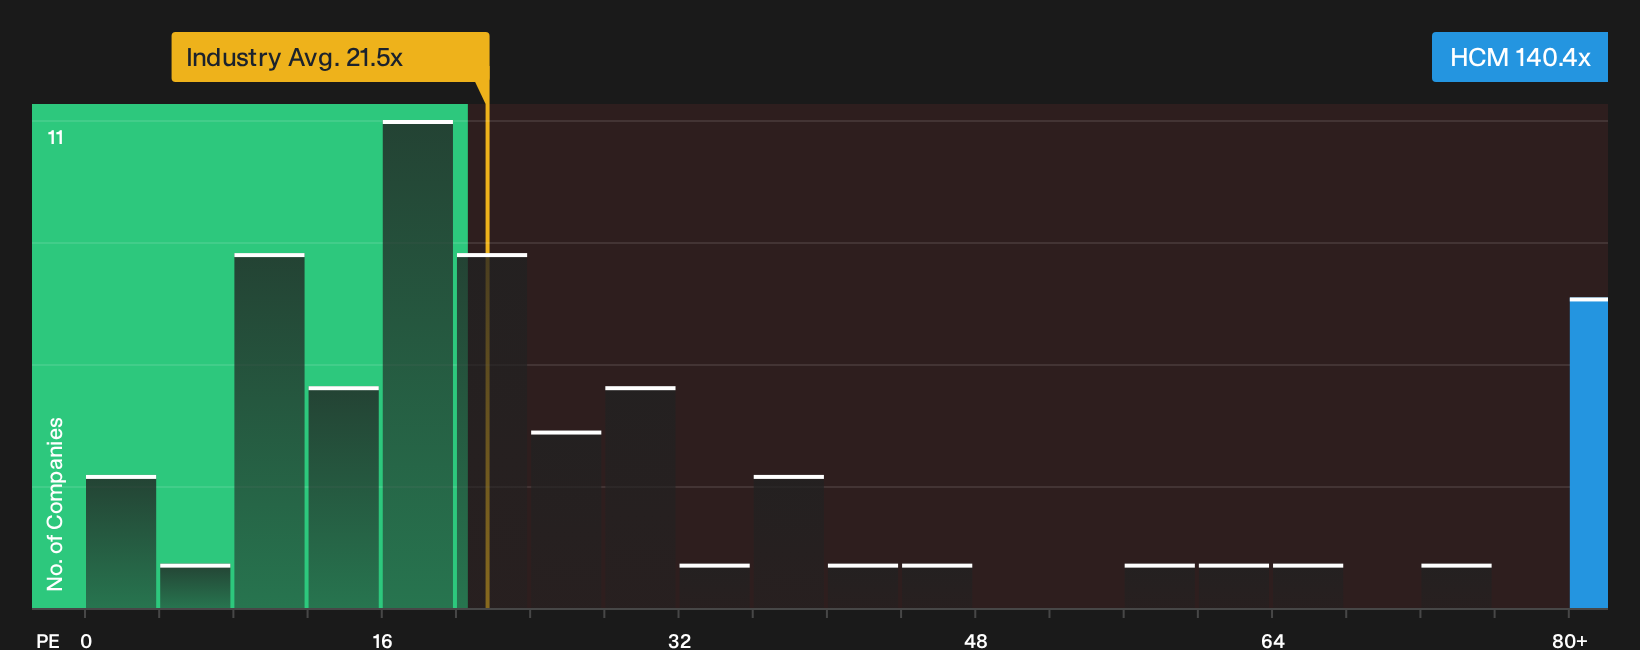
There is a very different message coming from the earnings multiple. HUTCHMED (China) trades on a P/E of 140.4x, while the European pharmaceuticals group sits near 21.3x and the peer average is 19.5x. The fair ratio is 29.1x, which is the level the market could move towards over time.
That gap signals that a lot of optimism is already built into the current price, even with other models flagging undervaluation. If sentiment shifts back toward the fair ratio, the valuation reset could be sharp. The key question for investors is which view deserves more weight right now: the rich P/E or the discounted fair value narrative.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Conflicted by HUTCHMED (China)'s upbeat deal news and mixed track record? Act quickly and test the data yourself, then weigh up the 2 key rewards and 2 important warning signs.
Looking for more HUTCHMED (China) sized opportunities?
If HUTCHMED (China) has sharpened your focus, do not stop here. Broaden your watchlist using targeted stock ideas built from the Simply Wall Street Screener.
- Target potential mispricings by scanning a 8 high quality undervalued stocks that filters for quality businesses trading below their fundamentals.
- Stack your income stream by reviewing a 5 dividend fortresses focused on companies offering higher yields and durable payout records.
- Dial down portfolio stress by checking a 4 resilient stocks with low risk scores that highlights businesses with sturdier balance sheets and more resilient risk profiles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com