
MP Materials (MP) Magnet Push Puts Valuation Back In Focus
Why MP Materials Is Back in Focus
MP Materials (MP) has moved back into the spotlight after committing around $1.2b to a Texas magnet facility and preparing to ship rare earth magnets to General Motors and Apple.
Recent announcements about MP Materials' Texas build out and upcoming magnet shipments have arrived against a weak tape, with the stock down 21.66% on a 30 day share price return and 30.33% year to date. At the same time, the 3 year total shareholder return of 132.12% still reflects substantial earlier gains, suggesting long term momentum has cooled even as interest in the rare earths story picks up again.
Spot potential peers to MP Materials by scanning a hand picked group of rare earth and related producers in our 32 best rare earth metal stocks.MP Materials is being pulled in two directions, a rare earth pure play pouring more than US$1.2b into magnets while the share price retreats hard. Do recent numbers and contracts justify the current valuation or the discount?
Most Popular Narrative: 46% Undervalued
MP Materials' most followed valuation narrative pegs fair value at about $70.76 per share, well above the recent $38.30 close. This view places significant emphasis on future execution at Mountain Pass and the Texas magnet build out.
Structural global shifts prioritizing domestic and allied supply chains for critical materials, underpinned by national security and electrification policies, have resulted in massive government funding, ownership stakes, and market protections for MP, setting up long-term demand and premium pricing for U.S.-produced rare earths and supporting sustained margin expansion.
See why 206 investors see MP Materials as 46% undervalued.
Result: Fair Value of $70.76 (UNDERVALUED)
Still, the upbeat MP Materials story runs into real friction if big projects run over budget or if heavy reliance on Apple, GM and the Pentagon tightens future flexibility.
Find out about the key risks to this MP Materials narrative.
Another View: MP Materials Looks Expensive On Sales
MP Materials screens as deeply undervalued on the SWS DCF model, with the $38.30 share price sitting well below an estimated future cash flow value of $188.44. That intuition gets tested when you look at plain P/S, though.
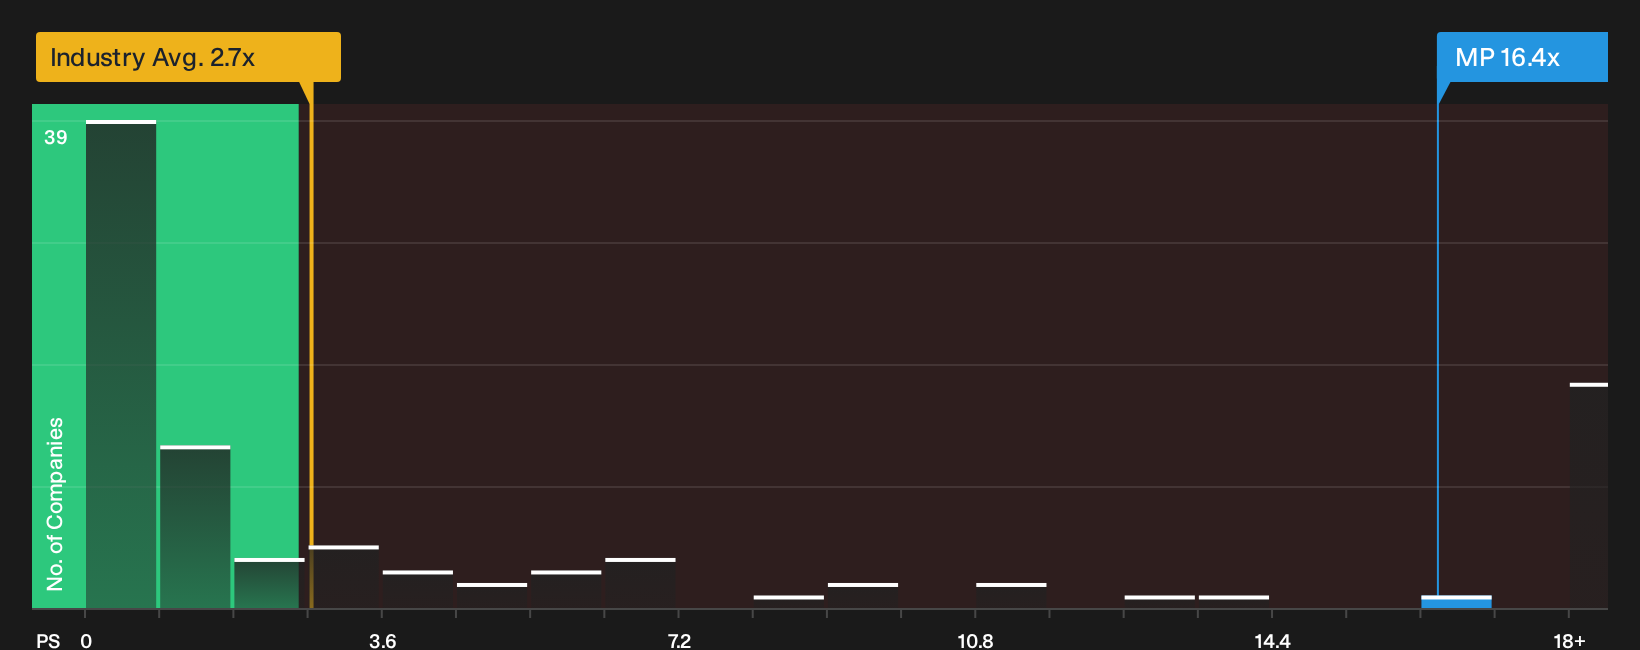
On revenue, the stock trades at a P/S of 16.4x. Peer companies average 11.9x, and the fair ratio estimate sits near 6.1x. That gap suggests investors are paying a heavy premium for MP Materials' story. Is that extra multiple really worth it if execution or contracts disappoint?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed messages on MP Materials so far, or a clear setup hiding in plain sight. Act while the data is fresh in your mind and stress test the bullish angles for yourself by starting with the 2 key rewards.
Looking for more investment ideas beyond MP Materials?
If MP Materials has sharpened your focus, do not stop here. Fresh ideas often come from scanning outside your comfort zone, before everyone else notices.
- Target sharper value opportunities by reviewing the 27 high quality undervalued stocks that combine quality fundamentals with potentially mismatched pricing.
- Build a sturdier core to your portfolio by checking the list of solid balance sheet and fundamentals (25 results) that highlight financially resilient businesses.
- Spot lesser known prospects early by scanning the 21 high quality undiscovered gems before market attention crowds the trade.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com