
Campbell's (CPB) Stock Could Be A Bargain On Current Earnings
Campbell's has seen its share price slide in recent years, which puts fresh attention on a basic question. Is the current market value supported by the earnings the business is generating today and is expected to produce over time?
- Over the past 3 years the stock has fallen 41.1%, which puts more weight on whether the earnings profile can justify where the shares now trade.
- The business still rests on a mature packaged food portfolio, so future return on invested capital and the stability of margins may matter more for valuation than rapid revenue expansion.
- Your read on Campbell's is one view; the desks covering it have another. See what analysts think Campbell's's shares could be worth.
For investors, the debate is whether Campbell's current earnings power and its prospects for profit growth are enough to make today's share price look sensible.
If you are weighing whether Campbell's earnings justify its current US$20.73 share price, it can help to compare that same question across 27 high quality undervalued stocks.
Does Campbell's Look Undervalued on Earnings?
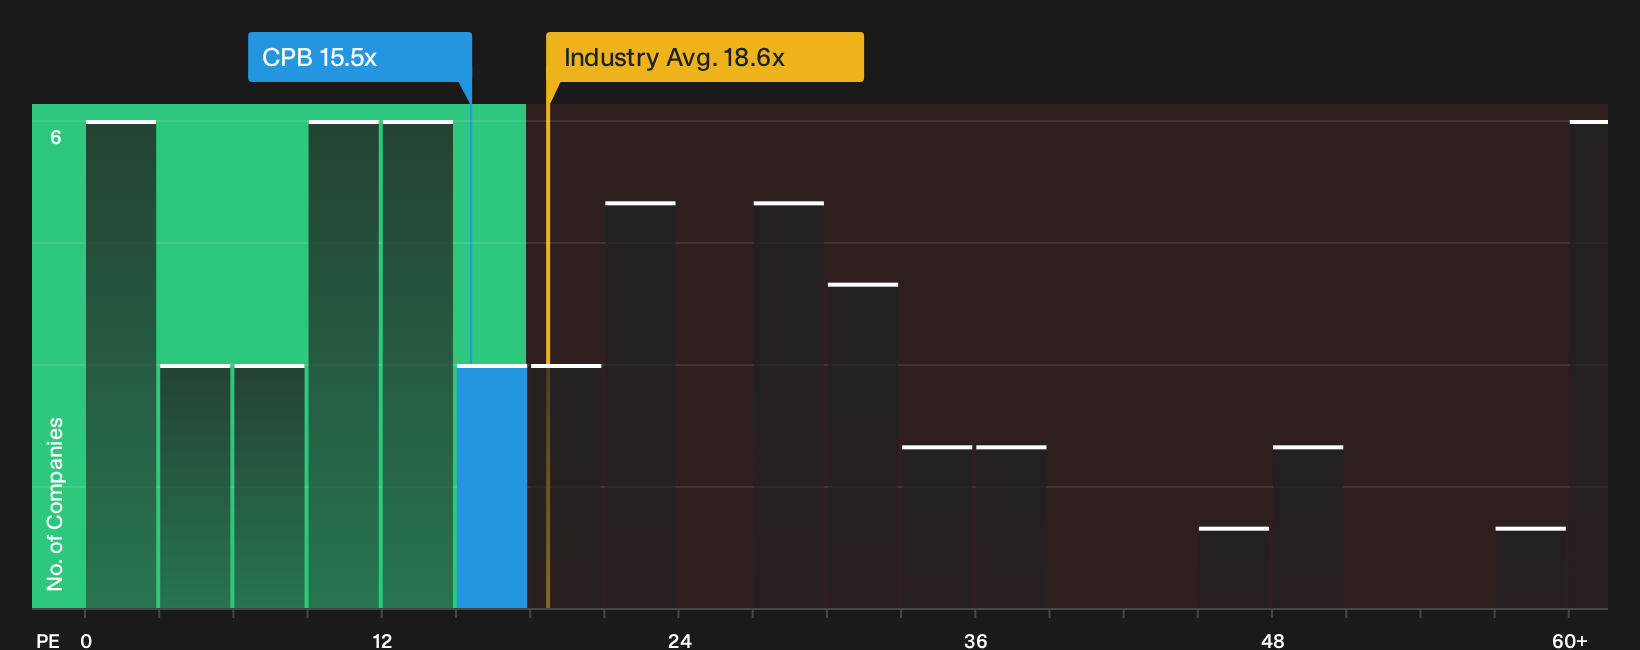
The P/E ratio fits Campbell's because earnings are still the main yardstick investors use for a branded packaged food group. At around 15.5x earnings, Campbell's trades below the broader Food industry average P/E of about 18.6x, which points to a discount against the typical valuation for the sector.
Against closer peers, the picture shifts a bit. The stock sits above the peer cluster average of roughly 13.5x, so Campbell's does not come across as the cheapest option inside its narrower comparison set. The modelled fair P/E for the company, which blends its growth outlook, profitability profile, risk factors and size, sits higher than the current multiple, so the shares screen as undervalued on this framework. Explore the numbers behind Campbell's's P/E valuation.
The Campbell's Narrative: What Would Justify Today's Price?
Simply Wall St Narratives link Campbell's current P/E puzzle to specific future paths for growth, margins and earnings, and set out what would need to happen in each case for the stock to be worth materially more or less than today based on those assumptions. Each scenario connects a fair value estimate to a clear storyline about Campbell's possible catalysts and risks so you can track over time which version of events is actually unfolding in the real world.
Community views on Campbell's are split between those who see cost cuts and brand investment as enough, and those who think category and balance sheet pressures still dominate.
Bull case: roughly fairly valued
"Ongoing execution of the expanded US$500 million enterprise wide savings program through fiscal 2030, built on prior PEAK savings and now targeting procurement across every P&L line, headcount reductions and further network optimisation after recent plant closures, is intended to lift productivity and operating efficiency..."
Discover why this Narrative puts Campbell's at roughly fairly valued.
Bear case: 30% overvalued
"Management plans for Snacks organic sales to decline at a high single digit rate in Q1 FY27 and does not expect Snacks consumption to turn positive in FY27, even after plant closures, assortment tightening and a heavier focus on brands like Goldfish and Snyder’s..."
Explore why this Narrative puts Campbell's at 30% overvalued.
Campbell's valuation still leaves one big question hanging
Price multiples tell you what the market pays for Campbell's earnings today, but broker models sketch where profits could land a few years from now and how that lines up with this share price. Explore where analysts expect Campbell's to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com