
3 Stocks Where AI Content Licensing Could Change The Investment Case
AI is quietly rewriting the rulebook for who gets paid for information and how. As search-driven traffic gets squeezed and new licensing deals emerge for machine-ready content, some businesses gain fresh ways to monetize what they already produce while others face pressure on old models. This article walks through three stocks exposed to that AI content shift and explains why the ripple effects could be relevant for portfolio decisions today.
The stocks covered below are only a sample set, and the full screen surfaced 24 more AI content infrastructure and licensing platforms with equally compelling narratives that are not discussed in this article.
To identify and analyze the highest conviction opportunities in this theme, head straight into the AI Content Infrastructure and Licensing Platforms screener
OVERLAP HoldingsInc (TSE:414A)
Overview: OVERLAP HoldingsInc creates, manages, and licenses entertainment IP libraries across manga, light novels, comics, and animation, well suited to AI content licensing workflows.
Operations: OVERLAP HoldingsInc generates ¥8,522 million from its Entertainment Business segment, with all reported revenue currently coming from Japan.
Market Cap: ¥16.1 billion
OVERLAP HoldingsInc owns structured manga and novel libraries that fit cleanly into AI content licensing models, where clear rights and metadata matter. The business focuses on monetizing IP across formats, so new machine readable licensing channels could influence what each story is worth, depending on how one unseen pressure plays out.
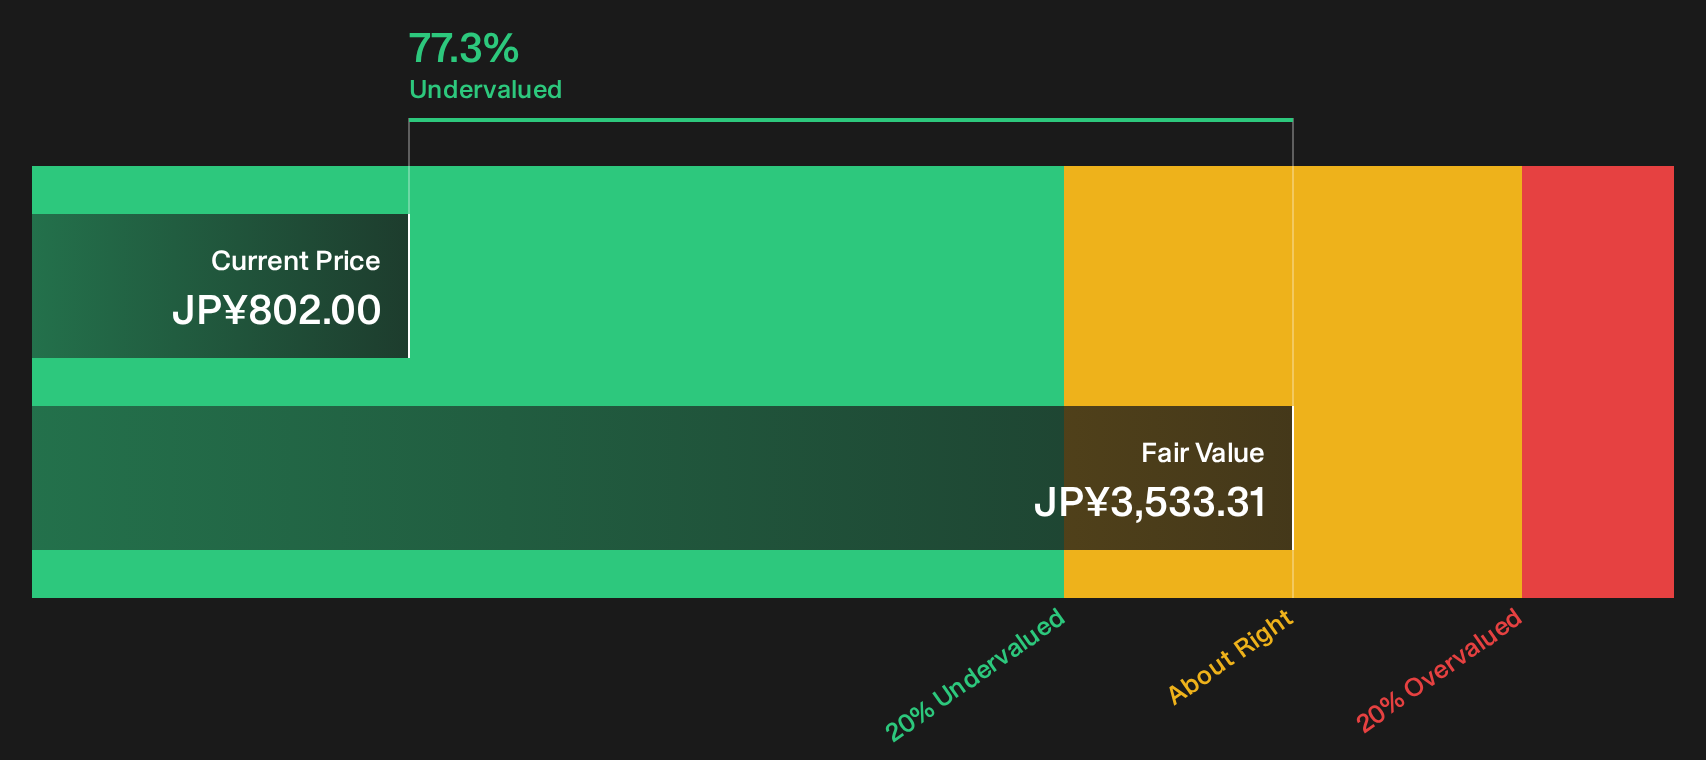
That pressure point is already shaping how each title is valued, so review the DCF valuation analysis for OVERLAP HoldingsInc to see where AI licensing economics could start to bite or surprise.
Docebo (TSX:DCBO)
Overview: Docebo provides a cloud learning platform that lets organizations create, manage, and monetize structured training content for employees, customers, and partners.
Operations: Docebo generates about $258.9 million from educational software, with roughly $174 million from the United States, $71.4 million from the rest of the world, and $13.5 million from Canada.
Market Cap: CA$1.1 billion
Docebo matters for this AI content infrastructure theme because its learning suite handles structured, rights-aware training data that enterprises already treat as mission critical. This puts the platform close to where verified content and internal AI tools increasingly meet.
"Growing adoption of Docebo’s AI driven modules that rely on proprietary learning, skills and compliance data can deepen customer usage and support higher subscription revenue and gross margin as more workflows are automated and embedded in client operations."
What happens to those margins if one quiet shift in how large enterprises price and bundle AI-heavy training contracts breaks the recent pattern?
If that pricing shift is what matters most, read the full narrative for Docebo to see how AI driven contracts could be accelerating or masking Docebo’s next chapter.

Vobile Group (SEHK:3738)
Overview: Vobile Group runs platforms that protect and track digital media, helping rights holders manage, license, and monetize content used in AI workflows.
Operations: Vobile Group generates HK$3,221 million from Offering Services, with roughly HK$1,516 million from the United States and HK$1,573 million from Chinese Mainland.
Market Cap: HK$6.4 billion
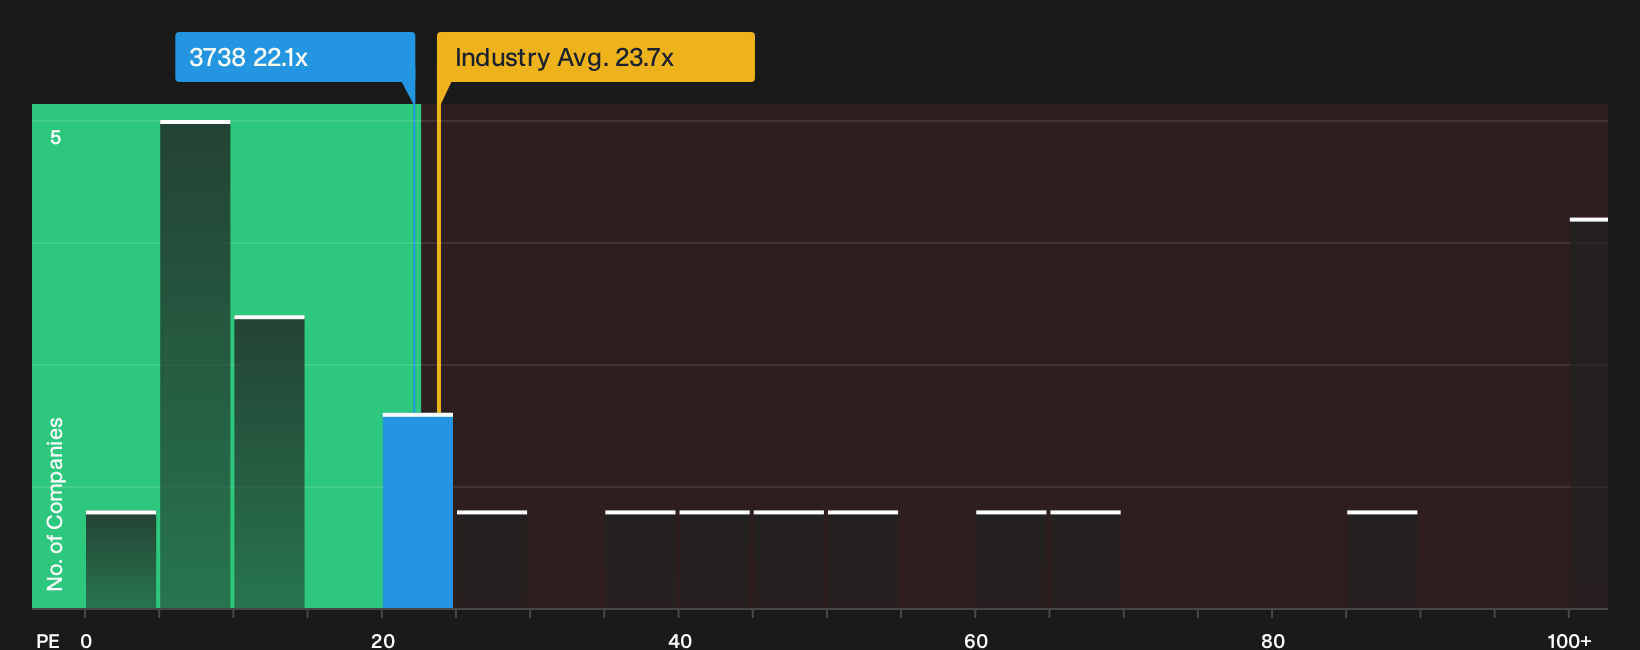
Vobile Group sits at the intersection of AI-focused platforms and copyright owners, providing content protection, RightsID management, and Web3 enabled monetization for media used in training and inference. Its earnings, revenue, and a P/E below the broader software sector indicate that investors are currently paying less for each dollar of AI related rights infrastructure, which may be relevant if an emerging pricing shift in digital content licensing fully takes hold.
If that licensing repricing is the real hinge, begin with the DCF valuation analysis for Vobile Group to assess where AI infrastructure expectations might already be decoupling from the share price.
Curious About What You Might Be Missing?
Fresh ideas do not wait. Breakout stories gain momentum, quiet compounders get caught, and laggards keep dropping while it matters. Scan these under the radar lists and get in early.
- Target steadier compounding by reviewing a curated list of solid balance sheet and fundamentals (23 results) that can help you focus on businesses where financial resilience does more of the heavy lifting.
- Chase upside in structural trends by scanning 72 high quality undiscovered gems that remain under the radar for now but could attract far more attention if sentiment shifts.
- Lock in cash flow focus by checking a hand picked 29 dividend fortresses where income potential and balance sheet strength work together instead of fighting for your attention.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com