
Is Credit Acceptance (CACC) Fully Priced Following Its October 29 Earnings Setup?
Credit Acceptance (CACC) has scheduled its third quarter earnings release for October 29, 2026, after the market close, with a webcast discussion planned that afternoon for investors and analysts.
At a share price of US$545.04, Credit Acceptance has given investors a year-to-date share price return of 20.07%. The 1-year total shareholder return of 7.60% trails the stronger 3-year total shareholder return of 34.71%, which points to momentum that has cooled in recent months as the stock has declined 5.06% over 90 days ahead of the upcoming earnings release.
Scan how Credit Acceptance compares with other US financials showing resilient performance in 2026 by reviewing our curated list of 30 resilient stocks with low risk scores.
After a 5.06% pullback over 90 days, yet with a price still close to analyst targets, the key issue for Credit Acceptance is simple: Do current estimates suggest meaningful upside, or has fair value already been reached?
Most Popular Narrative: 9% Undervalued
Credit Acceptance last closed at $545.04, compared with a widely followed fair value narrative of about $596.67. This frames the upcoming earnings call around whether the lending model and funding access can support that higher valuation over time.
Recent moves to embed AI across pricing, underwriting, servicing, collections and sales workflows, including a roughly 5x quarter on quarter increase in AI call center volumes and new AI driven dealer tools, create room for better credit decisions and operating efficiency that can support net margins and earnings.
See why 4 investors see Credit Acceptance as 9% undervalued.
Result: Fair Value of $596.67 (UNDERVALUED)
Still, the multistate settlement with US$694 million of combined payments and canceled debt, along with ongoing litigation and reputational pressure, could limit how much that 9% undervaluation thesis can play out.
Find out about the key risks to this Credit Acceptance narrative.
Another View: Cash Flows Paint A Different Picture
The first narrative around Credit Acceptance leans on earnings and analyst targets that frame the stock as roughly 9% undervalued. A second lens tells a very different story. The SWS DCF model puts fair value at about $347.91, well below the current $545.04 share price.
That gap means investors are paying far more for Credit Acceptance than this cash flow view supports. This raises a practical question for anyone holding the stock: Is the market correctly pricing long term resilience, or are expectations running ahead of what future cash flows can justify?
Look into how the SWS DCF model arrives at its fair value.
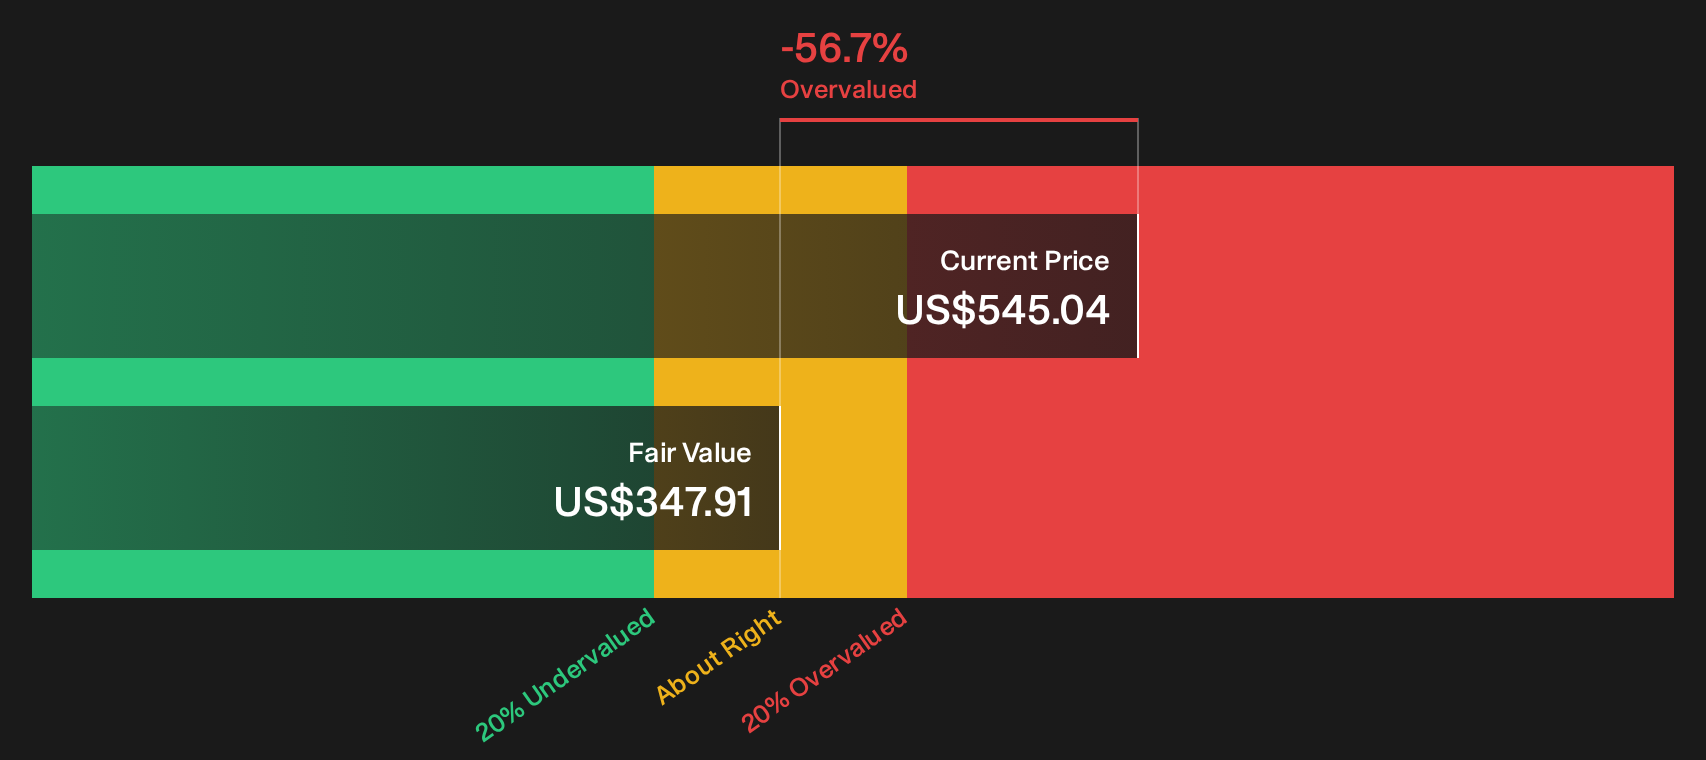
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Credit Acceptance for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 27 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals around Credit Acceptance do not need to leave you on the sidelines. Take a quick look at the same data, weigh the trade off between risks and rewards, and ground your own view with the 3 key rewards and 1 important warning sign.
Looking for more ideas beyond Credit Acceptance?
If Credit Acceptance has you thinking harder about opportunity and risk, do not stop here. Use the screener to pressure test fresh ideas for your watchlist.
- Target potential mispricings by scanning a curated set of 27 high quality undervalued stocks that pair quality fundamentals with prices that lag underlying metrics.
- Build a steadier income stream by reviewing a focused group of 5 dividend fortresses with yields that may complement more growth oriented holdings.
- Strengthen your downside protection by zeroing in on a list of solid balance sheet and fundamentals (25 results) that can help anchor a more durable portfolio.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com