
Corpay (CPAY) Could Be 11% Below Fair Value After Newcastle United Deal
Corpay (CPAY) just signed a multi-year agreement for its Cross-Border unit to serve as Newcastle United’s Official Foreign Exchange Partner, putting its FX risk tools and global payments platform in front of a globally followed football club.
Corpay’s latest Newcastle United agreement lands while the stock trades at US$408.46 and has posted a 90 day share price return of 10.22%, with year to date share price gains of 35.89% and a 1 year total shareholder return of 43.63%, signalling firm momentum rather than a short lived bounce.
Scan how Corpay’s Newcastle United deal fits into a wider payments theme by reviewing 21 high quality undiscovered gems that are already executing on cross-border and transaction-led growth stories.
Corpay’s strong run and fresh Newcastle United exposure put you at a crossroads. Is it worth paying up at US$408.46, or does it make more sense to wait for a cheaper shot at the same cash flows?
Most Popular Narrative: 11% Undervalued
At $408.46, Corpay screens below the most followed fair value estimate of $461. This estimate anchors on long term cash generation and capital deployment rather than short term sponsorship noise.
The main requirement for this approach is continued execution on portfolio simplification and capital deployment, including divesting non-core Vehicle Payments assets while using roughly $15b of available capital for buybacks and targeted corporate payments deals.
The current numbers, including raised 2026 cash EPS guidance to $27.35 and plans to use divestiture proceeds for repurchases, suggest a share price that does not fully reflect this cash generation and buyback capacity.
See why 14 investors see Corpay as 11% undervalued.
Result: Fair Value of $461 (UNDERVALUED)
Still, the Corpay story can break if the proposed US$100m U.S. Vehicle Payments settlement reshapes pricing, or if organic transaction growth falls short of analyst forecasts.
Find out about the key risks to this Corpay narrative.
Another View: Corpay Through The P/E Lens
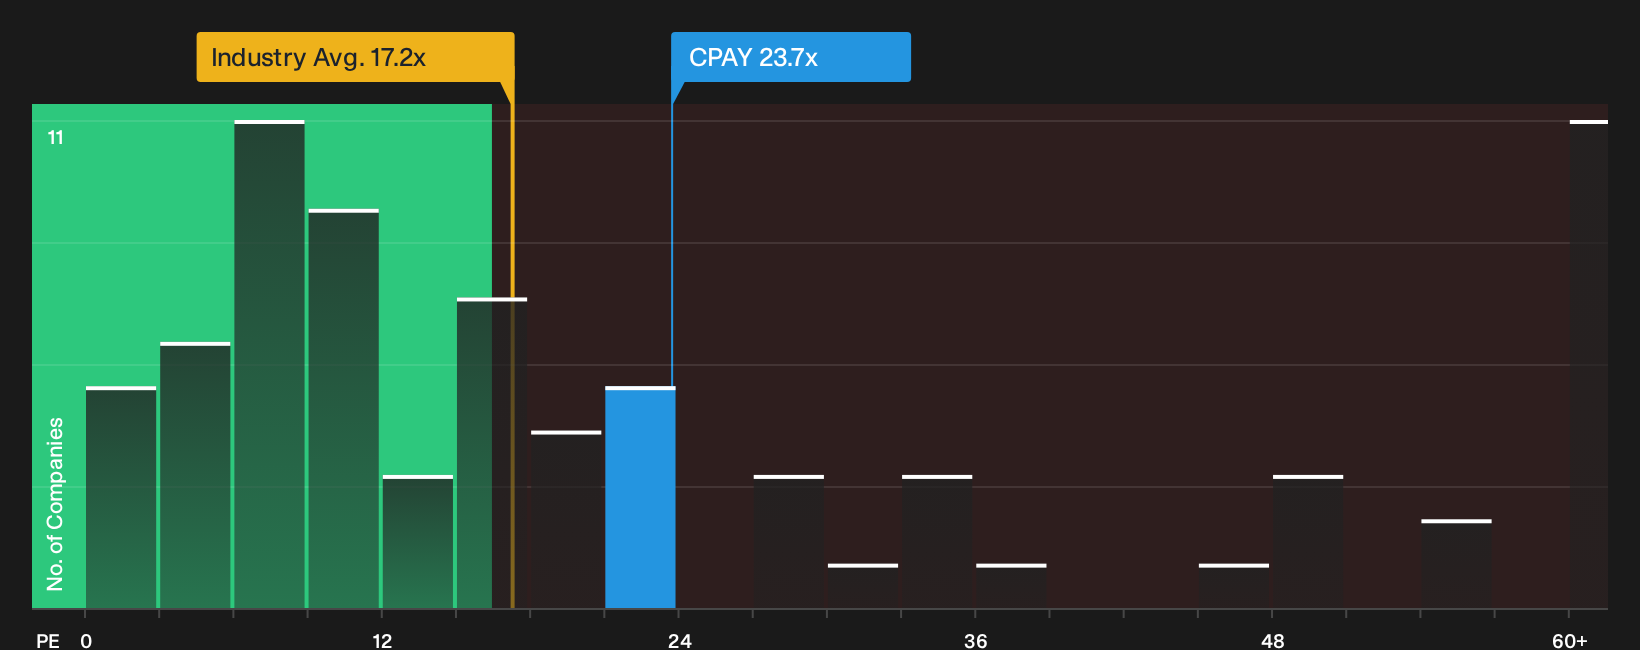
The cash flow story presents Corpay as undervalued, yet the earnings multiple tells a tougher story. At a P/E of 23.7x, the stock trades well above the US Diversified Financial industry on 17.7x, the peer group on 18x, and its own fair ratio of 16.9x.
That gap means you are paying a premium price for each dollar of current earnings, even though the SWS DCF model and analyst fair value indicate potential upside. The question is simple: Are you comfortable paying above 20x earnings for a business that appears inexpensive on cash flows but looks expensive on multiples, or do you wait for the P/E to move closer to the fair ratio?
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
The mix of cash flow optimism and a richer P/E leaves the Corpay story finely balanced, so move quickly and weigh the full picture of 3 key rewards and 2 important warning signs.
Looking for more investment ideas beyond Corpay?
If Corpay has sharpened your thinking, do not stop here. You can also consider a wider opportunity set across other companies with different risk, return, and income profiles.
- Target fresh upside by scanning a curated set of growth stories that still look mispriced through the 27 high quality undervalued stocks.
- Build a steadier income stream by reviewing companies in the 5 dividend fortresses that aim to combine yield with resilient payout histories.
- Dial down portfolio stress by focusing on businesses screened for resilience and balance sheet strength inside the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com