
Does Higher Margin Push Change The Bull Case For UPS Stock?
- United Parcel Service has shifted away from lower-yield Amazon volumes, raised per package pricing, and updated profit targets while highlighting cost savings, automation and growth in higher-margin small and medium business, B2B and healthcare logistics.
- This pivot reduces reliance on high-volume, lower-quality parcels and leans on healthcare and automated facilities, which could reshape UPS's earnings mix and capital returns profile.
- We will now look at how United Parcel Service's investment narrative evolves as it leans harder into higher margin healthcare shipments.
Compare United Parcel Service's pivot toward higher quality parcels with a curated group of logistics and capital-efficient businesses in the 30 resilient stocks with low risk scores.
United Parcel Service Investment Narrative Recap
To stay on board with United Parcel Service, you need to believe the shift to higher yielding parcels, more automation and a larger healthcare footprint can offset stagnating sales and shrinking returns on capital. Recent news around weaker earnings per share and flat revenue keeps the spotlight on whether this mix change can genuinely lift profitability.
The near term catalyst is execution on cost savings and network consolidation, including building closures and higher use of automated facilities. The biggest current risk is that lower parcel volumes, labor pressure and a high dividend payout limit flexibility, so the efficiency program fails to translate into better margins and healthier cash generation.
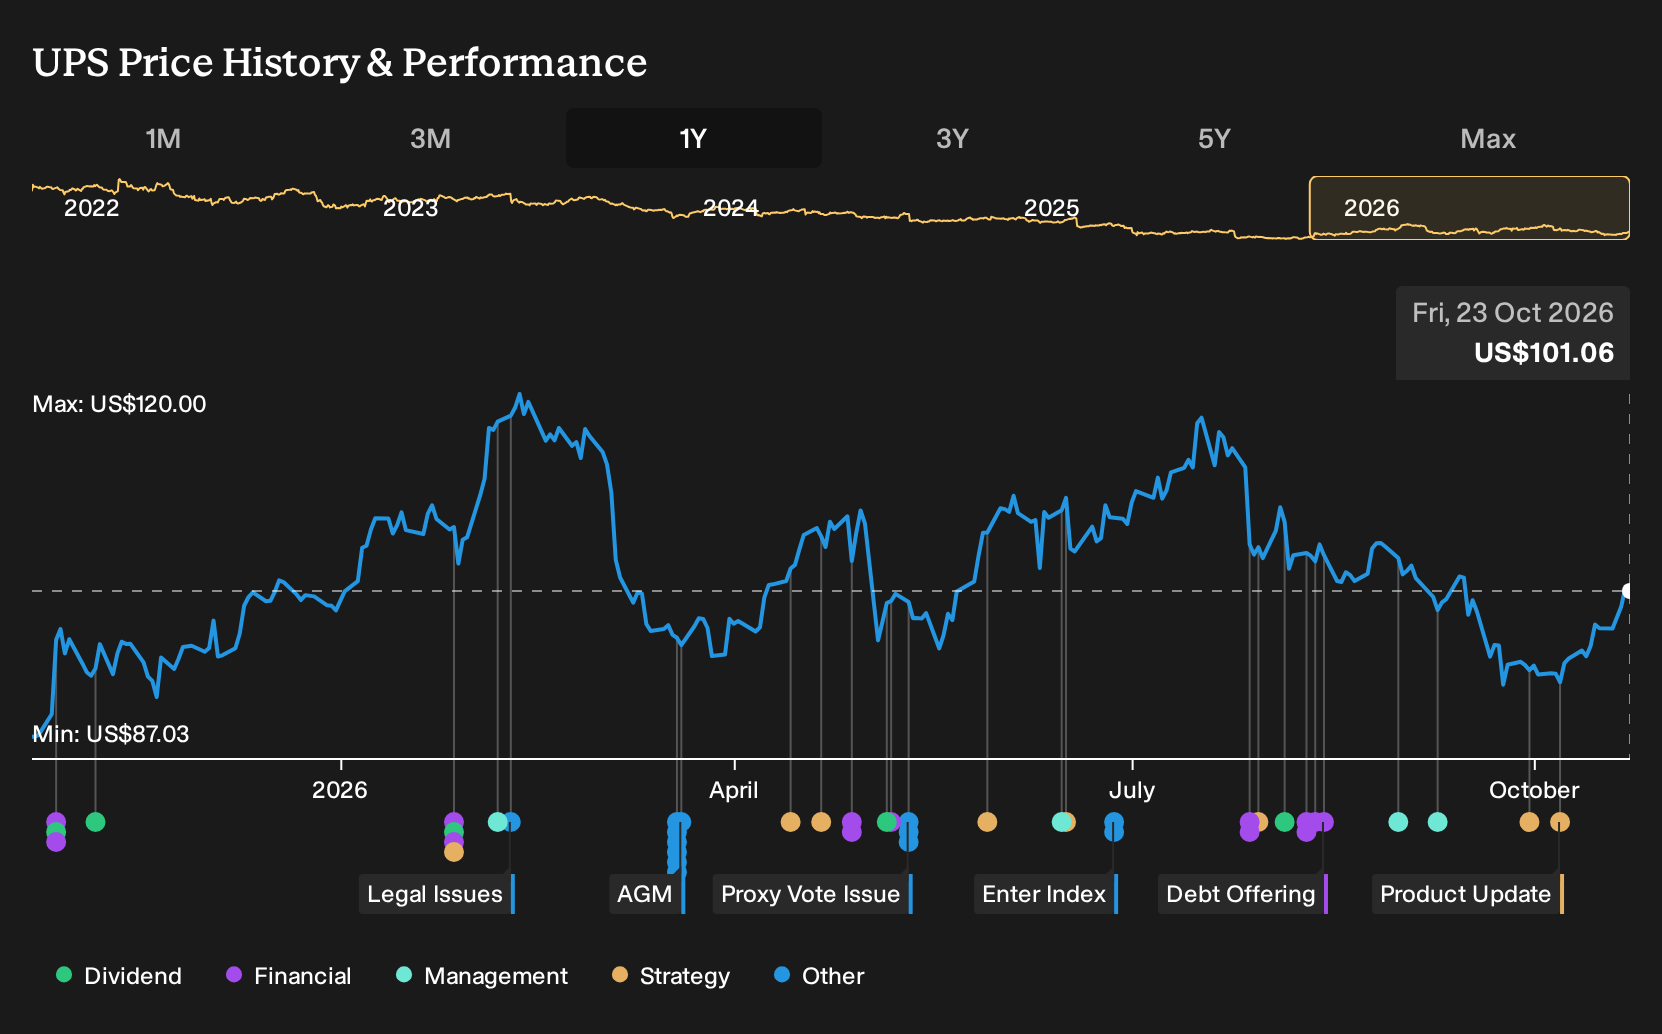
The most relevant recent update is management’s decision to raise prices per package while handling fewer U.S. deliveries and updating its full year adjusted operating profit target. This move ties directly to the pivot away from lower quality Amazon parcels and toward small and medium business, B2B and healthcare shipments that carry higher yields.
For you as an investor, the key question is whether this pricing and mix shift can offset competitive pressure and the drag from past earnings declines. If the automated network, RFID rollout and healthcare and cold chain expansion support steadier revenue per piece without service disruptions, those operating gains would directly influence how the current risks around debt and the dividend are perceived.
United Parcel Service's narrative projects US$99.4b revenue and US$7.2b earnings by 2029. This assumes 3.4% yearly revenue growth and an earnings increase of about US$2.6b from the US$4.6b of earnings today.
Uncover how United Parcel Service's fair value indicates a 15% potential upside to its current price, which could narrow quickly if sentiment around UPS improves.
Exploring Other Perspectives
Some of the most optimistic analysts focus on healthcare as the big swing factor for United Parcel Service. They were penciling in US$105.5b of revenue and US$8.6b of earnings by 2029 before this latest pricing and mix update. That is far above the US$99.4b and US$7.2b consensus view, so you can see how opinions can spread out. Treat this news as a fresh data point and explore both the baseline and bullish narratives before deciding which story you find more convincing.
Explore 8 other United Parcel Service fair value estimates, including one that suggests the potential for as much as 63% upside from the current price!
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own judgment.
- A great starting point for your United Parcel Service research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for United Parcel Service. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate United Parcel Service's overall financial health at a glance.
Looking for more investment ideas beyond United Parcel Service?
Once you have formed a view on United Parcel Service, it can be useful to compare that thesis with other businesses that share similar qualities or offer very different risk and return profiles. The Simply Wall St Screener is built for exactly that, helping you quickly narrow thousands of listings down to a focused watchlist that fits your approach.
- If you care most about stability, start with a 30 resilient stocks with low risk scores that screens for resilient businesses with stronger risk profiles than the broader market.
- If valuation discipline is your anchor, filter for attractively priced opportunities using a 27 high quality undervalued stocks that blends quality fundamentals with discounted pricing.
- If you want to spot early stage opportunities with room to mature, consider a 21 high quality undiscovered gems that highlights underfollowed companies with solid underlying metrics.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com