
Will Earnings Miss Change Delta Air Lines (DAL) Narrative
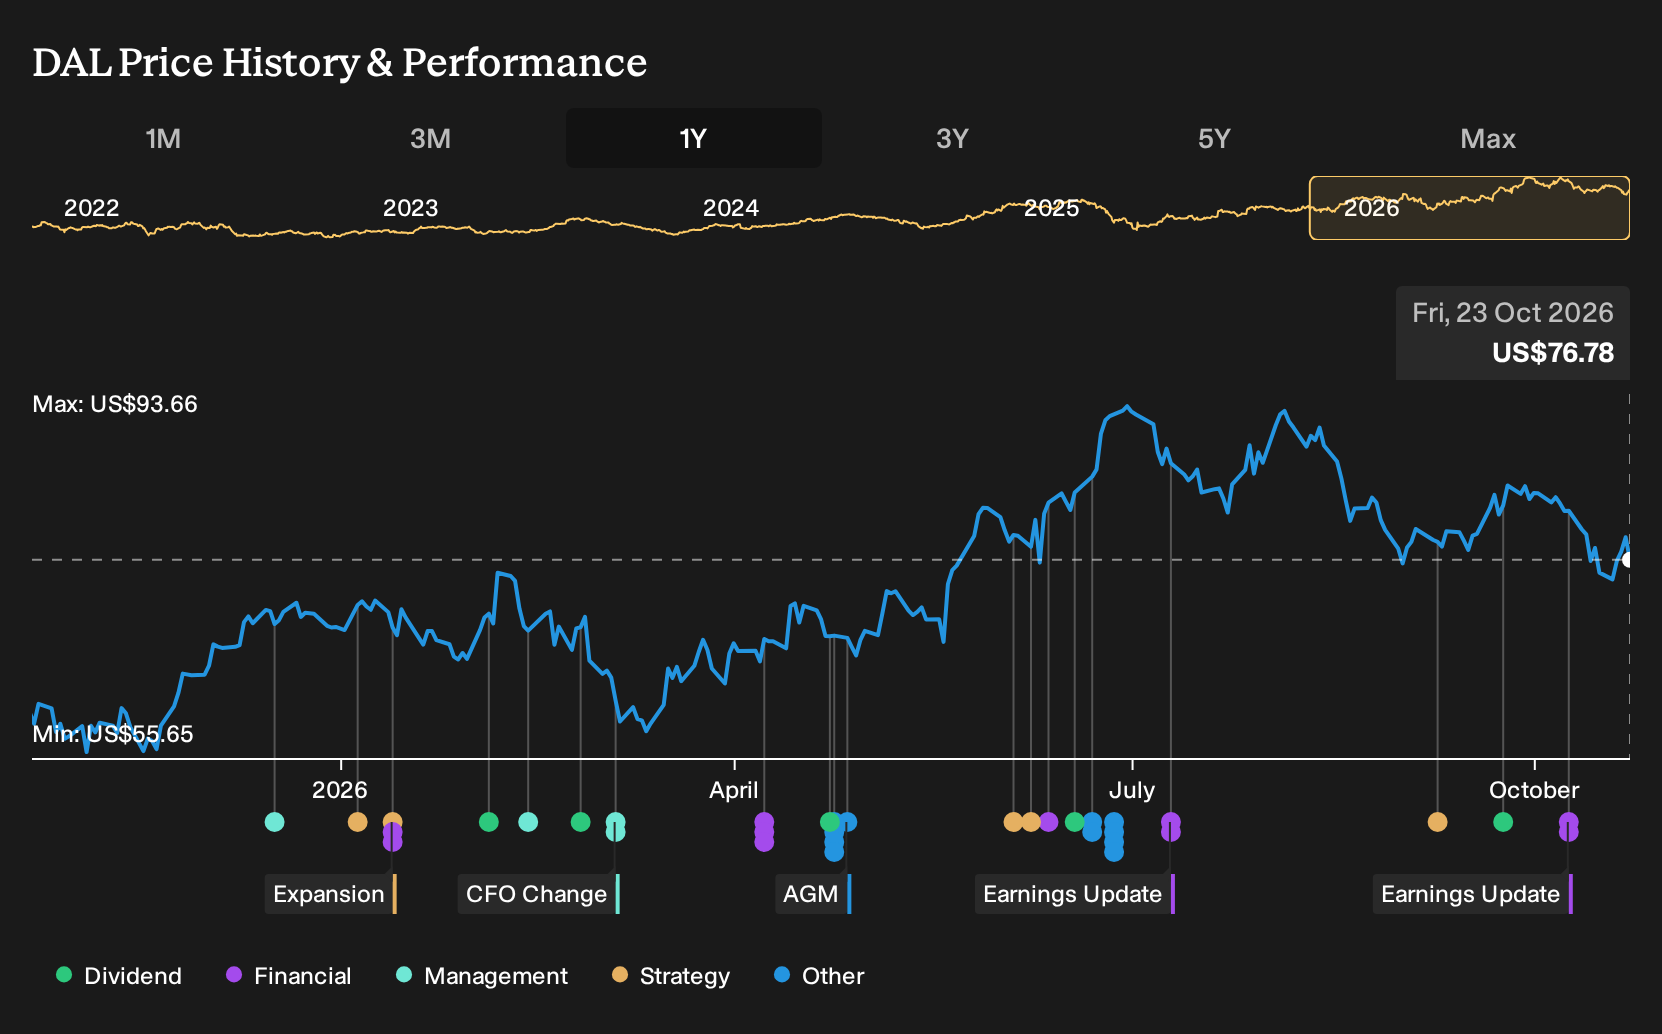
- Delta Air Lines reported third quarter 2026 earnings that missed consensus expectations, with adjusted revenue of US$17.59b supported by strong travel demand and healthy yields, while higher fuel and non fuel expenses pressured profitability.
- The airline continued to expand premium and diversified revenue streams, which helped support overall sales performance even as cost pressures weighed on earnings delivery.
- We will look at how Delta Air Lines' investment narrative intersects with higher fuel costs and expense pressure after its earnings miss.
Scan how other carriers are handling fuel and cost pressures by reviewing our curated list of list of solid balance sheet and fundamentals (25 results) alongside Delta Air Lines' latest quarter.
Delta Air Lines Investment Narrative Recap
For Delta Air Lines, the core belief is that premium, loyalty and diversified services can carry more of the load when fuel and other operating costs feel tight. The third quarter 2026 miss did not change that basic story, although it did spotlight how quickly earnings can come under pressure when fuel stays expensive and non fuel expenses rise together.
In the near term, the key swing factor is whether Delta can keep premium and international demand healthy enough to support unit revenue while holding capacity roughly flat. The biggest risk is a combination of persistently high fuel costs and any softening in domestic main cabin demand, which would squeeze margins that are already below last year.
Recent commentary around the refinery benefit illustrates why this asset matters alongside the latest quarter. Management still expects more than US$700 million of refinery benefit in 2026, with a larger per gallon contribution in the December period. This is directly relevant when fuel is a clear headwind to earnings delivery.
For catalysts, that refinery support works together with the growing mix of premium, loyalty, cargo and MRO revenue, which already accounts for 61% of total sales. If Delta executes on its 10 year TechOps maintenance agreement with UPS and the targeted expansion of third party MRO revenue, that non ticket income could become even more important to offset fuel and cost volatility.
Delta Air Lines' current analyst framework points to US$80.8b in revenue and US$3.4b in earnings by 2029, based on projected revenue growth of 4.0% per year and an increase in earnings of about US$0.1b from US$3.3b today.
Uncover why Delta Air Lines' fair value indicates a 32% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You also have a very different storyline on Delta Air Lines from the most bearish analysts. They focus on the risk that higher fuel and nonfuel costs persist, with revenue falling toward about US$69.1b and earnings around US$3.1b by 2029. Those views were set before this earnings miss, so opinions may shift.
Explore 7 other Delta Air Lines fair value estimates, including one that suggests as much as 18% downside from the current price.
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Delta Air Lines research is our analysis highlighting 3 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Delta Air Lines. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Delta Air Lines' overall financial health at a glance.
Looking For More Ideas Beyond Delta Air Lines?
Once you have a view on Delta Air Lines, it can help to line that opinion up against other opportunities that share similar financial qualities or offer a different balance of risk and potential reward.
- If capital protection matters most, scan a focused group of companies with relatively resilient profiles through our 30 resilient stocks with low risk scores.
- For investors hunting for quality at a reasonable price, cast a wider net across our 27 high quality undervalued stocks that combine solid fundamentals with compressed expectations.
- When you want sturdier foundations alongside Delta Air Lines in your portfolio, filter for companies with stronger balance sheets and sound financial footing using our list of solid balance sheet and fundamentals (25 results).
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com