
How Raised Guidance At Thermo Fisher Scientific Stock Has Changed Its Investment Story
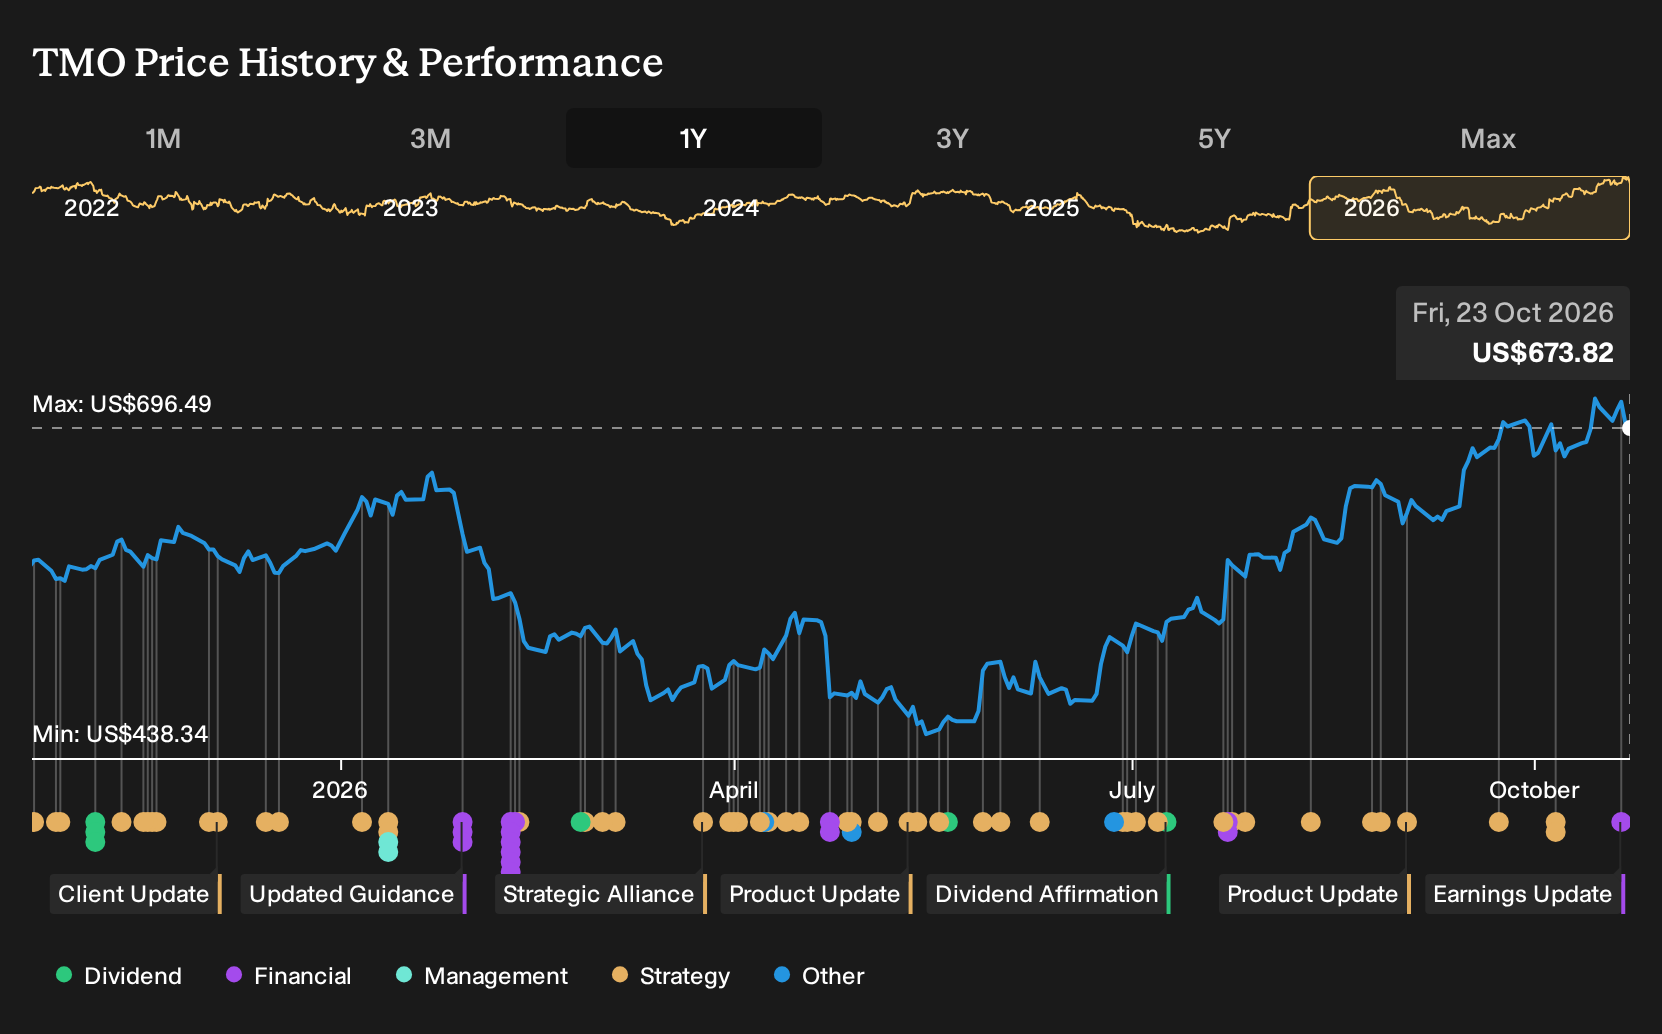
- Thermo Fisher Scientific reported Q3 2026 sales of US$12.137b and net income of US$1.721b, with earnings per share from continuing operations modestly higher than a year earlier.
- The business coupled these results with raised full year guidance and broad based strength in pharma services and lab products after prior end market disruption.
- Next, the focus will be on how Thermo Fisher Scientific's raised full year guidance reshapes the broader investment narrative around the company.
See how Thermo Fisher Scientific’s guidance upgrade fits into the broader life sciences recovery by comparing it with peers in our hand picked list of 34 healthcare AI stocks.
Thermo Fisher Scientific Investment Narrative Recap
To own Thermo Fisher Scientific, you need to believe that pharma, biotech and high end lab demand will continue to support its broad tools and services platform, while management keeps fine tuning the portfolio. The latest quarter, with higher sales, earnings and raised guidance, reinforces that core idea and suggests near term operating momentum is intact.
The key near term swing factor is whether pharma services and lab products stay strong enough to offset still muted academic and government budgets. The biggest risk remains that funding recovery at those customers stays soft, which could limit appetite for premium instruments, even as Thermo Fisher Scientific leans into higher value segments.
A clear recent reference point is Thermo Fisher Scientific’s update that all four operating segments recorded margin gains and that free cash flow of US$4.62b over nine months funded US$4.0b of buybacks and US$8.88b of acquisitions. That context matters when viewing a guidance upgrade built on pharma services and lab product strength.
Earlier comments on portfolio shifts, including the completed microbiology divestiture and contributions from deals like Clario and Solventum filtration, tie directly into current catalysts. Execution on integrating acquisitions, managing higher debt and backfilling revenue lost from disposals now sits alongside the earnings guidance as the practical test for the Thermo Fisher Scientific story.
Thermo Fisher Scientific's current earnings are about US$7.0b and analysts expect earnings to reach US$9.9b by 2029, which is an increase of roughly US$2.9b. This projection is based on an assumed 5.8% yearly revenue growth rate and forecast revenues of US$54.8b in 2029.
Uncover why Thermo Fisher Scientific's fair value indicates that Thermo Fisher Scientific is trading roughly in line with its current price.
Exploring Other Perspectives
The sharpest contrast comes from analysts who see the microbiology divestiture as a lasting headwind for Thermo Fisher Scientific. Before this Q3 update, the most cautious forecasts were still building to around US$54.8b of revenue and US$8.9b of earnings by 2029. That is well below consensus. Use those lower estimates as a reference point to explore how this new guidance might eventually shift both stories.
Explore 4 other Thermo Fisher Scientific fair value estimates, including one that indicates up to 17% downside from the current price.
Decide For Yourself
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your Thermo Fisher Scientific research is our analysis highlighting 2 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Thermo Fisher Scientific. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Thermo Fisher Scientific's overall financial health at a glance.
Looking For More Ideas Beyond Thermo Fisher Scientific?
Once you have formed a view on Thermo Fisher Scientific, it can help to compare that thesis with opportunities across the wider market. The Simply Wall St Screener lets you filter for traits that match your own risk tolerance and return goals, so you can build a watchlist that fits your style rather than copying anyone else’s.
- If you prefer companies that combine strong financials with what may be a discounted share price, start by checking out our 27 high quality undervalued stocks and see which businesses match that profile.
- If resilience matters most to you, especially when conditions turn choppy, filter for stocks using the 30 resilient stocks with low risk scores and focus on those with sturdier risk scores.
- If you are hunting for ideas that the broader market might be overlooking, broaden your research with the 21 high quality undiscovered gems and look for quality that is not yet widely followed.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com