
What QuickLogic Doubters Got Wrong
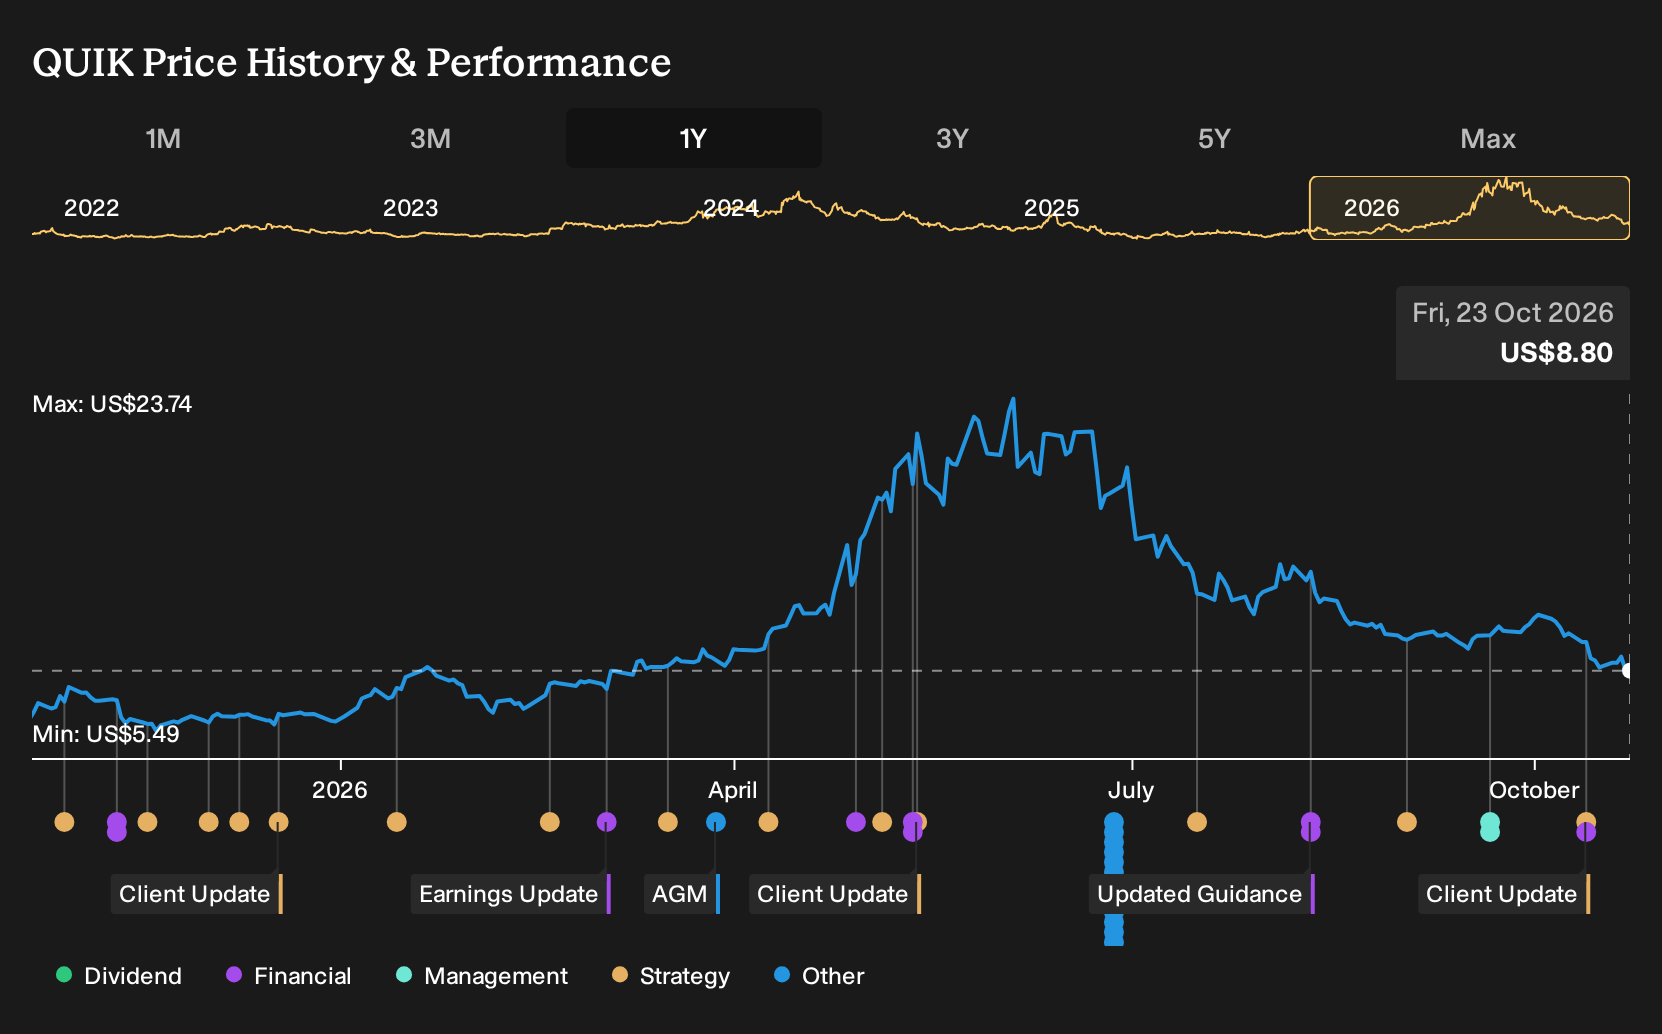
QuickLogic’s latest win came from a six-figure eFPGA IP deal tied to an automotive and industrial SoC, with future royalties linked to production shipments in areas like robotics and battery management. Investors who held QuickLogic over the past year are up 25.4%, including dividends. If you had been deciding in October 2025, what would you have needed to believe about onshore FPGA demand and contract durability to justify buying before that contract was announced?
Narratives are how investors here put a case on the record, with explicit assumptions about revenue, margins and the multiple. Those assumptions imply an estimated Fair Value.
QuickLogic is not the only name tied to this theme. Zero in on 39 AI small caps and compare how each one is priced.
The Two QuickLogic Stories Investors Had To Weigh
The shares cost US$6.52 at the start of the period, and anyone looking at QuickLogic then had to choose which earnings story felt more believable.
On the bullish side, the Fair Value was US$7.97. This was built on the idea that onshore, rad hard FPGA and eFPGA tools could support revenue growth of 26.3%, with profit margins reaching 14.1% and a future P/E of 41.6x.
The bearish Narrative put Fair Value at US$5.95 and treated contract concentration as the core hazard. This view still assumed 32.0% annual revenue growth, a 14.1% margin, and a lower future P/E of 27.2x.
What The QuickLogic Evidence Actually Tested
QuickLogic’s six-figure eFPGA IP win for an automotive and industrial SoC supported the bullish story about onshore FPGA demand and IP licensing. The Q2 2026 report showed revenue of US$5.482m versus US$3.687m a year earlier and the loss narrowing from US$2.661m to US$0.882m, with net margin improving from -72.2% to -16.1%. Profitability remained unproven, so the evidence pointed in both directions.
The key assumption here was that contract quality would translate into better earnings. For another chip stock, investors can track whether new design wins actually appear in segment revenue and net margin, not only in press releases or forward commentary.
What QuickLogic’s Price Already Bakes In
QuickLogic now trades at US$8.8, and the current Narrative’s Fair Value sits above that level based on its own framework and assumptions rather than settled fact.
The argument leans on defense eFPGA work, Intel 18A and storefront chiplets gaining traction. Investors need to consider whether current design and dev kit activity can become sustained, higher-margin shipments.
"The main thing that has to go right is that QuickLogic converts current design activity and dev kit interest into sustained storefront and chiplet product shipments while managing higher R&D and operating expenses."
One Narrative disagrees with today's price. → See where this Narrative says QuickLogic should trade
Before The Next Story Makes Headlines
You may be late to this rally, but that does not have to mean arriving late to every opportunity. Start with companies whose prices leave room for a different view of their future. Here are three trading below our estimates.
- Company 1 - 42% below our estimate - targets higher margin film and installation services as new capacity ramps.
- Company 2 - 40% below our estimate - scales device trade in and refurbishment activity as supportive policies broaden adoption.
- Company 3 - 49% below our estimate - works through a near record project backlog while containing remaining dispute exposures.
Those are three of them. See all 27 potentially undervalued companies →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com