
Why Innovent Biologics (SEHK:1801) Is Back In The Spotlight
Innovent Biologics (SEHK:1801) just reported positive Phase 3 data for its Claudin 18.2 targeted antibody drug conjugate, arcotatug tavatecan, in advanced gastric and gastroesophageal junction cancer. The results support a priority-review new drug application in China.
Despite the clinical win, Innovent Biologics' 30-day share price return is down 19.54% and the 7-day share price return is down 6.57%, while the 3-year total shareholder return of 84.89% points to a much stronger longer-term picture that investors are weighing against the recent pullback.
Capture how arcotatug tavatecan fits into the broader oncology opportunity set by comparing Innovent Biologics with our hand-picked 124 healthcare AI stocks that are building the next wave of data-driven drug development.Innovent Biologics has fresh clinical momentum and a long track record of shareholder gains, yet the share price just fell sharply over the past month. Does that pullback leave the stock looking mispriced, or fair for what you get today?
Preferred P/E of 100x: Is it justified?
Innovent Biologics closed at HK$83.20, yet the stock trades on a rich P/E of 100x that puts a clear premium on its earnings compared with peers.
The P/E ratio compares the current share price to earnings per share and gives you a quick read on how much investors are willing to pay for each dollar of profit. For a research driven biopharma group like Innovent Biologics, a high P/E often reflects expectations for strong future earnings expansion and confidence in a growing commercial portfolio rather than current profits alone.
That premium is not small. The P/E of 100x is far higher than the Hong Kong Biotechs industry average of 15.4x and also above the peer group average of 19.6x. This suggests the market is pricing in a much stronger earnings path than is implied for many competitors. It is even elevated against an estimated fair P/E of 37.2x. The current multiple therefore sits well above the level the market could move towards if sentiment cools or growth assumptions are revised.
Explore the SWS fair ratio for Innovent Biologics.
Result: Price-to-earnings of 100x (OVERVALUED)
Still, a rich 100x P/E leaves Innovent Biologics exposed if key drug launches disappoint or if sentiment toward high-multiple biotechs cools suddenly.
Find out about the key risks to this Innovent Biologics narrative.
Another view on Innovent Biologics' value
The rich 100x P/E paints Innovent Biologics as expensive, yet the SWS DCF model points in the opposite direction. At HK$83.20, the stock is described as trading about 46.1% below an estimated future cash flow value of HK$154.30. Two very different stories. Which one seems more realistic to you?
Look into how the SWS DCF model arrives at its fair value.
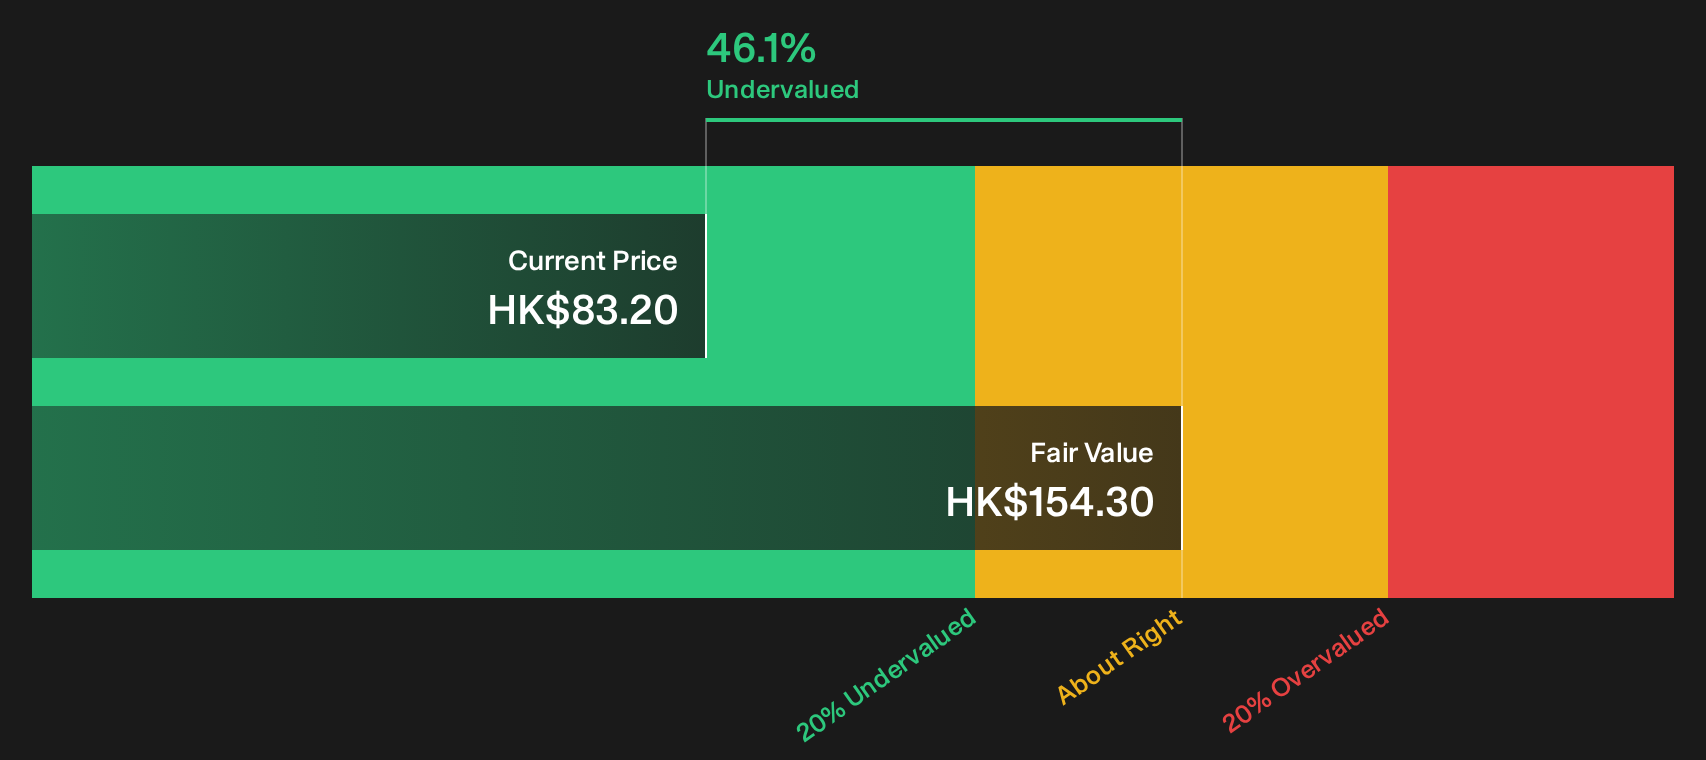
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Innovent Biologics for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Sentiment feels split after weighing Innovent Biologics' rich valuation against its fresh trial success, so it makes sense to move fast and test the numbers yourself. To see what optimistic investors are focusing on, take a closer look at the 4 key rewards.
Looking for more investment ideas beyond Innovent Biologics?
If Innovent Biologics has your attention, do not stop here. Broaden your watchlist now so you are not late to the next opportunity.
- Target potential mispricings early by scanning a curated 192 high quality undervalued stocks that blend quality fundamentals with attractively low expectations baked into current prices.
- Strengthen your income game by reviewing a focused 226 dividend fortresses designed for investors who want high yields backed by real business substance.
- Sleep easier at night by filtering for 221 resilient stocks with low risk scores that score well on financial resilience and lower volatility across market cycles.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com