
Is Peab (OM:PEAB B) A Bargain As Its Askim Contract Win Lifts Valuation Questions?
Peab (OM:PEAB B) has landed a NOK 319 million housing and commercial contract in Askim’s Bytorget project in Norway, putting a fresh construction order in focus for investors.
Peab’s NOK 319 million Bytorget win comes during a period where the share price has gained 8.86% year to date and the 1-year total shareholder return is 26.42%, hinting at building momentum despite a 6% share price pullback over the past month.
Scan how Peab’s contract win compares with other construction and infrastructure stocks showing fresh momentum by running through our hand picked list of solid balance sheet and fundamentals (204 results).
Peab appears to be a solid Nordic builder with fresh orders coming in and a strong recent return profile. The key question now is whether that track record and the new contract are already fully reflected in the share price.
Price-to-Earnings of 12.7x: Is it justified?
Peab shares last closed at SEK94, while the stock is being flagged as trading at good value with a P/E ratio of 12.7x compared with both peers and the broader European construction group. That gap suggests investors are paying less for each krona of earnings than the market is paying for similar businesses.
The P/E ratio compares the current share price with the company’s earnings per share. For a builder like Peab, which operates across construction, civil engineering and project development, this metric gives a quick read on how the market is pricing its profit engine relative to other listed contractors.
Peab is described as good value on several fronts. Its 12.7x P/E is below the European Construction industry average of 14.8x, and also below a peer average of 19.9x. It is also lower than the estimated fair P/E of 20.2x that the SWS fair ratio points to, a level the valuation work suggests the market could move towards if current earnings quality and growth forecasts hold.
Explore the SWS fair ratio for Peab.
Result: Price-to-Earnings of 12.7x (UNDERVALUED)
Still, Peab carries clear risks if construction demand weakens or if project execution stumbles, which could pressure both earnings and the current valuation case.
Find out about the key risks to this Peab narrative.
Another View: What The DCF Says About Peab
The P/E points to good value for Peab, yet the SWS DCF model goes even further. From that cash flow perspective, the share price of SEK94 sits below an estimated fair value of SEK174.85, which frames the current quote as firmly undervalued. Which signal should carry more weight in your process?
Look into how the SWS DCF model arrives at its fair value.
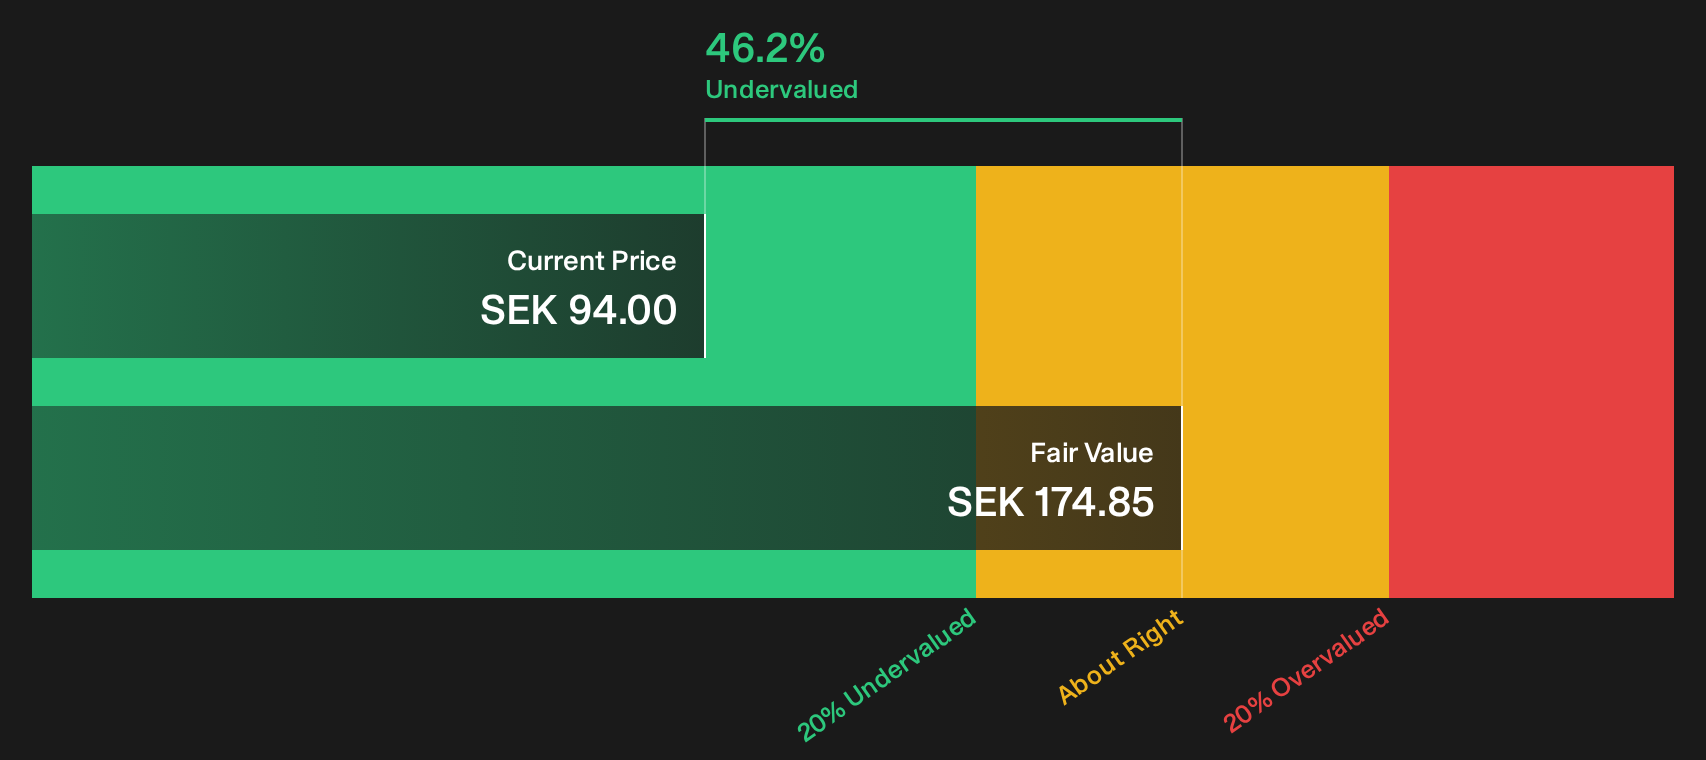
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Peab for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 192 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of upside signals and clear risks around Peab leaves you undecided, it may be useful to quickly review the underlying drivers and form your own stance. A good place to start is with a balanced view of both sides via the 4 key rewards and 2 important warning signs
Looking for more Peab sized investment ideas?
Round out your view on Peab by lining it up against other opportunities, so you are not relying on a single construction stock for ideas.
- Target potential bargains by scanning companies that line up in our valuation work as attractively priced using the 192 high quality undervalued stocks.
- Strengthen your income watchlist by focusing on businesses with robust payout profiles through the 226 dividend fortresses.
- Prioritise capital protection by filtering for businesses with resilient fundamentals and lower perceived risk via the 221 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com