
Cognex (CGNX) Reset Growth Expectations, Is The Stock Fully Priced?
Why Cognex Guidance Has Put Quarterly Results Under The Microscope
The recent update on Cognex (CGNX) reset expectations. Management is targeting about 14.6% revenue growth for fiscal 2026, with adjusted earnings projected to climb at an even faster pace.
That mix of stronger top line ambitions and faster profit expansion has changed how investors weigh every upcoming quarter. The next revenue print now acts as a practical test of whether the current share price still lines up with the growth story.
Cognex enters this guidance reset with clear momentum in the background, with a 1-day share price return of 1.74%, a year-to-date share price gain of 50.42%, and a 3-year total shareholder return of 64.03%. However, the 90-day share price return is down 10.48% and the 5-year total shareholder return is down 34.47%. This suggests that recent optimism is building on a longer and more mixed track record as investors reassess both growth potential and execution risk around the new outlook.
Scan other robotics and automation plays moving on similar guidance stories by checking the hand picked 95 robotics and automation stocks alongside Cognex.
Cognex now trades at US$55.55 while the average analyst target sits near US$79, and the modelled intrinsic value implies a very different story again. So where does fair value actually look anchored today?
Most Popular Narrative: 30% Undervalued
The most followed Cognex narrative anchors fair value around $79.58, well above the last close at $55.55. This puts guidance and execution under a sharper spotlight for anyone weighing the gap between the two figures.
The main factor that has to go right is that Cognex successfully executes its diversification and operating model transformation. This includes integrating RealSense, scaling newer verticals such as packaging and data centers, and maintaining high incremental margins and strong free cash flow conversion.
See why 33 investors see Cognex as 30% undervalued.
Result: Fair Value of $79.58 (UNDERVALUED)
Still, the Cognex story can crack if machine vision hardware pricing pressure squeezes margins, or if the RealSense acquisition underdelivers after consuming most of the cash pile.
Find out about the key risks to this Cognex narrative.
Another View: Cognex Through The P/E Lens
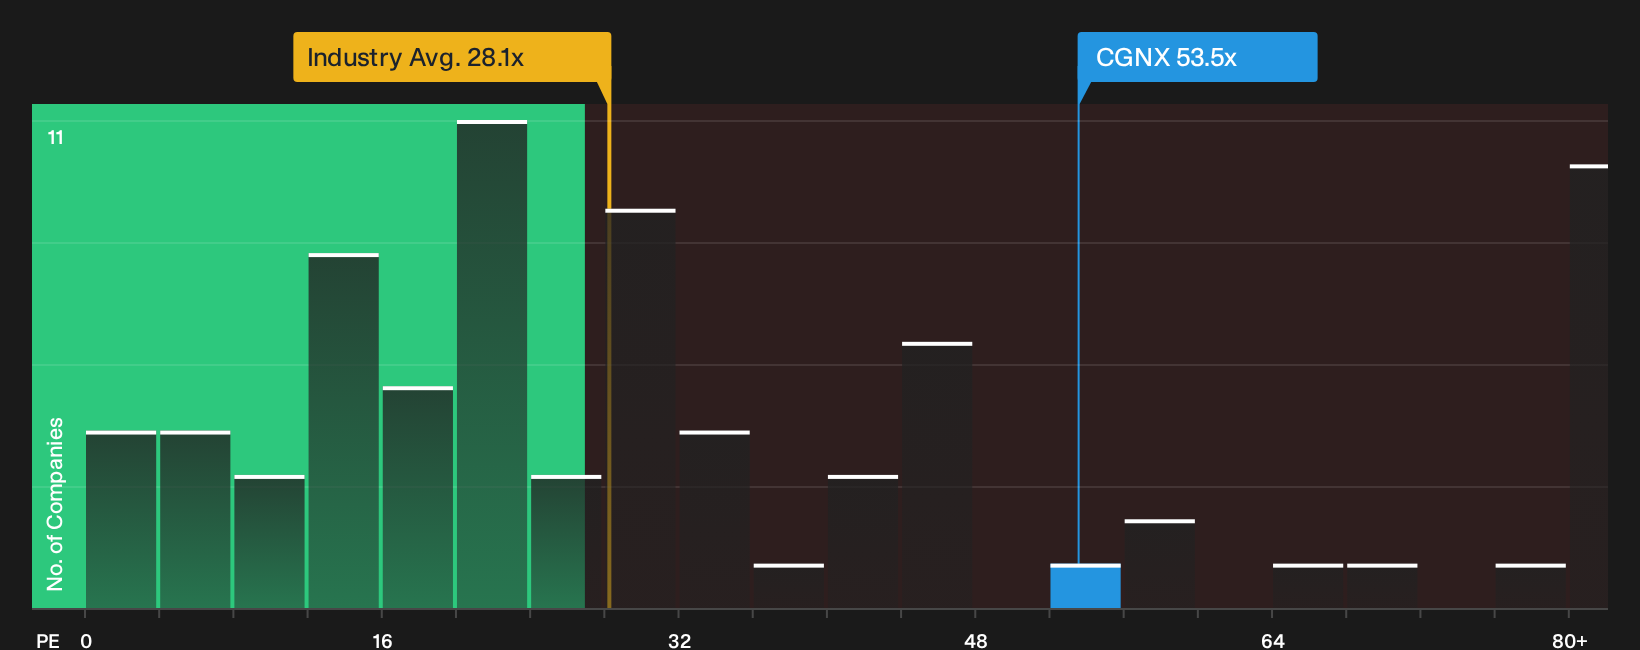
Cognex might look cheap against a $79.58 fair value from the narrative model, but the P/E picture tells a tougher story. The stock trades on 53.5x earnings, compared with 28.1x for the US Electronic industry, 43.2x across peers, and a fair ratio of 32.4x.
That is a wide gap. It suggests investors are already paying a hefty premium for future execution on AI vision, RealSense and margin targets, which raises the risk of disappointment if guidance or growth expectations slip from here.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Debate around Cognex is clearly heating up, so do not just lean on the loudest narrative when the data is right in front of you. Take a few minutes to review the potential upside yourself, starting with the 3 key rewards.
Looking For More Ideas Beyond Cognex?
Do not stop your research with Cognex. Broaden your watchlist with a few focused stock ideas that match different goals so potential opportunities do not slip past you.
- Target long term compounders with resilient earnings profiles by scanning a 30 resilient stocks with low risk scores that keeps downside firmly in view.
- Hunt for quality at a sensible entry point by reviewing a curated 27 high quality undervalued stocks that filters for fundamentals first.
- Stack potential income streams by checking a focused 5 dividend fortresses that concentrates on higher yielding payers.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com