
Did AI Go Launch Just Shift Procore Stock's Investment Narrative?
- Procore Technologies has launched Procore AI Go, a voice-first mobile app and AI glasses experience with Meta, and is collaborating with IBM to link its construction platform to IBM Maximo for connected asset lifecycle data.
- Together, voice-driven field access and tighter IBM Maximo integration push more project and asset data through Procore’s platform, which can affect customer productivity, data stickiness, and willingness to adopt higher-tier packages.
- We will now look at how Procore AI Go, particularly its IBM Maximo integration, could reshape Procore Technologies' investment narrative.
Scan beyond Procore Technologies and this IBM Maximo and AI story by sizing up a curated field of construction and infrastructure software peers in the 55 AI infrastructure stocks.
Procore Technologies Investment Narrative Recap
To own Procore Technologies, you need to believe its construction platform can keep pulling more workflows and data into one place, then monetize that through product breadth and AI. The near term swing factor is whether AI tools like Procore AI Go translate into higher usage and attach rates without disrupting existing sales motions in a still choppy construction cycle.
The biggest risk remains exposure to North American construction activity and competition from other software and AI providers. The new launches do not remove that macro and competitive overhang. They mostly sharpen the existing product story rather than creating a new, standalone catalyst in the short run.
The IBM Maximo collaboration looks most relevant for the current thesis. It tries to tie Procore Asset Management data into long term operations systems, which can matter for owners that care about a consistent record from build to maintenance. For you, the question is whether that tighter data thread increases stickiness and justifies broader deployments.
If Procore executes well on the Maximo link, that could support the catalysts analysts already focus on, such as higher average revenue per customer and better international appeal for large capital projects. Execution risk is real though. Complex integrations can be slow, and any friction at handover between construction and operations teams would limit how much impact this has on growth or margins.
Procore Technologies' current analyst narrative points to US$2.0b in revenue and US$141.6m in earnings by 2029. That profile assumes revenue expansion of 13.4% a year and an earnings swing of about US$218.5m from a loss of US$76.9m today to the projected profit.
Uncover how Procore Technologies' fair value indicates a 10% potential upside to its current price before sentiment around Procore Technologies closes that discount.
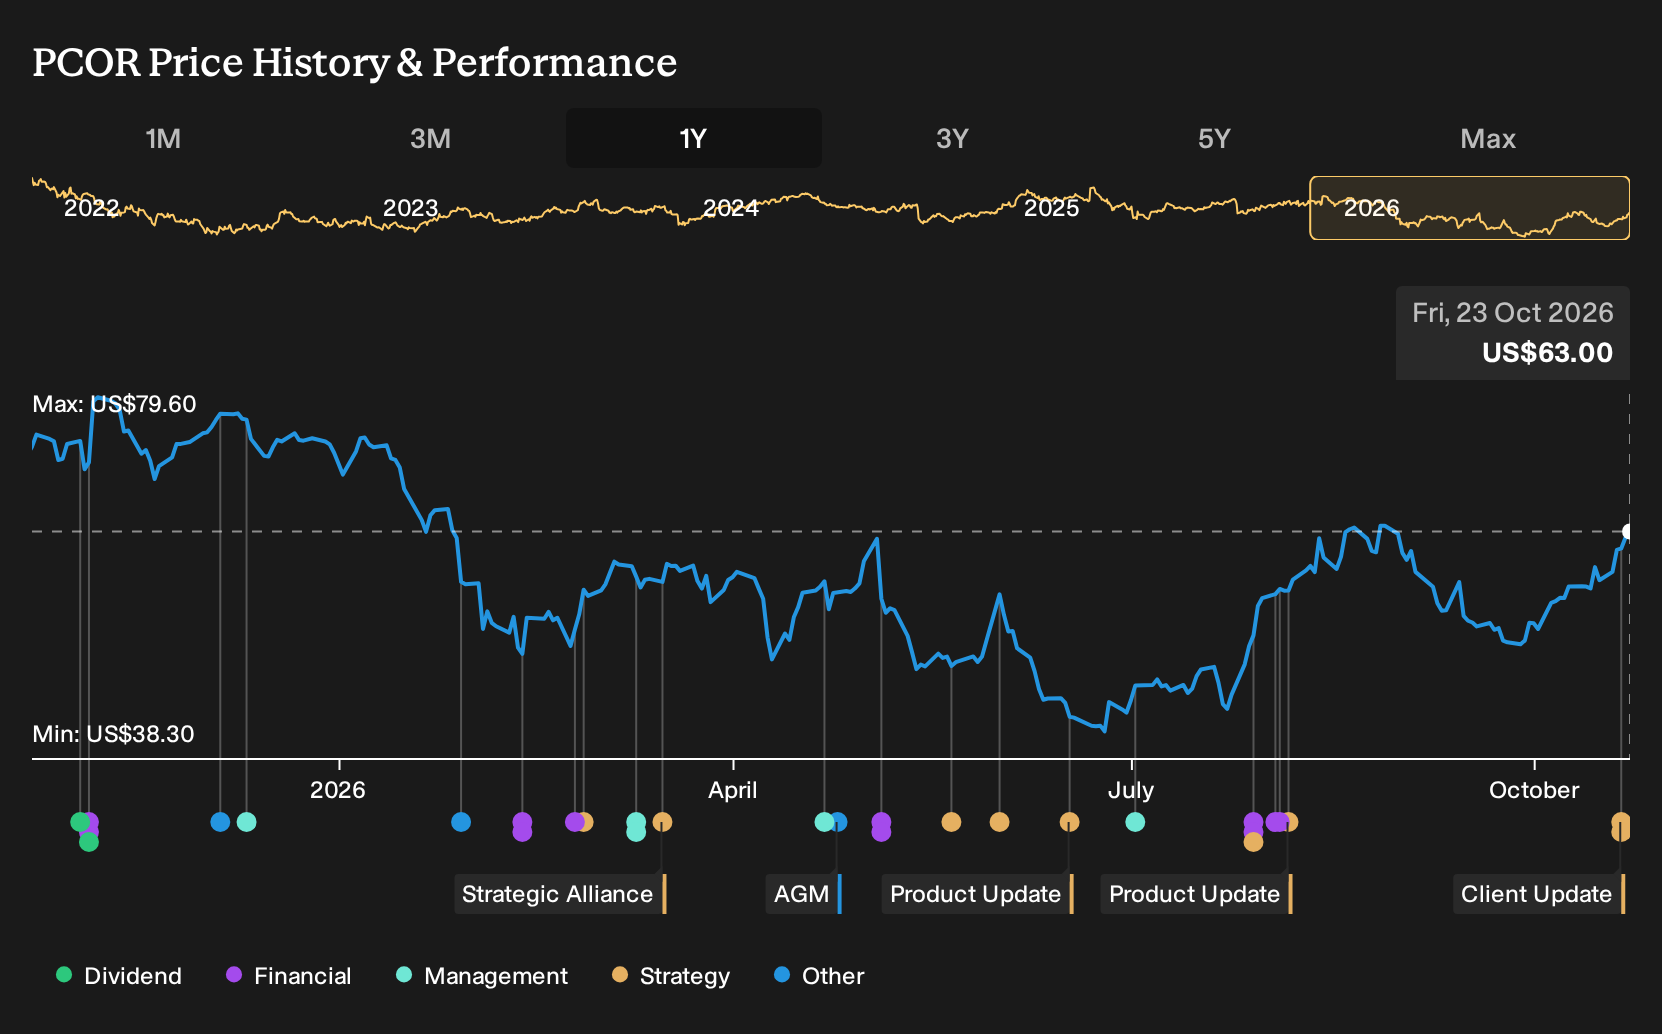
Exploring Other Perspectives
Some of the most optimistic analysts lean into AI automation as the key catalyst, arguing Procore Technologies could justify forecasts of US$2.1b in revenue and US$176.0m in earnings by 2029. You can see how Procore AI Go and the IBM Maximo link might push those views further, or prompt fresh debate, so it pays to compare several narratives before deciding your stance.
Explore 4 other Procore Technologies fair value estimates, including one that suggests as much as 35% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so trust your own analysis.
- A great starting point for your Procore Technologies research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Procore Technologies. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Procore Technologies' overall financial health at a glance.
Looking For More Ideas Beyond Procore Technologies?
Once you have a view on Procore Technologies, it can help to widen the lens and compare it with other opportunities that share similar quality or risk traits. The Simply Wall St Screener lets you filter for different profiles in a few clicks so you can build a watchlist that fits your own risk and return preferences.
- If you want stability to anchor your portfolio, start with a 30 resilient stocks with low risk scores that may help keep volatility in check.
- For investors hunting for quality at a reasonable price, a 27 high quality undervalued stocks can surface companies where fundamentals and price are out of sync.
- Those looking for strong foundations without stretching for story stocks can focus on a list of solid balance sheet and fundamentals (25 results) and see which businesses back their narratives with robust finances.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com