
Whitbread (LSE:WTB) Resists Corvex Board Push, Is The Upside Already Priced In?
Whitbread (LSE:WTB) is in the spotlight after half year earnings showed net income of £61.7 million versus £216.9 million a year earlier, alongside fresh resistance to activist Corvex Management’s push for a new board appointment.
Recent trading tells a mixed story. The 1 month share price return of 12.0% and 90 day gain of 6.7% suggest momentum has picked up around Whitbread’s £26.01 share price, even though the 1 year total shareholder return is down 13.7% and longer term returns have also declined.
Compare Whitbread’s recent swings with a hand picked 8 high quality undervalued stocks that currently show stronger momentum or cleaner value stories in this part of the market.
Given Whitbread’s sharp profit drop but recent share price rebound, investors now have to judge whether the better news is already reflected in the price or if the latest move still leaves meaningful upside ahead.
Most Popular Narrative: 3% Undervalued
Against Whitbread’s last close of £26.01, the most followed narrative pegs fair value at about £26.86, suggesting only a modest gap while hinging heavily on how asset recycling and Germany reshape returns.
The current valuation implies the share price already reflects a fair outcome in which Whitbread funds high return growth through £1.5b of property recycling, maintains investment grade leverage and achieves its UK and German profit ambitions.
See why 31 investors see Whitbread as 3% undervalued.
Result: Fair Value of £26.86 (UNDERVALUED)
Still, the Whitbread story could be knocked off course if higher UK business rates bite harder than planned, or if the £1.5b property recycling raises funding strain.
Find out about the key risks to this Whitbread narrative.
Another View On Whitbread’s Valuation
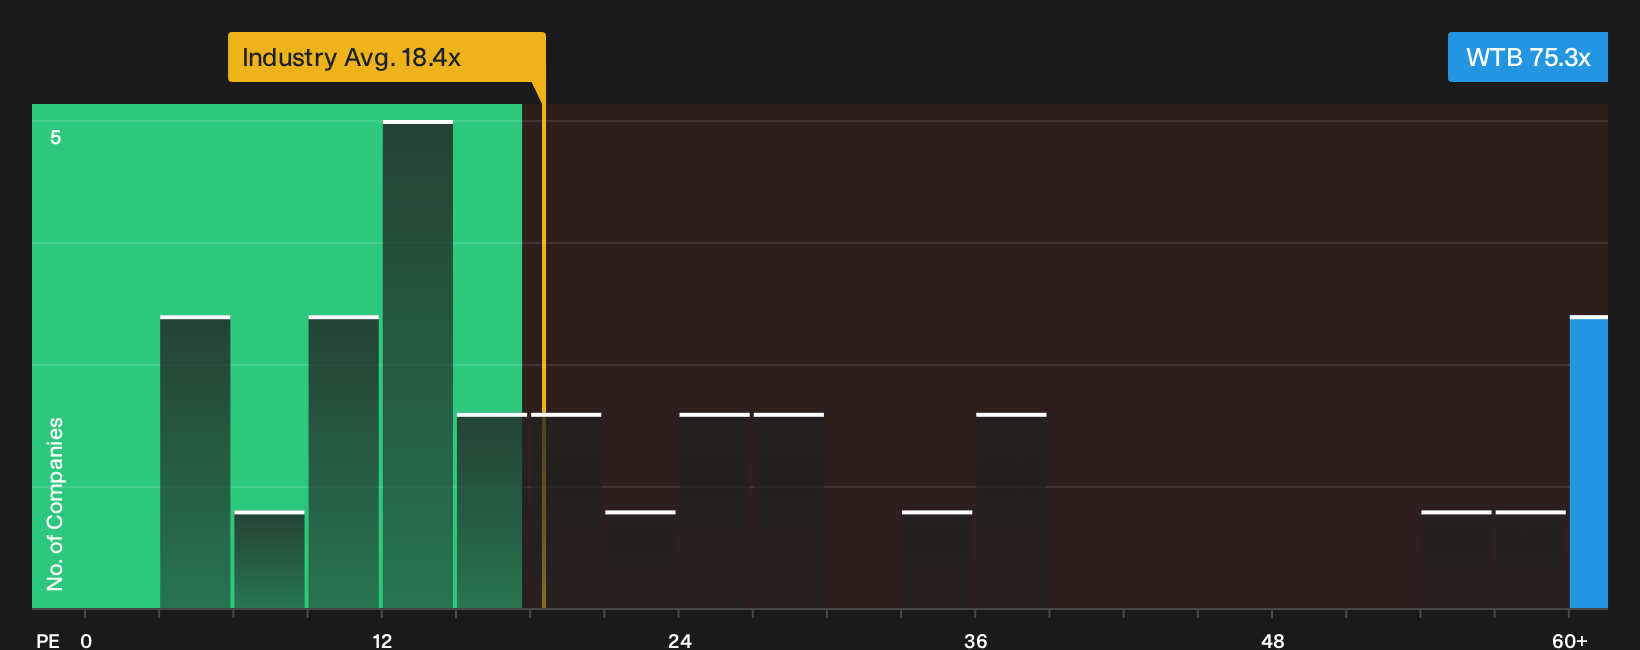
There is a twist when the focus shifts from fair value estimates to what Whitbread actually trades on today. The shares sit on a P/E of 75.3x, while the fair ratio sits at 25.9x, the UK Hospitality industry at 18.4x and peers around 14.9x.
That kind of gap points to a lot of optimism already embedded in the price, and leaves less room for disappointment if earnings or margins fall short of expectations. The question for you is whether Whitbread’s long term plans justify paying such a rich multiple.
See what the numbers say about this price — find out in our valuation breakdown.
Next Steps
Mixed signals around Whitbread’s valuation and outlook can pull you in both directions, so move quickly from headline impressions to your own judgement by weighing the 2 key rewards and 3 important warning signs.
Looking For More Investment Ideas Beyond Whitbread?
If Whitbread has raised fresh questions for you, you may want to balance that view by scanning other opportunities where quality, value and risk profiles line up more clearly.
Do not leave fresh ideas to chance. Use the Simply Wall Street Screener to quickly surface focused shortlists that match the way you prefer to invest.
- Spot potential bargains early by reviewing a 5 high quality undiscovered gems that pairs strong fundamentals with limited current market attention.
- Protect capital more deliberately by filtering for a 4 resilient stocks with low risk scores that focuses on businesses with sturdier financial risk profiles.
- Anchor your watchlist to resilience by starting with a list of solid balance sheet and fundamentals (9 results) that emphasises stronger balance sheets and underlying fundamentals.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com