
Should Manufacturing Deal Progress Require Action From Becton Dickinson (BDX) Investors?
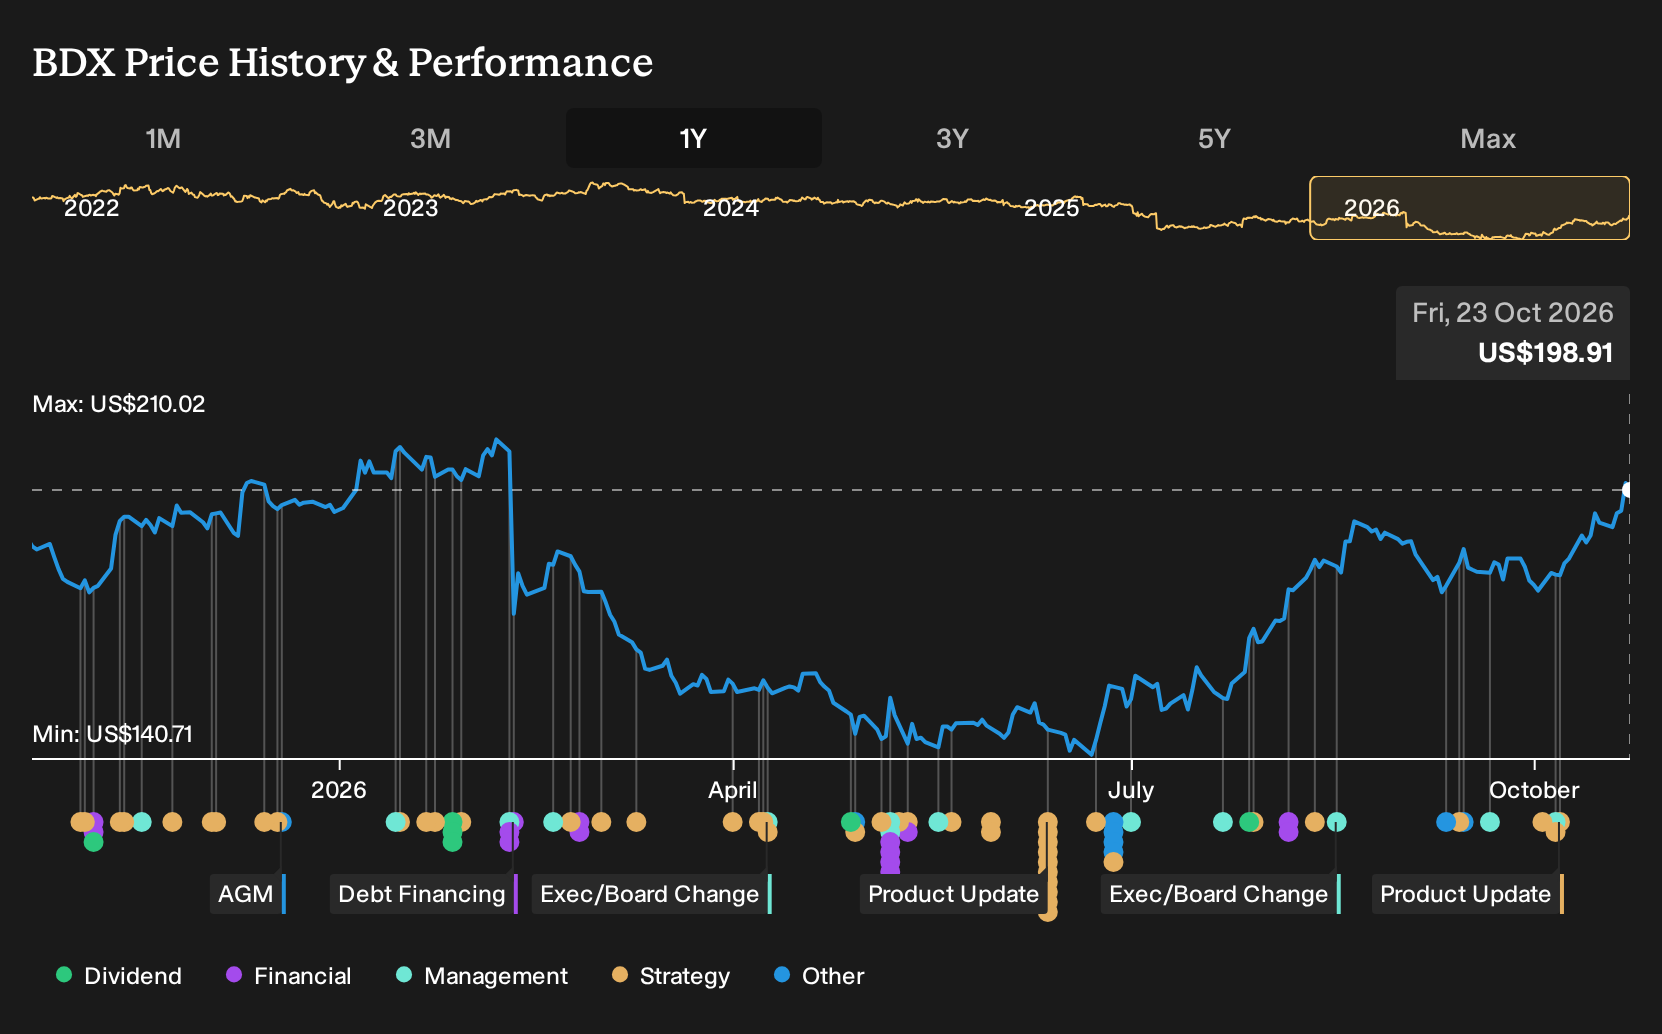
- Becton Dickinson has recently reported stronger execution, progress in high growth units and continued product development, ahead of its fiscal Q4 2026 earnings release set for 5 November 2026.
- A large U.S. manufacturing agreement and new clinical trial milestones are shaping how Becton Dickinson allocates capital and prioritizes higher margin platforms.
- Next, the focus will be on how Becton Dickinson's execution-led program and clinical progress influence its broader investment narrative.
Scan how Becton Dickinson's recent execution story compares with other high quality healthcare peers by reviewing our hand picked 30 resilient stocks with low risk scores.
Becton Dickinson Investment Narrative Recap
To own Becton Dickinson, you need to believe the core medtech franchises, recurring consumables and BD Excellence productivity work can offset pockets of pressure such as weaker China demand, Alaris replacement headwinds and recall related issues. The recent share price strength and upcoming Q4 2026 report put execution on costs, mix and quality controls firmly in the spotlight.
The near term catalyst is whether earnings can grow even as sales are projected to dip, supported by higher margin platforms and plant productivity gains. The key risk is that quality or regulatory issues, combined with the fading Alaris uplift, make reported growth and cash generation look softer than the underlying narrative suggests.
The recent large U.S. manufacturing agreement is the clearest operational read through for this setup. It gives Becton Dickinson extra volume visibility in BioPharma Systems and drug delivery. This ties directly into the roughly 100 GLP 1 related contracts and the broader biologics mix already supporting recurring revenue.
For you as a shareholder, the question is whether that incremental manufacturing load meaningfully offsets pressures such as China price competition, infection prevention remediation and the coming Alaris drag. If execution stays tight, this type of long dated contract can help keep plant utilization healthier, support the intended 8% productivity gains and reduce the strain on already stretched operating cash flow coverage of debt.
What The Current Becton Dickinson Forecasts Assume
For Becton Dickinson, the analyst playbook is unusually clear on the trade off. Forecasts bake in a slow 1.6% yearly decline in revenue over the next three years, while expecting much stronger profitability as the BD Excellence program and higher margin platforms do more of the heavy lifting.
On earnings, the consensus view anchors on profit of US$1.6b today stepping up to US$3.3b by 2029. That is an increase of roughly US$1.7b in annual earnings, with profit margins assumed to rise from 7.3% to 15.6% over the same stretch as mix, pricing and plant efficiency work harder than top line growth. The split between the most bullish US$4.6b earnings estimate and the more cautious US$2.4b highlights how differently analysts weigh the Alaris drag, China pricing pressure and the durability of recent manufacturing wins.
Putting those assumptions into a simple valuation frame, the market view hinges on Becton Dickinson shifting from a P/E of 30.1x today to 17.5x on those 2029 earnings. This sits below the current US medical equipment sector level at 24.7x. That implies investors are being asked to accept slower revenue, higher earnings power and a lower multiple, a combination that only really works if margin execution and cash conversion keep tracking the BD Excellence ambitions.
Becton Dickinson's narrative projects US$21.4b revenue and US$3.3b earnings by 2029. This rests on revenue decreasing by 1.6% per year and an earnings increase of about US$1.7b from US$1.6b today.
Uncover why Becton Dickinson's fair value indicates that Becton Dickinson is in line with its current price.
Exploring Other Perspectives
You have a very different story if you lean into the bullish view that Becton Dickinson’s GLP 1 and biologic delivery work can outweigh tariff and recall risks. Those optimistic analysts were penciling in about US$22.3b revenue and US$4.6b earnings by 2029 before this latest execution news, so those forecasts and opinions may shift as fresh information lands.
Explore 2 other Becton Dickinson fair value estimates, including one that suggests up to 18% upside from the current price.
Reach Your Own Conclusion
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so consider trusting your own analysis.
- A great starting point for your Becton Dickinson research is our analysis highlighting 4 key rewards and 2 important warning signs that could impact your investment decision.
- See our latest analysis for Becton Dickinson. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Becton Dickinson's overall financial health at a glance.
Looking for more Becton Dickinson investment ideas?
If the Becton Dickinson story has you thinking about portfolio construction more broadly, it can help to line it up against other opportunities that share similar qualities or offer very different profiles. The Simply Wall St Screener gives you a structured way to do that in a few minutes.
- For readers who want income that does more of the heavy lifting, scan a universe of companies offering robust payouts and assess potential candidates through the 5 dividend fortresses.
- If capital preservation and balance sheet strength matter most to you, filter for businesses with cleaner finances and steadier fundamentals using the list of solid balance sheet and fundamentals (25 results).
- Those looking to cast a wider net beyond widely followed large caps can review financially sound smaller opportunities using the 21 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com