
What Eldorado Gold Holders Bought Into
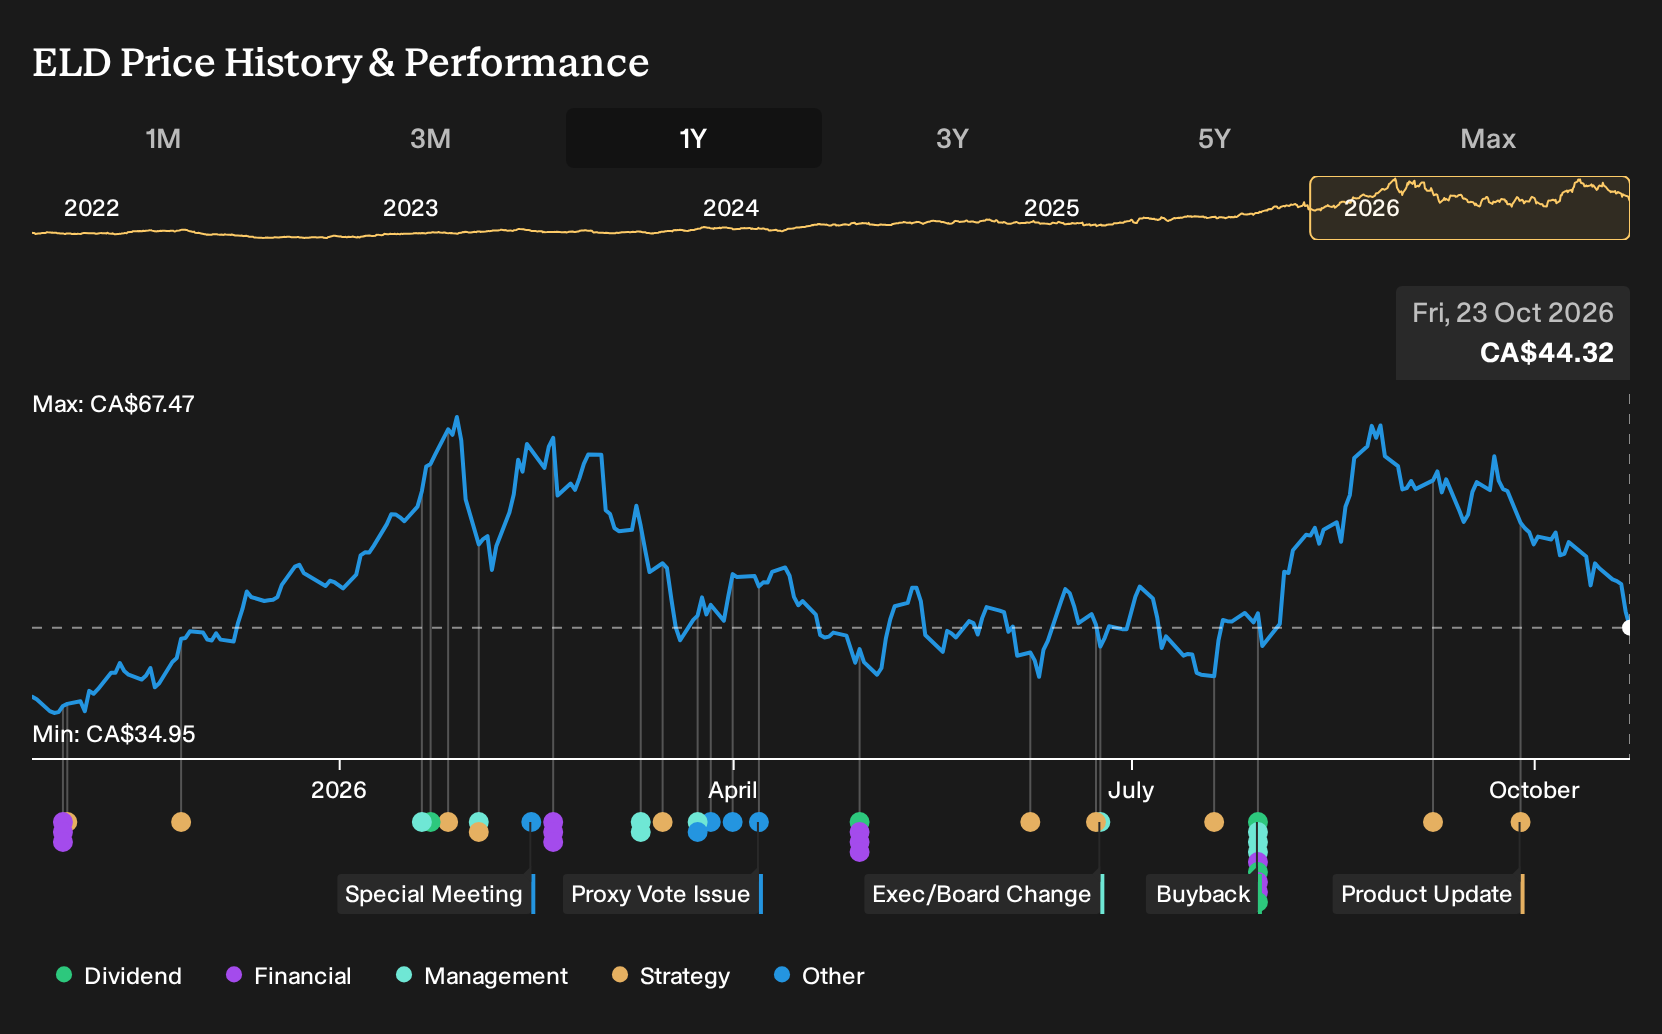
If you only glanced at Eldorado Gold headlines over the past year, with bullish analysts talking up Skouries and Olympias while skeptics warned about ESG pressure and decarbonization, the outcome might surprise you. Investors who held Eldorado Gold over the past year are up 22.3%, including dividends. If you were weighing those sharply different July 2025 research views, what in the actual business story made that kind of payoff a reasonable risk to take?
Eldorado Gold is not the only name tied to this theme. Zero in on 35 elite gold producer stocks and compare how each one is priced.
The Argument You Would Have Been Weighing On Eldorado Gold
The shares cost CA$36.72 at the start of the period, and Eldorado Gold sat between two very different yet plausible stories.
On the bullish side, the implied Fair Value was CA$40.86, a price that reflected what believers thought the business could be worth if things broke right. That view leaned on Skouries and Olympias ramping smoothly, with project completion and cost declines feeding into stronger cash flow and wider net margins.
The bearish Narrative put Fair Value at CA$28.46, an estimated worth that baked in tougher conditions. This camp focused on ESG pressure, higher input costs, and regulatory risk in Greece and Turkey as forces that could squeeze profitability and keep the multiple closer to a low P/E assumption.
What The Results Changed For Eldorado Gold
The strongest new fact for Eldorado Gold came from its Q2 2026 report. Revenue reached US$487.456 million and net income was US$172.817 million, with net margin moving from 30.8% to 35.5%. Progress at Skouries toward first concentrate production and the launch of a sustainable dividend and large buyback all leaned toward the optimistic case, although higher Skouries capex kept execution risk in view. Overall, the evidence cut both ways but leaned supportive.
The key lesson is simple. When a thesis hangs on projects like Skouries and Olympias and on cash flow improvement, you track reported net margin and concrete project milestones, not just production guidance or analyst targets.
What Eldorado Gold's Price Now Asks You To Believe
Today Eldorado Gold trades at CA$44.32. The selected Narrative argues that Fair Value sits above the current price, based on copper heavy projects like Skouries and McIlvenna Bay reshaping earnings mix and cost profile if ramp ups stick to the updated plans.
From that perspective, a buyer at today’s price is effectively assuming the market still underestimates how much low to negative cost copper linked output and cash returns could change Eldorado Gold’s longer term cash generation.
"Current numbers, including cash on hand, project financing, and ongoing dividends and buybacks, indicate that the market is still pricing Eldorado Gold as if higher-cost legacy production, execution risk, and elevated debt will weigh more heavily on the share price than the cash flow potential of its emerging low to negative cost copper-gold growth projects."
One Narrative has put a figure on that disagreement. → See the Narrative with its higher Fair Value, assumptions and all
Another Way To Think About Copper
Eldorado Gold points you toward copper linked mines and cash flow. Just beyond that, a different copper story starts to emerge.
Global electrification plans require additional raw copper, not only gold byproducts. That leaves space for a miner centered on direct copper production.
This other business relies on larger, more efficient pits and processing lines. It aims to manage costs carefully as output expands.
Project build outs, water constraints and permitting risks still matter. If they are handled well, its role in meeting copper demand could shift meaningfully.
Could this be another way into the opportunity? → Explore the copper opportunity and its 38% discount to one Narrative's Fair Value
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com