
Kuehne + Nagel International (SWX:KNIN) Q3 Earnings Justified Its Premium Multiple
Kuehne + Nagel International walked into its Q3 2026 report with a rich 27.6x P/E, a slightly softer 3.8% net margin over the past year, and a share price that had drifted lower over the last month. The headline today is Q3 earnings power catching up with that premium multiple, as recurring EBIT and basic EPS both came through as solid proof points rather than just a valuation story.
The stock closed at CHF227.10 on 23 October. This leaves investors to decide whether a weaker recent share return and slim margin compression really justify the cautious mood when Q3 revenue reached CHF7,386m and net income came in at CHF307m.
Like the earnings power at Kuehne + Nagel International but uneasy about paying a premium P/E for single digit margins and a recently softer share price? Filter for transport and logistics peers with sturdier profitability profiles in our list of solid balance sheet and fundamentals stocks (204 results)
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): CHF 7,386m vs CHF 6,043m (up 22.2%)
- Net Income (Excl. Extra Items, Q3 2026 vs Q3 2025): CHF 307m vs CHF 194m (up 58.2%)
- Basic EPS (Q3 2026 vs Q3 2025): CHF 2.57 vs CHF 1.63 (up 57.7%)
- Trailing Net Profit Margin (last 12 months vs prior year): 3.8% vs 4.0% (margin compressed by 0.2 percentage points)
Earnings tell part of the story, but investors who care about what they are really paying for usually anchor on the cash coming through the door. When you look at Kuehne + Nagel International's cash flows rather than just the income line, the stock could be a dramatic 40% undervalued.
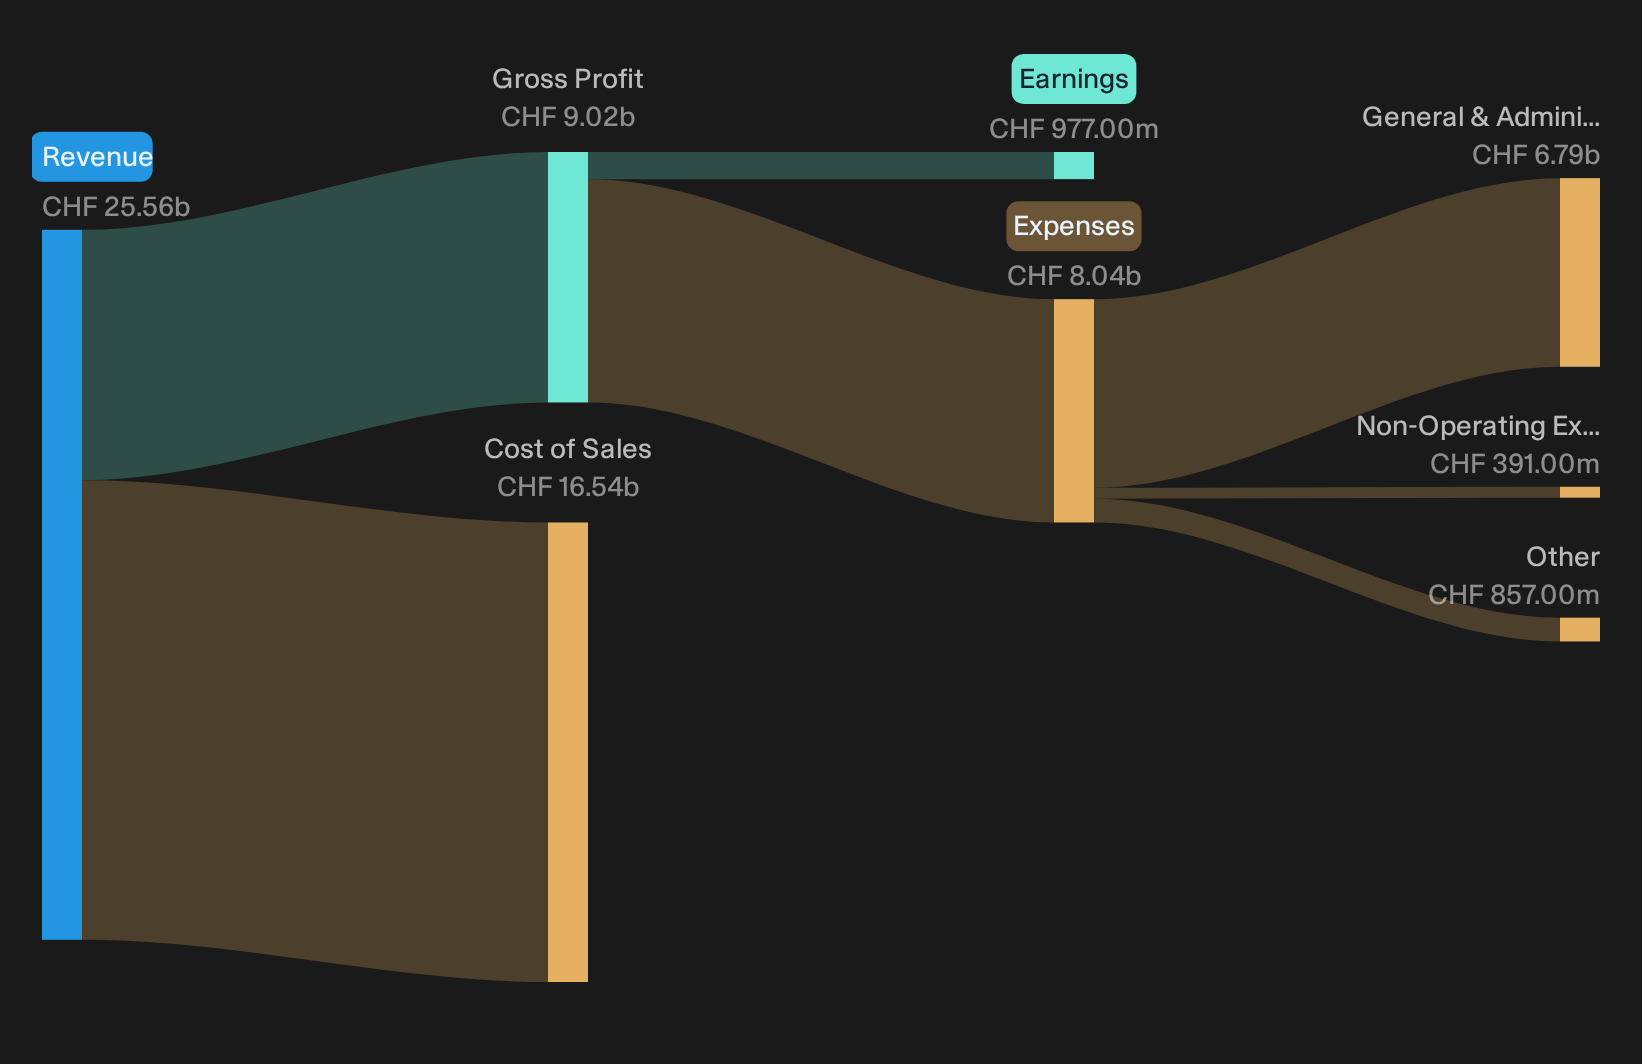
Kuehne + Nagel Execution Thesis Faces Real Scorecard
The bullish script hangs on execution more than freight cycles.
"The main thing that has to go right is that AI productivity gains and the cost reduction program continue to convert into higher recurring EBIT and free cash flow without freight yield pressure or start-up costs in Sea and Contract Logistics eroding those benefits."
On that score, Kuehne + Nagel is hitting early milestones. Recurring EBIT in Q3 rose 53% and management lifted 2026 recurring EBIT guidance to CHF 1.5 to 1.6b. Cost savings reached about CHF 100m year to date with a run rate of at least CHF 200m already in sight, while Q3 free cash flow of CHF 336m and roughly 105% cash conversion back up the cash side of the story.
One Narrative has put a figure on that disagreement. → See the Narrative with its lower Fair Value, assumptions and all.
Kuehne + Nagel Bear Case Meets Mixed Evidence
The skeptical view hangs on execution risk around AI and cost savings at Kuehne + Nagel International.
"The main thing that has to go right is that AI driven productivity gains and the cost reduction program translate into the targeted CHF 200m plus of annualized savings and CHF 100 to 150m of additional EBIT by end 2027 without eroding service quality."
Q3 cuts against the fear on cost delivery. Management already reports about CHF 100m savings year to date and now expects an annualised run rate of at least CHF 200m by year end 2026. The raised recurring EBIT guidance to CHF 1.5 to 1.6b also leans against underdelivery. The AI uplift, though, remains unproven with benefits still guided to start in 2027, so that part of the concern stays unresolved in this print.
Hunt For Mispriced Execution Stories
Kuehne + Nagel International recently highlighted how execution and sentiment shifts can change valuation multiples. The real opportunity could be in stocks that appear undervalued before expectations adjust.
- Company 1 - 20% below our estimate - leans into secured, granular lending as collection efficiency and asset quality remain resilient through leadership transition and increased investment.
- Company 2 - 24% below our estimate - folds in specialist distributors so higher value-added electrical and automation projects increasingly influence margins and the overall contract mix.
- Company 3 - 23% below our estimate - pushes clinically-backed probiotics into mainstream adult channels as retailers expand shelf space for preventative health-focused products.
Three companies from the same screener. Open the full list of 192 companies trading below our fair value estimates →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com