
Shore Bancshares (SHBI) Q3 Earnings Counter Rising Credit Risk
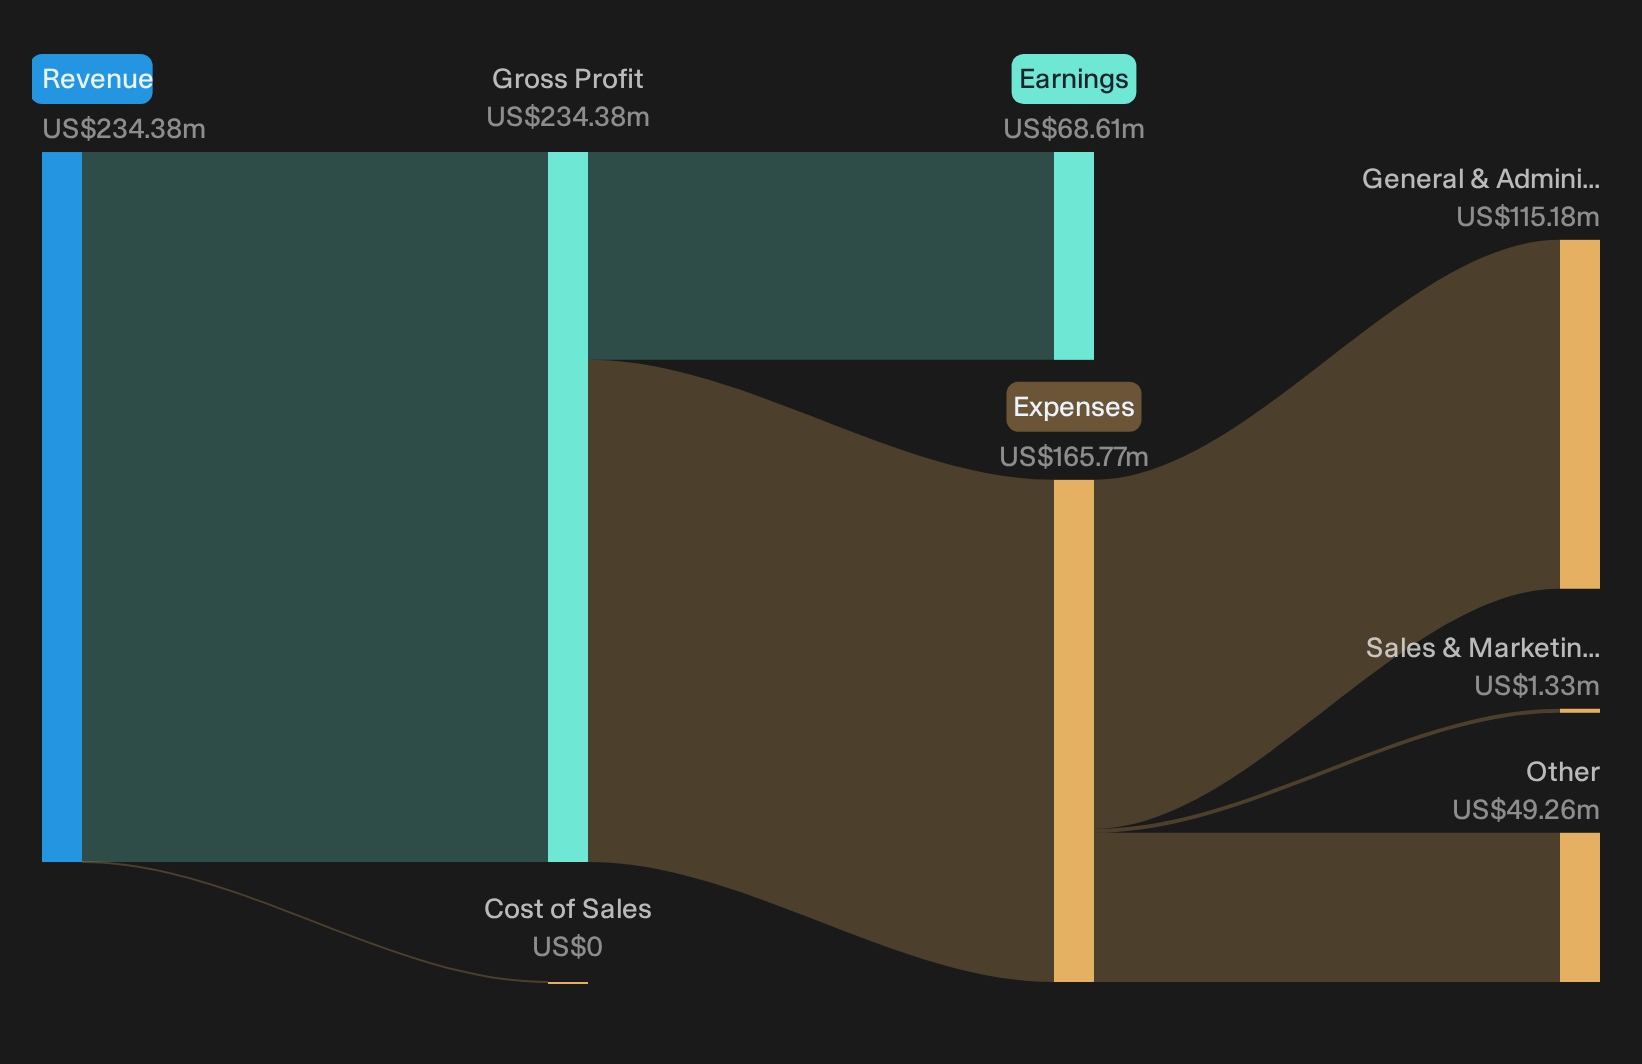
Shore Bancshares slipped 1.9% to US$22.94 on Friday, yet the fresh Q3 2026 earnings tell a calmer story than that red screen suggests. The bank posted basic earnings per share of about US$0.50 on revenue of roughly US$57.5m, with net income close to US$16.8m. The real tension sits on the balance sheet. Non performing loans have climbed sharply over the past year, while the allowance for bad loans sits at 91%. This keeps credit risk and long term capital protection squarely in focus for anyone holding the stock beyond this quarter.
Like Shore Bancshares' income profile but uneasy about rising non performing loans and the 91% allowance coverage? Compare that credit risk trade off with banks in our list of solid balance sheet and fundamentals stocks (25 results).
Q3 2026 Earnings Summary
- Revenue (Q3 2026 vs Q3 2025): US$57.53m vs. US$53.36m (up about 7.8%)
- Net Income (Q3 2026 vs Q3 2025): US$16.77m vs. US$14.35m (up about 17%)
- Basic EPS (Q3 2026 vs Q3 2025): US$0.50 vs. US$0.43 (up about 17%)
- Net Interest Margin (Q3 2026 Trailing 12 Months vs Q3 2025 Trailing 12 Months): 3.64% vs. 3.36% (showing a modest improvement in lending spread)
Ask Charlie what makes Shore Bancshares look undervalued now.
Shore Bancshares earnings still back a cautious bull
For anyone leaning positive on Shore Bancshares, this quarter gives the thesis fresh fuel. Revenue reached about US$57.5m and net income roughly US$16.8m, with basic EPS near US$0.50. All three metrics moved higher than Q3 2025. Net interest margin improving to 3.64% from 3.36% fits a story of a traditional lender getting more out of its book. The share price slipped 1.9% after the release. Even so, the profit trend still lines up with a cautiously constructive view of the underlying franchise.
Credit quality and capital protection keep bears engaged
The concern around Shore Bancshares sits with credit, not earnings. Non performing loans have risen sharply over the past year, while the allowance for bad loans covers 91% of that problem pool. That ratio leaves limited room if troubled credits keep building. The recent 90 day share return is down about 2.8%, which suggests that investors remain wary of balance sheet risk even as profitability improves. For a more negative thesis, the direction of asset quality, rather than income growth, is the key validation point right now.
Are analysts backing the cautious bull case for Shore Bancshares, or fading it as credit worries build? Check the consensus price target analysis for Shore Bancshares.Hunt Quiet Disconnects In Plain Sight
Shore Bancshares shows how a solid earnings story can sit alongside balance sheet concerns. The real opportunity is finding stocks that could be undervalued before the market adjusts.
- Company 1 - 37% below our estimate - helps large online platforms collect and send funds across emerging markets using higher margin payment tools and automation.
- Company 2 - 33% below our estimate - sells the compute racks and software stack that power many data centres racing to host heavier AI workloads.
- Company 3 - 36% below our estimate - focuses on fee rich advisory mandates as new senior hires convert a larger backlog of capital raising and restructuring assignments.
Three companies from the same screener. Open every one of the 27 undervalued companies on it →
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com