
Did Clinical Data On Furoscix ReadyFlow Just Shift MannKind (MNKD) Investment Narrative?
- MannKind Corporation recently reported new clinical data on Furoscix ReadyFlow, showing IV equivalent pharmacokinetic and pharmacodynamic performance across thigh and upper arm injection sites in heart failure and chronic kidney disease patients, with results shared at the 2026 Heart Failure Society of America meeting.
- The post hoc and crossover analyses suggest that Furoscix ReadyFlow’s 10 second autoinjector format can support outpatient fluid management while preserving bioequivalence to IV furosemide. This directly affects MannKind’s product mix, manufacturing profile and potential demand for its ready to use heart failure therapy.
- Focus now shifts to how MannKind’s investment narrative might evolve as Furoscix ReadyFlow’s IV equivalent, rapid autoinjector data gains more investor attention.
MannKind Investment Narrative Recap
To own MannKind, you need to believe the shift toward a product led model in Afrezza, Furoscix and Technosphere partnerships can eventually outweigh current losses and higher R&D and SG&A. The big near term swing factor is execution on Afrezza and Furoscix uptake, while the main risk is that elevated launch spending and negative shareholders equity drag out the path to sustained profitability.
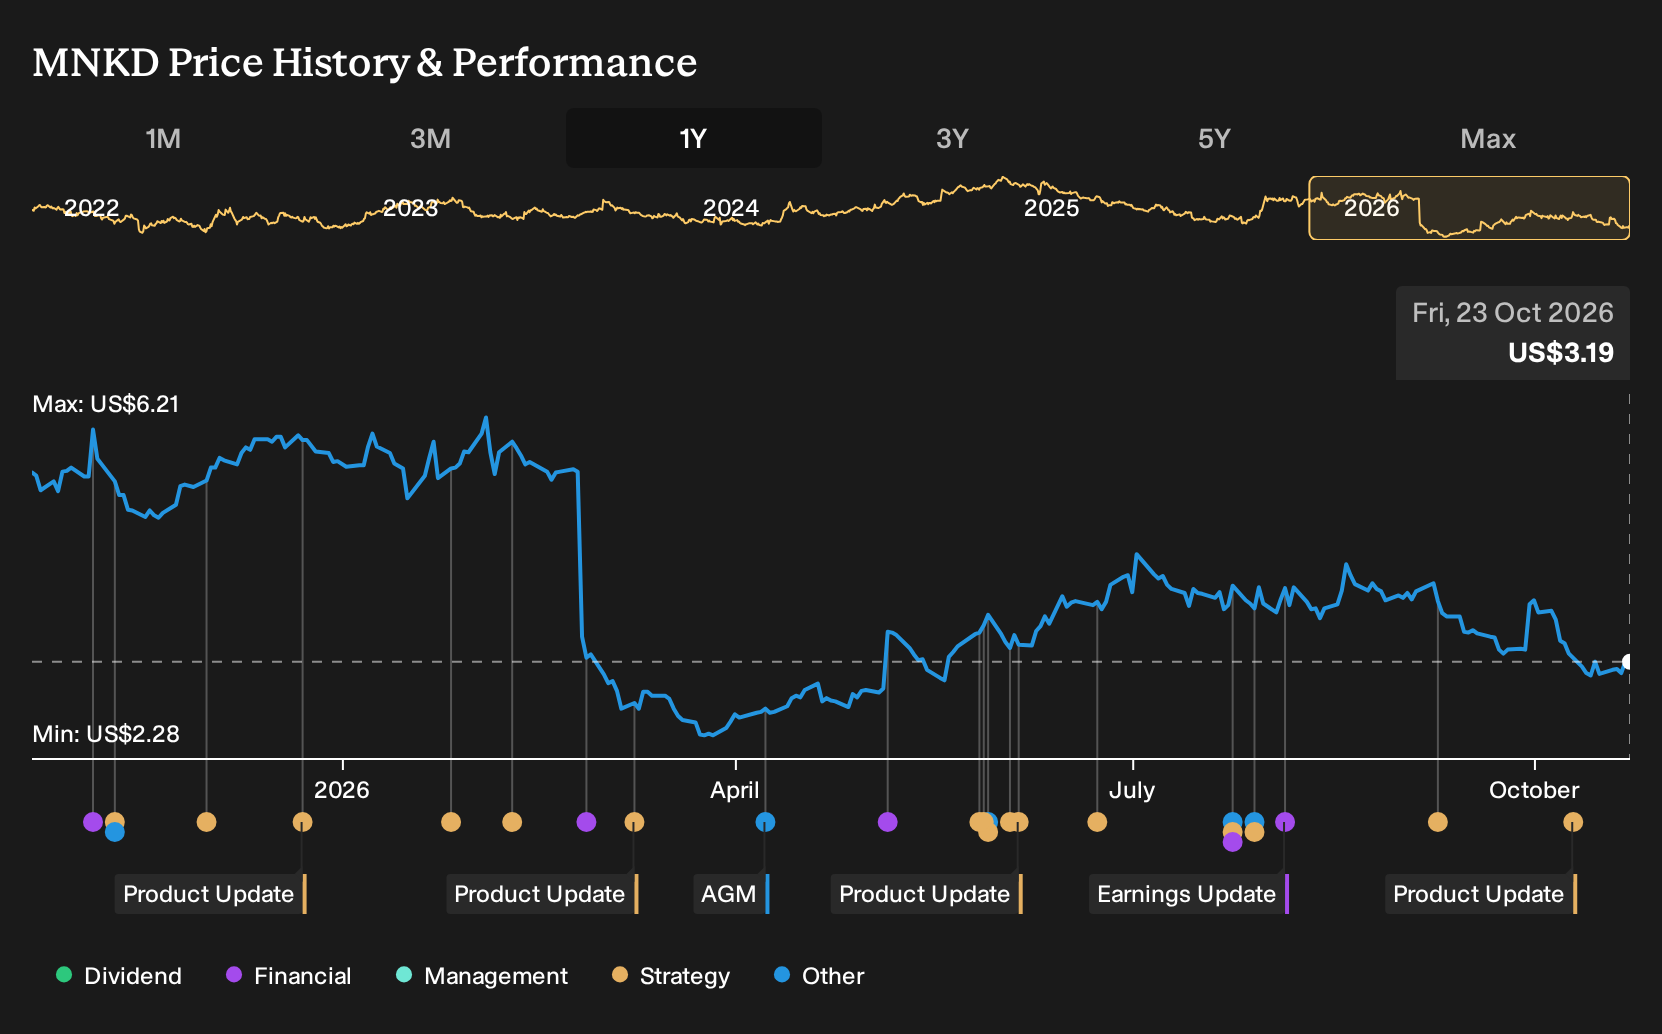
The fresh Furoscix ReadyFlow data strengthens the operational case but does not single handedly change the near term risk reward. The most important short term catalyst is still whether Afrezza pediatrics and ReadyFlow can translate into a cleaner gross margin profile. The key concern remains that owned product demand or partner revenue disappoints while costs stay high.
The July 2026 FDA approval of Furoscix ReadyFlow is the clearest bridge between MannKind’s story and this new PK and PD dataset. ReadyFlow turns Furoscix from a five hour wearable into a 10 second autoinjector, which management and analysts have framed as a way to simplify use and potentially improve manufacturing economics, both important for an outpatient heart failure product.
With the HFSA data reinforcing IV equivalent exposure and the on body infusor comparison, the operational question becomes execution. Can MannKind scale production efficiently, educate cardiologists and nephrologists, and integrate ReadyFlow into real world congestive heart failure and chronic kidney disease pathways without letting SG&A and R&D overwhelm the P&L? That execution arc is what makes upcoming quarters important catalysts for the stock.
MannKind's narrative projects US$549.9 million in revenue and US$33.5 million in earnings by 2029. This setup assumes 11.8% yearly revenue growth and an earnings improvement of about US$77.1 million from earnings today, with a US$43.6 million loss.
Discover why MannKind's fair value suggests a 150% potential upside to its current price, which could narrow quickly.
Exploring Other Perspectives
You have one clear swing factor here. Bearish analysts focus on MannKind’s higher commercial spend, with SG&A at US$58.3 million and a forecast that revenue only reaches US$480.4 million by 2029. Consensus was at US$549.9 million. Those lower forecasts came before the new ReadyFlow data, so investors may want to review both narratives as opinions develop.
Explore 2 other MannKind fair value estimates, including one that suggests it could be worth just $4.36!
The Verdict Is Yours
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your MannKind research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for MannKind. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate MannKind's overall financial health at a glance.
Looking For More Investment Ideas Beyond MannKind?
If MannKind has sharpened your focus on healthcare and higher risk, higher reward stories, it can help to line it up against a broader watchlist built with the Simply Wall St Screener.
- For investors hunting for potential future standouts at lower price points, scan through a curated set of 7 elite penny stocks with strong financials that already show stronger financial quality than typical micro caps.
- If your priority is quality at a reasonable entry point, compare MannKind against a wider pool of 27 high quality undervalued stocks that pair solid fundamentals with more attractive pricing.
- For a steadier approach that balances income with resilience, focus on a 5 dividend fortresses that concentrates on higher yielding companies with tougher balance sheet filters baked in.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com