
Should Strong Q3 Earnings Require Action From BOK Financial Stock Investors?
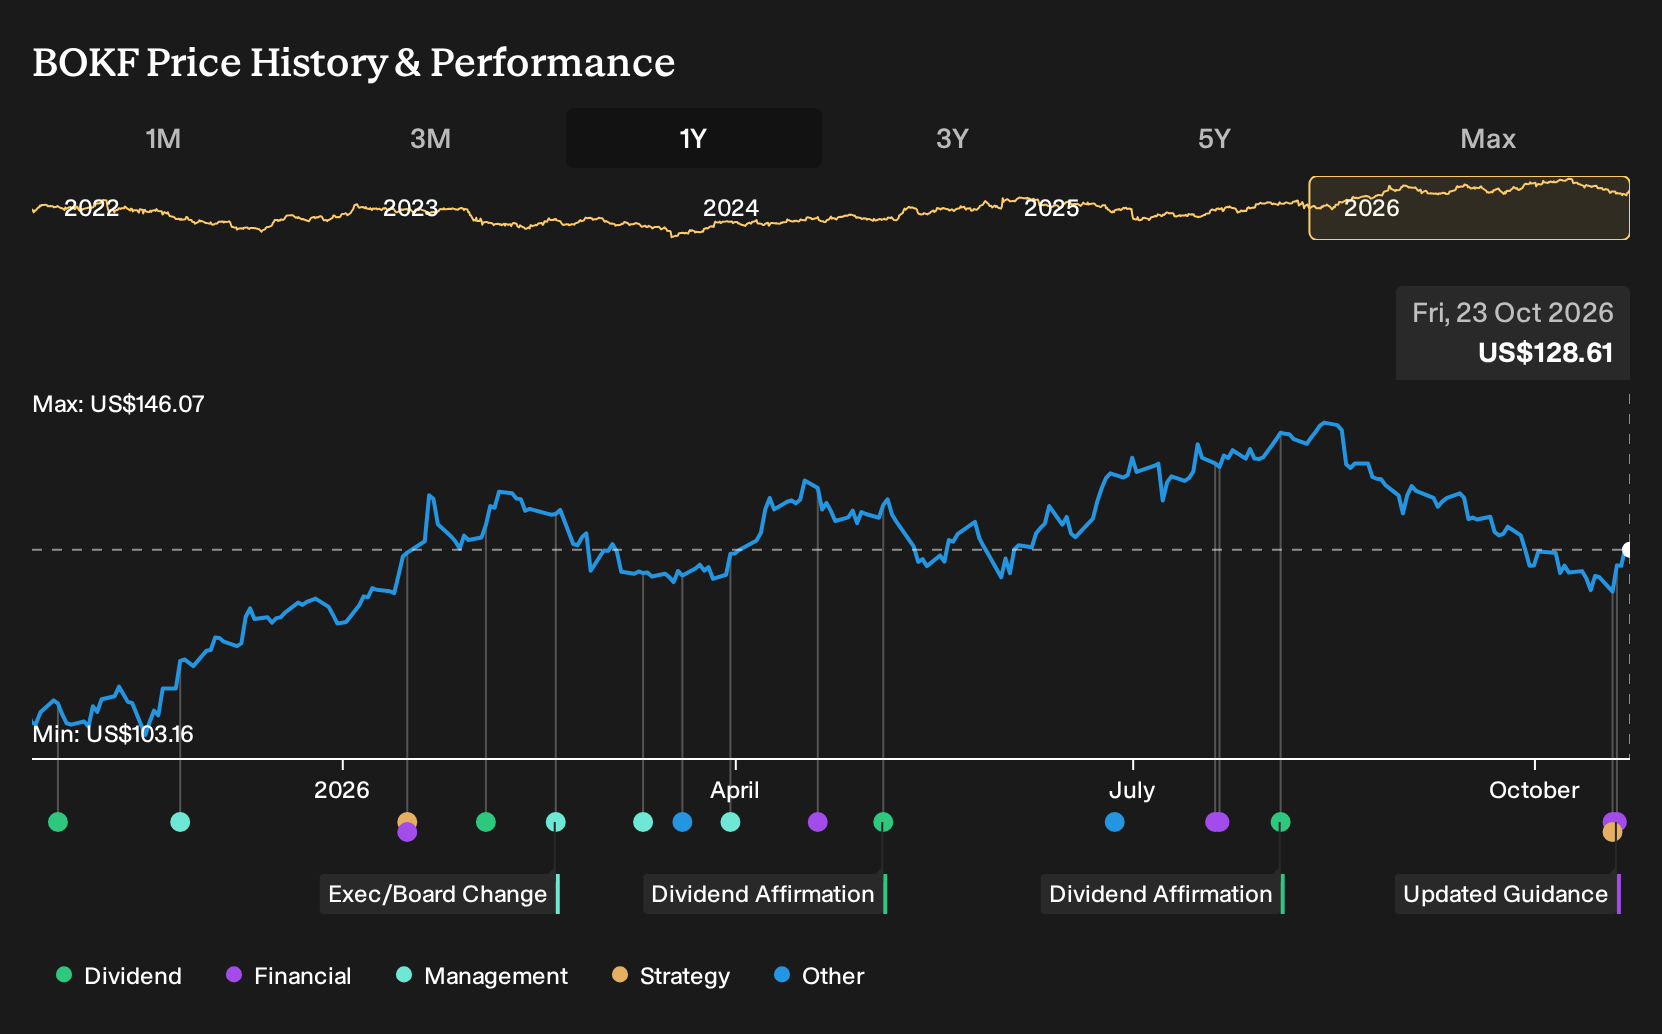
- BOK Financial reported third quarter 2026 results with higher net interest income of US$369.98 million, net income of US$159.85 million, and basic earnings per share from continuing operations of US$2.64, alongside lower net charge offs of US$886,000 compared with a year earlier.
- The company kept its 2026 full year guidance for mid single digit total revenue growth. Management highlighted strong loan growth, expanding net interest margins, and disciplined expenses supported by what it describes as exceptional credit quality.
- This article examines how BOK Financial's investment narrative is shaped by robust third quarter loan growth and reported margin strength.
Scan for other regional lenders showing similar credit discipline and earnings resilience to BOK Financial inside our hand picked 30 resilient stocks with low risk scores.
BOK Financial Investment Narrative Recap
BOK Financial appeals to investors who want a regional lender focused on steady loan growth, fee income balance, and tight credit standards. The current story leans on expanding net interest margins and quality lending, while keeping credit costs manageable. The short term swing factor is how well that margin strength holds if funding costs stay pressured or loan growth cools.
The biggest operational risk remains concentration in commercial real estate and energy, where any sector stress could change the current low loss picture. Recent results and very small net charge offs do not remove that exposure. The latest quarter looks supportive for the narrative rather than a material shift either way.
The most relevant update is management holding its 2026 outlook for mid single digit total revenue growth. Keeping guidance unchanged after reporting higher net interest income and earnings indicates that the team is framing Q3 as consistent with its existing plan, not a reset. For investors, that sets a reference point for how execution is judged over the next few quarters.
That guidance also links directly to the key catalysts analysts focus on, such as loan growth across C&I and specialty areas and the build out of the mortgage finance warehouse business. Progress on those pieces, combined with what management calls exceptional credit quality, will likely shape whether BOK Financial can keep margins firm and provisions low while dealing with fee income swings and any sector specific credit pressure.
BOK Financial's narrative projects US$2.6b revenue and US$673.8 million earnings by 2029. This assumes 4.5% yearly revenue growth and an earnings increase of about US$8.3 million from US$665.5 million today.
Uncover why BOK Financial's fair value indicates a 13% potential upside to its current price that may not last much longer.
Form Your Own Verdict
Disagree with existing narratives? Extraordinary investment returns rarely come from following the herd, so go with your instincts.
- A great starting point for your BOK Financial research is our analysis highlighting 3 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for BOK Financial. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, which makes it easy to evaluate BOK Financial's overall financial health at a glance.
Looking for more investment ideas beyond BOK Financial?
If the BOK Financial story has sharpened your thinking, put that lens to work on a wider watchlist using the Simply Wall St Screener. You can line up other banks, compare balance sheets and earnings profiles, then decide where the risk and reward mix feels most comfortable for you.
- For investors who want potential mispricings with solid fundamentals, start with companies that screen as high quality yet possibly overlooked through our 21 high quality undiscovered gems.
- If resilience matters most to you in the current cycle, narrow the field to businesses that show stronger balance sheets and financial footing using the list of solid balance sheet and fundamentals (25 results).
- Income focused readers who want yield with some cushion on risk can scan for payouts backed by sturdier profiles through the 5 dividend fortresses.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com