
Is Rayonier (RYN) Undervalued Following Its Latest Dividend Decision?
Rayonier (RYN) has set its fourth quarter cash dividend at $0.26 per share, payable on December 31, 2026, to investors on record as of December 17. That decision keeps income in focus.
Recent trading has been more subdued for Rayonier, with the share price at US$18.72 after a 30 day share price return that declined 7.51% and a year to date share price return that fell 13.37%, while the 1 year total shareholder return declined 15.38%.
Scan beyond Rayonier and compare this dividend REIT to a curated 6 dividend fortresses that have kept income front and center even as share prices have come under pressure.
Bulls point to Rayonier’s dividend and recent revenue and net income growth. Bears focus on the falling share price and softer total returns. The question is which side today’s valuation actually supports next.
Most Popular Narrative: 21% Undervalued
Rayonier’s most followed narrative pegs fair value at about $23.67, which sits well above the recent $18.72 share price and puts the focus squarely on whether the gap reflects opportunity or risk.
The current valuation implies that the market is not fully crediting Rayonier for the earnings and asset value contribution of its recent merger synergies, higher price HBU and solar land sales, and the scale of its share repurchase programme.
See why 21 investors see Rayonier as 21% undervalued.
The narrative uses a 7.94% discount rate and ties its fair value view to expectations for land conversion, timber and wood products earnings, and the impact of the PotlatchDeltic merger. It then weighs that against a mixed near term backdrop for lumber, pulpwood and real estate transactions. Analysts in that framework are modelling revenue rising to $2.0b and earnings reaching $302.1m by 2029, and they frame the current price as not fully reflecting those projected cash flows or the existing timberland and real estate portfolio.
The same storyline also flags clear pushback points for readers to consider, including softer recent profit margins at 7.8% compared with 35.3% last year, a P/E of 73.5x that screens expensive versus both peers and an estimated fair P/E of 64.7x, and a board and management bench that is relatively new with average tenures under two years. For investors weighing Rayonier today, the tension between discounted cash flow based fair value, a lower share price, and higher headline valuation multiples will likely sit at the center of any personal conclusion.
Result: Fair Value of $23.67 (UNDERVALUED)
Still, the Rayonier story can break if timber pricing stays weak or if those lumpier rural HBU and solar land deals take longer to close than expected.
Find out about the key risks to this Rayonier narrative.
Another View on Rayonier’s Valuation
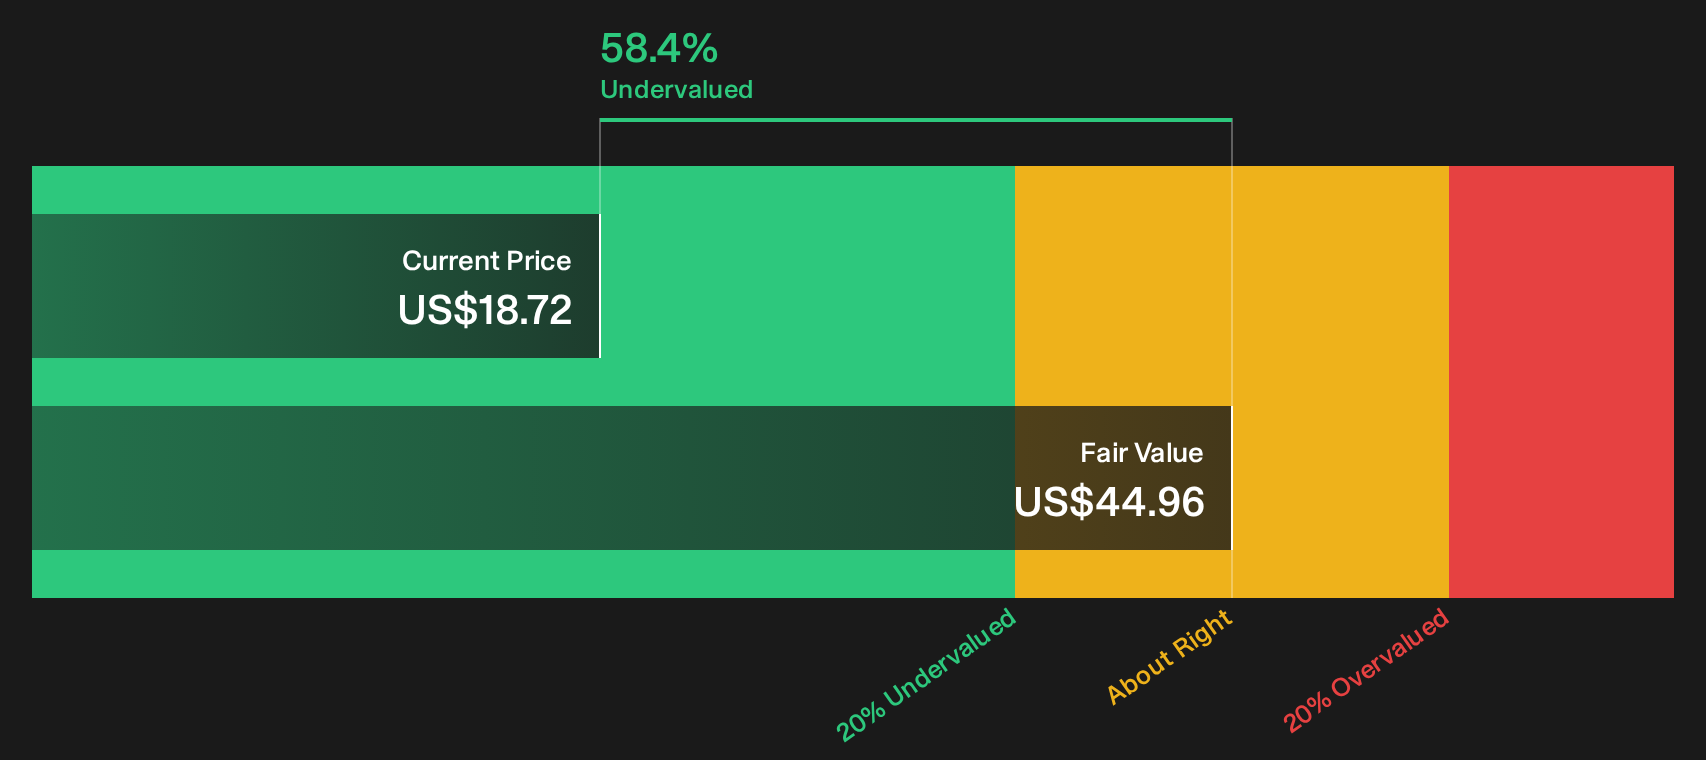
On the flip side of the discounted cash flow case that points to Rayonier trading 58.4% below an estimated $44.96 future cash flow value, the current 73.5x P/E versus a fair ratio of 64.7x suggests the stock screens expensive on earnings. Which lens feels more convincing to you right now?
To see how that earnings based view stacks up against cash flow, take a closer look at how the SWS DCF model is built for Rayonier, then weigh it against your own assumptions. Look into how the SWS DCF model arrives at its fair value.
Next Steps
Mixed signals so far or a clear leaning in your mind? Step back from the narratives, run the numbers yourself, then weigh the 2 key rewards and 4 important warning signs.
Looking for more income ideas beyond Rayonier?
If Rayonier has your attention, do not stop there. Broaden your watchlist with other dividend and quality focused opportunities that line up with your own risk and return goals.
- Target reliable income streams by scanning companies that appear in the 6 dividend fortresses and see which yields and payout records appeal most to you.
- Hunt for quality at a price that still looks reasonable by reviewing the 29 high quality undervalued stocks that pair solid fundamentals with more modest valuations.
- Prioritise resilience first by filtering for businesses on the 30 resilient stocks with low risk scores and focus your research on balance sheets that look sturdier.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com