
Earnings Beat Might Change The Case For Investing In Weatherford Stock (WFRD)
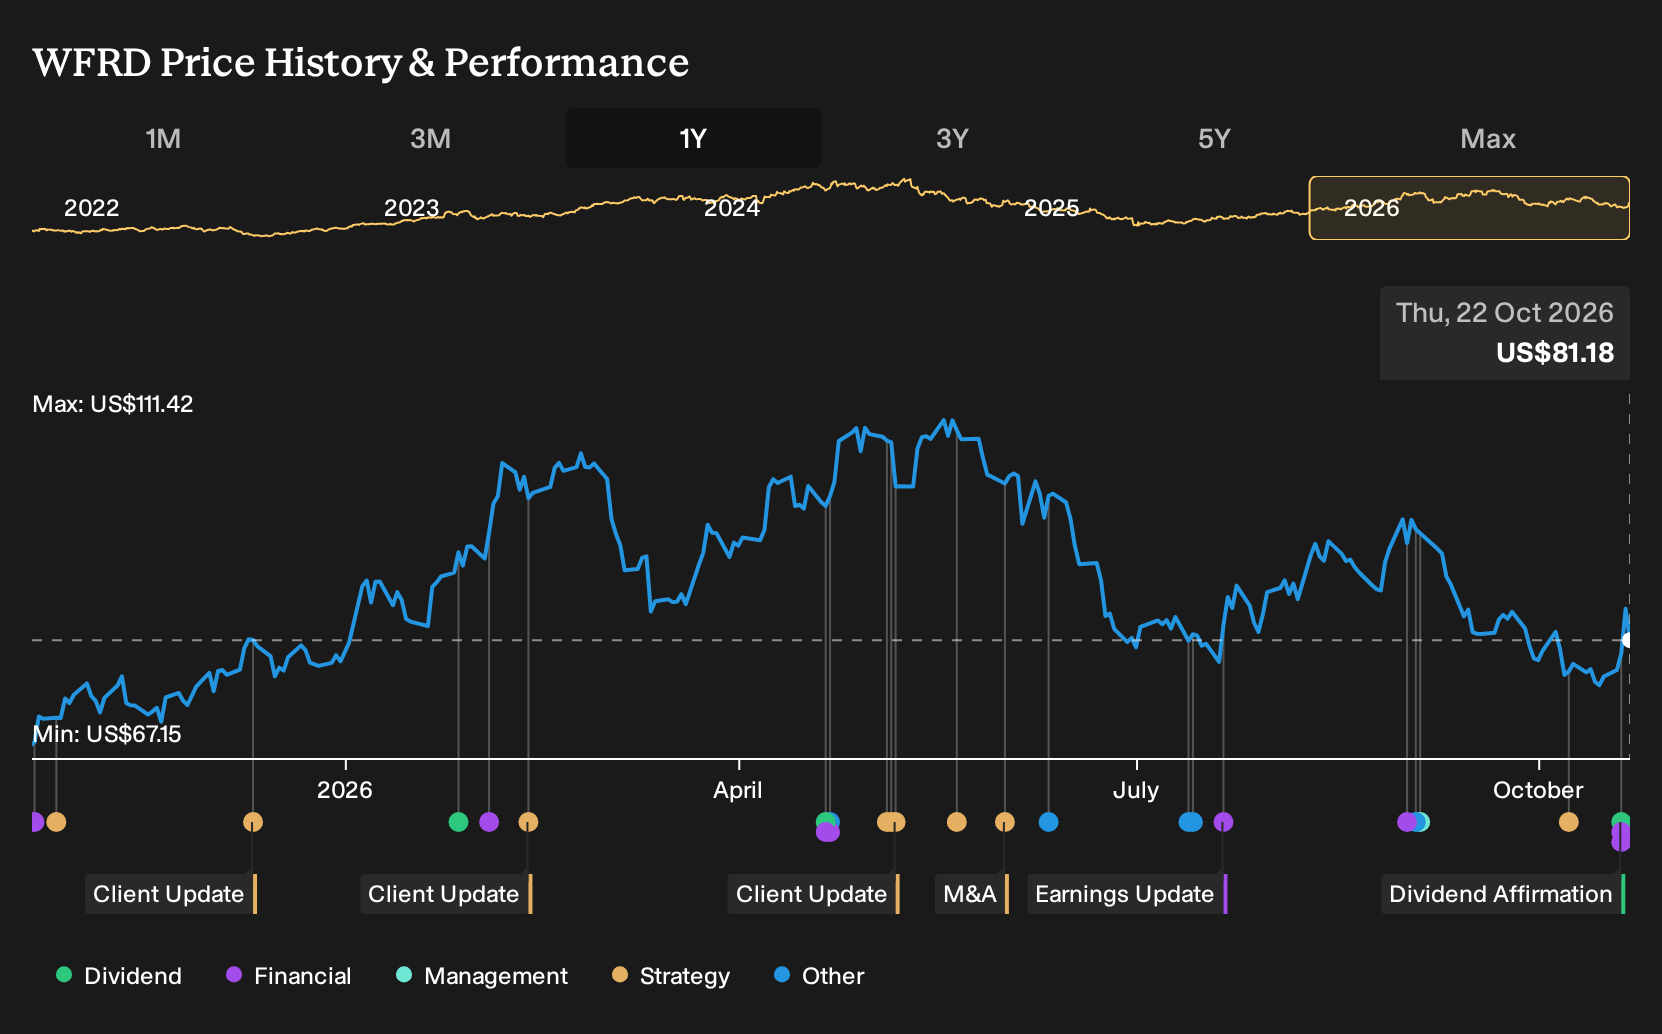
- Weatherford International reported Q3 2026 revenue of US$1,143 million, compared with US$1,232 million a year earlier. Net income reached US$120 million and basic EPS from continuing operations was US$1.66. The company also declared a US$0.275 per share dividend for payment on December 3, 2026.
- Despite lower sales versus the prior year, Weatherford International posted higher quarterly net income and strong free cash flow. Management highlighted support from margin discipline, capital light portfolio shifts, the NCS Multistage integration and a move to redeem US$236 million of 8.625% senior notes using cash on hand.
- Attention now turns to how Weatherford International's stronger than expected Q3 margins and cash generation may influence the existing investment narrative.
Scan how Weatherford International’s margin strength and debt reduction story compares with other balance sheet focused plays by reviewing our curated list of solid balance sheet and fundamentals (26 results) today.
Weatherford International Investment Narrative Recap
To own Weatherford International today, you need to believe the shift toward higher margin, capital light services and offshore work can keep supporting earnings quality even if activity in parts of the Middle East stays messy. Q3 showed that thesis at work, with strong margins and cash generation despite softer sales and regional disruptions.
The near term swing factor is execution on international and offshore projects as they move from award to full activity, while absorbing the Saudi contract roll off without too much drag on revenue and net margin. The biggest risk remains extended operational disruption or project delays in the Middle East that keep forcing guidance resets.
The decision to redeem US$236 million of 8.625% senior notes with cash on hand is the announcement that really matters for this story. Lower interest expense and a cleaner balance sheet feed directly into Weatherford International’s focus on free cash flow and give more room to keep pruning lower quality, capital heavy work.
For shareholders, that debt move tightens the link between strong Q3 free cash flow and future flexibility around portfolio choices, technology led offerings and potential capital returns. It also raises the bar on execution, because any renewed disruptions or further guidance cuts would now land against a leaner capital structure that the market is already watching closely.
What Current Forecasts Assume For Weatherford International
Weatherford International's narrative projects US$5.3b revenue and US$581.6 million earnings by 2029. This implies 3.8% yearly revenue growth and an earnings increase of about US$215.6 million from US$366.0 million today.
Uncover how Weatherford International's fair value indicates a 40% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
Some of the lowest Weatherford International forecasts lean hard into revenue risk. Before this Q3 update, the most cautious analysts were only baking in about US$5.3b of sales and roughly US$607.8 million of earnings by 2029, and pairing that with a US$93.0 fair value. That is a much tougher bar than consensus. You can use that gap to stress test your own view and see which assumptions feel closer to how you think this story might evolve after the latest earnings, debt redemption and dividend news.
Explore 5 other Weatherford International fair value estimates, including one that suggests it could be worth just $93.00.
The Verdict Is Yours
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Weatherford International research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Weatherford International. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Weatherford International's overall financial health at a glance.
Looking For More Investment Ideas Beyond Weatherford International?
If Weatherford International has sharpened your focus on balance sheets, cash generation and future potential, it can help to look across a wider field of candidates before making any decision.
- If you want potential mispricings with quality fundamentals, start by scanning our collection of 29 high quality undervalued stocks that may warrant a closer look.
- If resilience matters most to you, narrow the field with a curated pool of 30 resilient stocks with low risk scores that score well on financial strength and business stability.
- If you prefer stories that are not yet widely followed, expand your watchlist with a focused set of 20 high quality undiscovered gems that combine solid fundamentals with lower profile coverage.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com