
Exelixis (EXEL) Stock May Look Like A Bargain On FDA Review Delay
Exelixis has seen its stock price climb sharply in recent years, which puts fresh attention on whether that kind of move is supported by its earnings power today. With the shares recently closing at US$65.31 and fresh oncology news in play, the key issue for you is how much of the current price can be explained by the profits the business is generating.
- Over the past 3 years the stock has returned about 223.3%, which puts a lot of weight on the question of whether its earnings can justify that kind of rise.
- The FDA’s decision to extend review of Exelixis’ zanzalintinib combination for metastatic colorectal cancer to March 2027 may influence how investors think about the timing and durability of future profit streams from its oncology pipeline.
- There is a second opinion on Exelixis worth weighing. See what analysts think Exelixis's shares could be worth.
The stock’s next move may depend on whether the current valuation still makes sense once you line Exelixis’ share price up against its earnings.
If you are weighing Exelixis against other oncology-focused opportunities, it can help to see how similar themes play out across 36 healthcare AI stocks.
Is Exelixis a Bargain on Earnings?
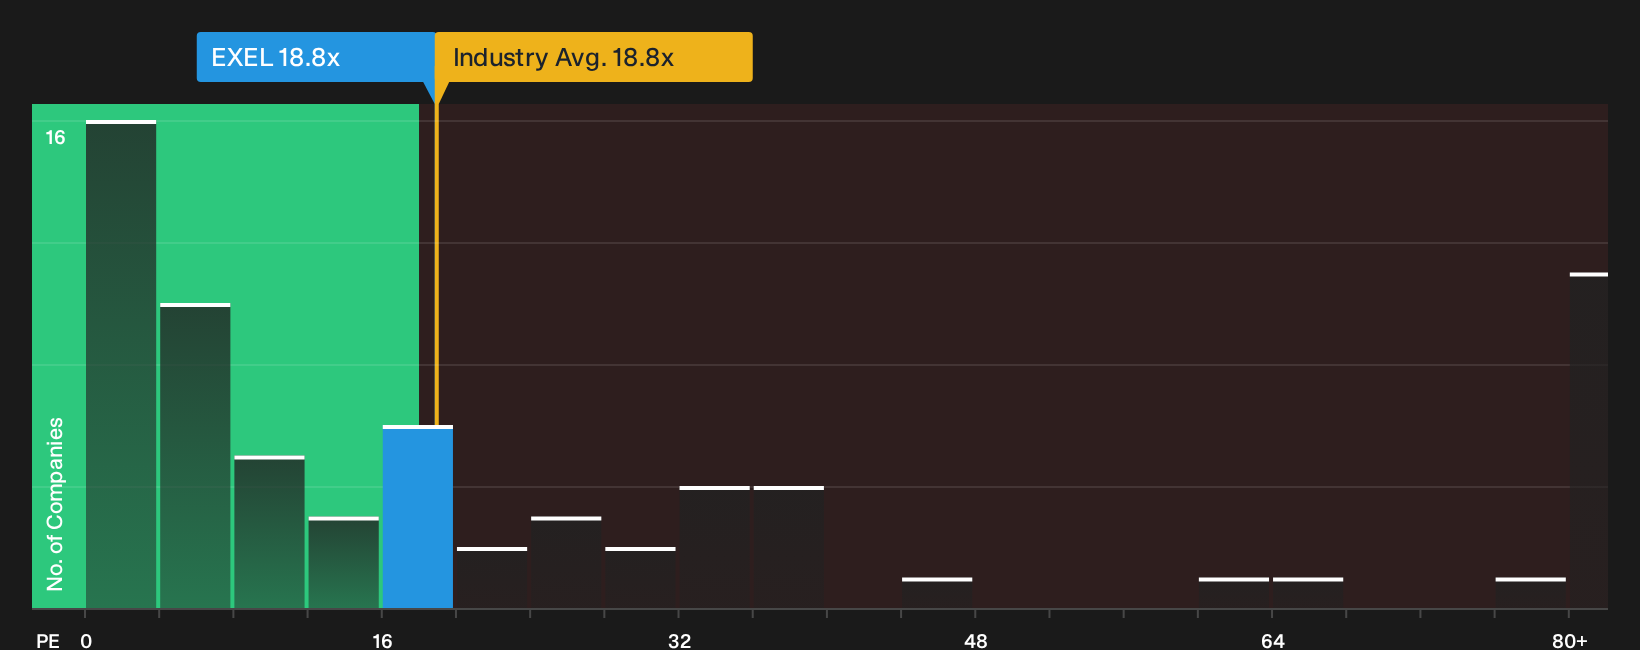
P/E suits Exelixis because you are ultimately paying for its ability to turn oncology drugs into recurring earnings. On that lens, the stock trades on a P/E of about 18.8x, which is broadly in line with the wider biotechs sector at roughly 18.8x as well, but sits well below a peer group closer to 56.0x. Because the tailored fair P/E that blends Exelixis’ growth profile, margins, size and risk points to a higher level than today’s figure, the current multiple screens as undervalued on this framework.
FDA review of the zanzalintinib combo now stretches out to March 2027, and despite that longer path the market is still pricing Exelixis at a discount to similar oncology stocks on earnings. If you think the earnings base the market is capitalising here is durable, and that the research pipeline can support it over time, this kind of P/E gap can be worth a closer look. Explore the numbers behind Exelixis's P/E valuation.
The Exelixis Narrative: What Would Justify Today's Price?
Simply Wall St Narratives pick up where the P/E puzzle for Exelixis leaves off by spelling out which paths for future growth, margins and earnings would need to play out for the stock to be worth meaningfully more or less than it is today, and they sit on the company’s Community page. Rather than a single multiple or headline model output, each one lays out the assumptions behind its fair value so you can compare those expectations with actual results as they come through.
Community views on Exelixis split between those who see more potential in the pipeline and those who think the current price already reflects a full story.
Bull case: roughly fairly valued
"The current valuation suggests the market may be treating Exelixis primarily as a cabozantinib cash generator, with limited recognition of a potential multi-franchise oncology model…"
Discover why this Narrative puts Exelixis at roughly fairly valued.
Bear case: 19% overvalued
"Cabozantinib remains the dominant revenue driver for Exelixis, so any earlier than expected loss of exclusivity or faster than expected generic erosion could lead to sharper declines…"
Explore why this Narrative puts Exelixis at 19% overvalued.
The share price is only one piece of the Exelixis story
Valuation tells you what the market is willing to pay today, but the analyst models looking a few years ahead show what expectations are already baked into Exelixis and where they might be stretched or conservative. Explore where analysts expect Exelixis to be in a few years.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com