
UniFirst (UNF) Beat On Revenue, Is Margin Pressure Limiting Fair Value?
Revenue beat and profit pressure in UniFirst’s latest quarter
UniFirst (UNF) has investors weighing a mixed Q4 2026 earnings report, with revenue ahead of market expectations while net income and earnings per share moved lower and net margin compressed.
The fourth quarter showed sales of US$645.01 million compared with US$614.45 million a year earlier. At the same time, quarterly net income came in at US$34.73 million versus US$41.03 million, with diluted earnings per share from continuing operations at US$1.90 compared with US$2.23.
Across the full fiscal year ended August 29, 2026, UniFirst reported sales of US$2.52b compared with US$2.43b in the prior year. Full year net income was US$109.49 million versus US$148.27 million, and diluted earnings per share from continuing operations were US$6.02 compared with US$7.98.
Management attributed part of the earnings pressure to costs tied to the proposed merger with Cintas Corporation and to UniFirst’s enterprise resource planning project. These spending items sit alongside organic expansion in the Uniform & Facility Service Solutions segment, which remains the core of the business.
Recent commentary from leadership has highlighted customer care, support for service teams, account management, and product placements as priorities. Those efforts align with the revenue performance, although they have not yet offset the squeeze on profitability that appeared in trailing margins.
UniFirst’s latest update landed after a strong run for the stock, with a 1-day share price return of 1.82% and a 7-day share price return of 5.35% adding to a 44.10% year to date share price gain, even though the 90-day share price return declined 5.22%.
Across a longer window, the picture has been even stronger for shareholders, with a 1-year total shareholder return of 80.05% and a 3-year total shareholder return of 77.12%. This suggests investors have been willing to look through recent margin pressure while they reassess UniFirst’s earnings resilience and the proposed Cintas merger.
Compare UniFirst’s mixed earnings story with other companies facing similar revenue strength and margin pressure by scanning the hand picked 29 high quality undervalued stocks for potential ideas.
The share price now hovers just above the average analyst target and only slightly above one intrinsic estimate. So where does fair value for UniFirst really sit after this run, and how tight is that gap?
Most Popular Narrative: 2% Overvalued
UniFirst closed at $278.99 versus a narrative fair value of $273.33, so the story now hinges on whether earnings can justify only a small premium to that estimate under a 7.24% discount rate.
The main thing that has to go right is that UniFirst converts its heavy ERP and sales and service investments, along with the planned Cintas integration, into better profitability over time despite current cost and tariff headwinds.
UniFirst’s current valuation and this narrative’s fairly valued, bullish stance together imply that the share price already reflects meaningful long term benefits from digital transformation, higher organic growth and the proposed Cintas merger synergies.
See why 2 investors see UniFirst as 2% overvalued.
Result: Fair Value of $273.33 (OVERVALUED)
Still, extended ERP spending and any setback on the proposed Cintas merger could quickly challenge the idea that UniFirst appears only 2% overvalued.
Find out about the key risks to this UniFirst narrative.
Another View: UniFirst through the SWS DCF lens
The first narrative paints UniFirst as about 2% overvalued versus a $273.33 fair value estimate, yet the SWS DCF model points in a slightly different direction. On that framework, UniFirst at $278.99 trades about 0.8% below an estimated future cash flow value of $281.20, which is a tiny margin. For investors, the real question is whether such a narrow gap leaves much room for error if the story around earnings or the Cintas deal changes.
For a closer look at how that cash flow estimate is built, you can go straight to the full breakdown in the Look into how the SWS DCF model arrives at its fair value..
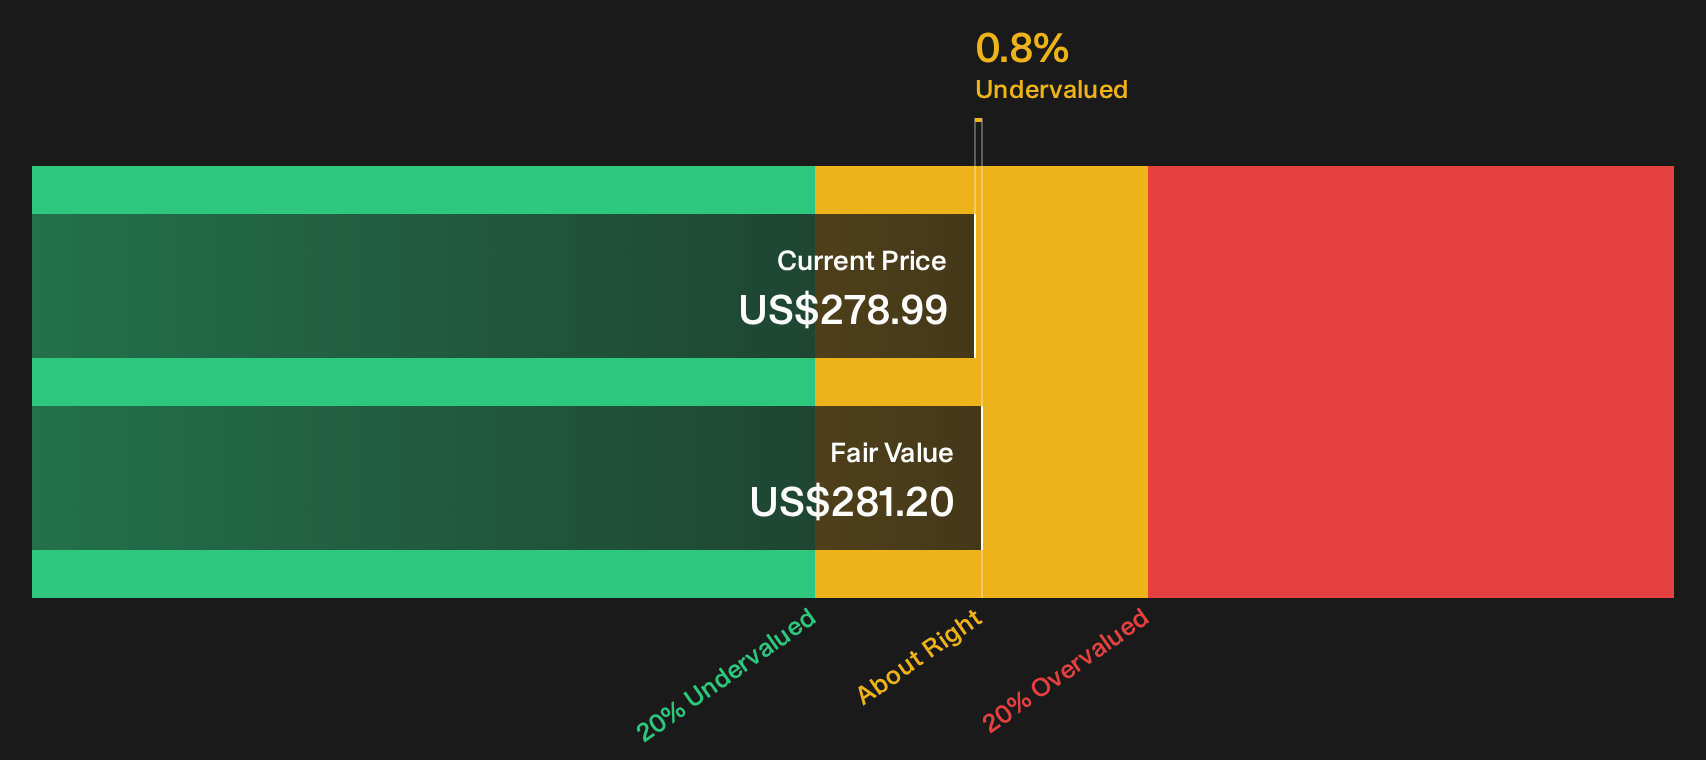
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out UniFirst for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
Mixed signals on UniFirst’s outlook can leave you torn, so act while the information is fresh and pressure test the upside yourself by reviewing the 2 key rewards.
Looking for more UniFirst investment ideas?
If UniFirst has your attention, do not stop here. Fresh opportunities often emerge where quality, income potential, and resilience quietly intersect in less crowded corners of the market.
- Target resilient balance sheets and steady fundamentals by scanning the list of solid balance sheet and fundamentals (26 results) that filters for financially grounded businesses.
- Boost your income focus by assessing the 6 dividend fortresses showcasing companies with dividend profiles that may interest cash flow oriented investors.
- Spot potential overlooked opportunities by running through the 20 high quality undiscovered gems that highlights fundamentally strong stocks flying under most radars.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com