
Is Schrödinger (SDGR) Fairly Valued Following Its Nature Battery Research?
New battery research puts Schrödinger’s platform in the spotlight
Schrödinger (SDGR) released new research, published in Nature, on lithium-ion battery electrolytes. The findings challenge long-held assumptions about how lithium ions behave in solution and highlight additional potential uses for its physics-based computational platform.
Investors have reacted cautiously to the Nature announcement, with Schrödinger’s share price falling 26.38% over the past 30 days and 11.30% over the last week, despite a 50.97% 90 day share price return and a modest 1 year total shareholder return of 2.91%. This points to fading short term momentum after a strong recent rebound.
Compare Schrödinger’s battery breakthrough with other potential movers in advanced materials by scanning the 20 high quality undiscovered gems that are still flying under most investors’ radar.
Bulls see Schrödinger’s selloff as a mismatch between its Nature-backed science and the current share price. Bears point to losses and a weak 5 year return. Which side does the valuation math support next?
Most Popular Narrative: 1% Overvalued
Schrödinger last closed at $22.60 while the most followed narrative pegs fair value at $22.29, implying a small premium that hinges on how its software and drug discovery engines convert into future cash flows under an 8.19% discount rate.
Strong pipeline advancement and early clinical success, such as positive Phase I data for SGR-1505, is cited as positioning the company to secure additional milestone payments, royalties, and out-licensing deals, which is described as creating potential for substantial long-term revenue growth and more predictable future cash flows.
See why 27 investors see Schrödinger as 1% overvalued.
Result: Fair Value of $22.29 (OVERVALUED)
Still, shrinking software margins and heavy reliance on unpredictable milestone revenue mean the Schrödinger narrative could change quickly if execution or partner demand softens.
Find out about the key risks to this Schrödinger narrative.
Another View: Schrödinger’s DCF Signal
Analyst narratives frame Schrödinger as roughly 1% overvalued around a fair value of $22.29. The SWS DCF model reaches a very different conclusion. On that framework, SDGR at $22.60 trades about 46% below an estimated future cash flow value of $41.70, which points to a wide gap in expectations.
The contrast is stark. One lens leans on near term earnings assumptions and cautious profit forecasts. The DCF view leans on longer runway cash flows instead. For investors weighing those stories, the question becomes simple: Which set of assumptions feels more realistic for Schrödinger over the coming years, and which looks too stretched?
Look into how the SWS DCF model arrives at its fair value.
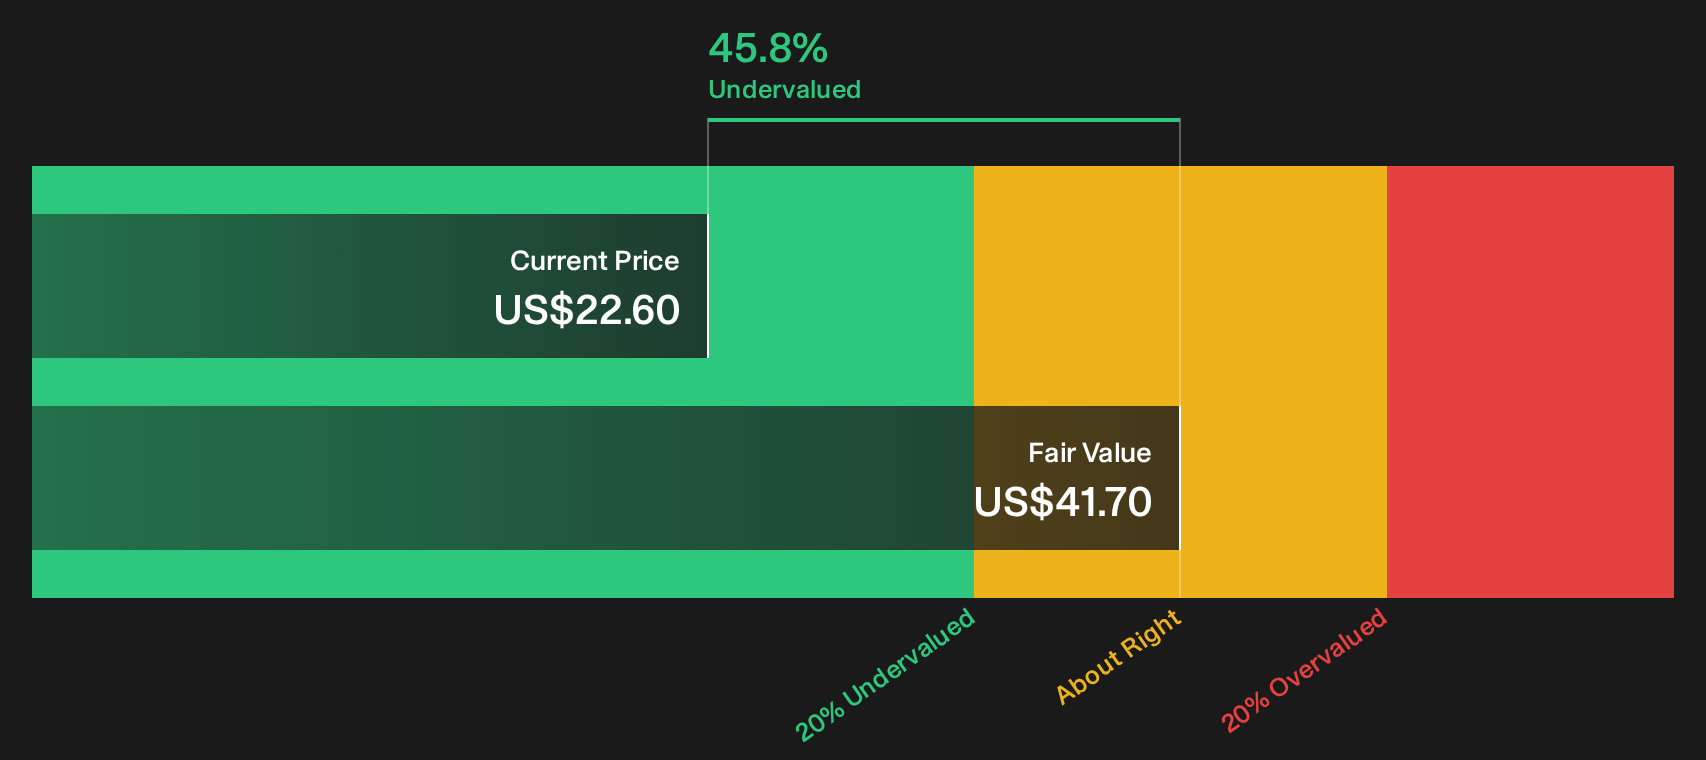
Simply Wall St performs a discounted cash flow (DCF) on every stock in the world every day (check out Schrödinger for example). We show the entire calculation in full. You can track the result in your watchlist or portfolio and be alerted when this changes, or use our stock screener to discover 29 high quality undervalued stocks. If you save a screener we even alert you when new companies match - so you never miss a potential opportunity.
Next Steps
If this mix of optimism and concern around Schrödinger feels familiar, treat it as a signal to move fast and test the data yourself. Weigh the upside case against the downside risks by starting with the 1 key reward and 3 important warning signs.
Looking for more Schrödinger investment ideas?
If Schrödinger has your attention, do not stop here. Broaden your watchlist now and give yourself more chances to spot mispriced opportunities early.
- Target quality at a discount by hunting for companies with strong fundamentals that still trade below intrinsic value through the 29 high quality undervalued stocks.
- Build a steadier income stream by focusing on payouts that look more durable than the headline yield suggests using the 6 dividend fortresses.
- Prioritize capital preservation first, then upside, by scanning companies with sturdier risk profiles through the 30 resilient stocks with low risk scores.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com