
Bath And Body Works Stock In Focus After Revenue Beat And Partnership Progress
- Bath & Body Works recently reported quarterly revenue that came in slightly above analyst expectations, despite a year-on-year decline, and paired this with softer EPS guidance for the next quarter.
- Management highlighted sequential improvement in body care, together with new product development and marketplace partnerships, as key supports for the business, even while underlying trends remain under pressure.
- Next, the focus turns to how Bath & Body Works' better-than-expected revenue shapes the existing investment narrative around its Consumer First Formula.
Scan beyond Bath & Body Works and size up other retailers showing resilient demand and balance sheet strength using the hand picked list of solid balance sheet and fundamentals (26 results).
Bath & Body Works Investment Narrative Recap
To be comfortable as a Bath & Body Works shareholder, you need to believe the Consumer First Formula can turn current category pressure into healthier, more durable demand. The latest quarter supports that thesis on revenue, which came in slightly ahead of expectations, but softer EPS guidance keeps the spotlight on near term execution rather than a clean inflection.
The key near term catalyst is whether body care and digital channels can build on the sequential improvement management pointed to, without eroding margins further as the firm invests in product and marketing. The biggest risk still sits in pressured categories and store traffic, and this update does not materially change that balance.
Among recent developments, the focus on product innovation and marketplace partnerships such as Amazon and Ulta Beauty is most relevant to this earnings update. Bath & Body Works is using these channels to reach younger and more affluent customers at higher average unit retail, which ties directly into its Consumer First Formula and category mix ambitions.
These marketplace gains, together with owned digital reacceleration and international expansion, form the practical backdrop to the current catalyst and risk mix. Execution on these avenues could help offset weaker physical store trends and high fixed costs, while any stumble in new launches or channel mix might keep gross margin and earnings pressure in focus.
Bath & Body Works Forecasts and Valuation Benchmarks
Analysts sketch a fairly specific road map for Bath & Body Works. Their models assume revenue will expand by 1.6% a year over the next three years, margins will slip from 10.8% to 9.8%, and earnings will move from US$781.0 million today to US$740.2 million by 2029, while the most cautious forecasts point to as little as US$594.9 million. On those numbers, the stock would trade on a P/E of 8.7x earnings by 2029 compared with 4.1x today, which still sits well below the cited 16.0x multiple for the broader US specialty retail peer group.
Bath & Body Works' narrative projects US$7.6b revenue and US$740.2 million earnings by 2029. This assumes 1.6% yearly revenue growth and an earnings decline of about US$40.8 million from US$781.0 million today.
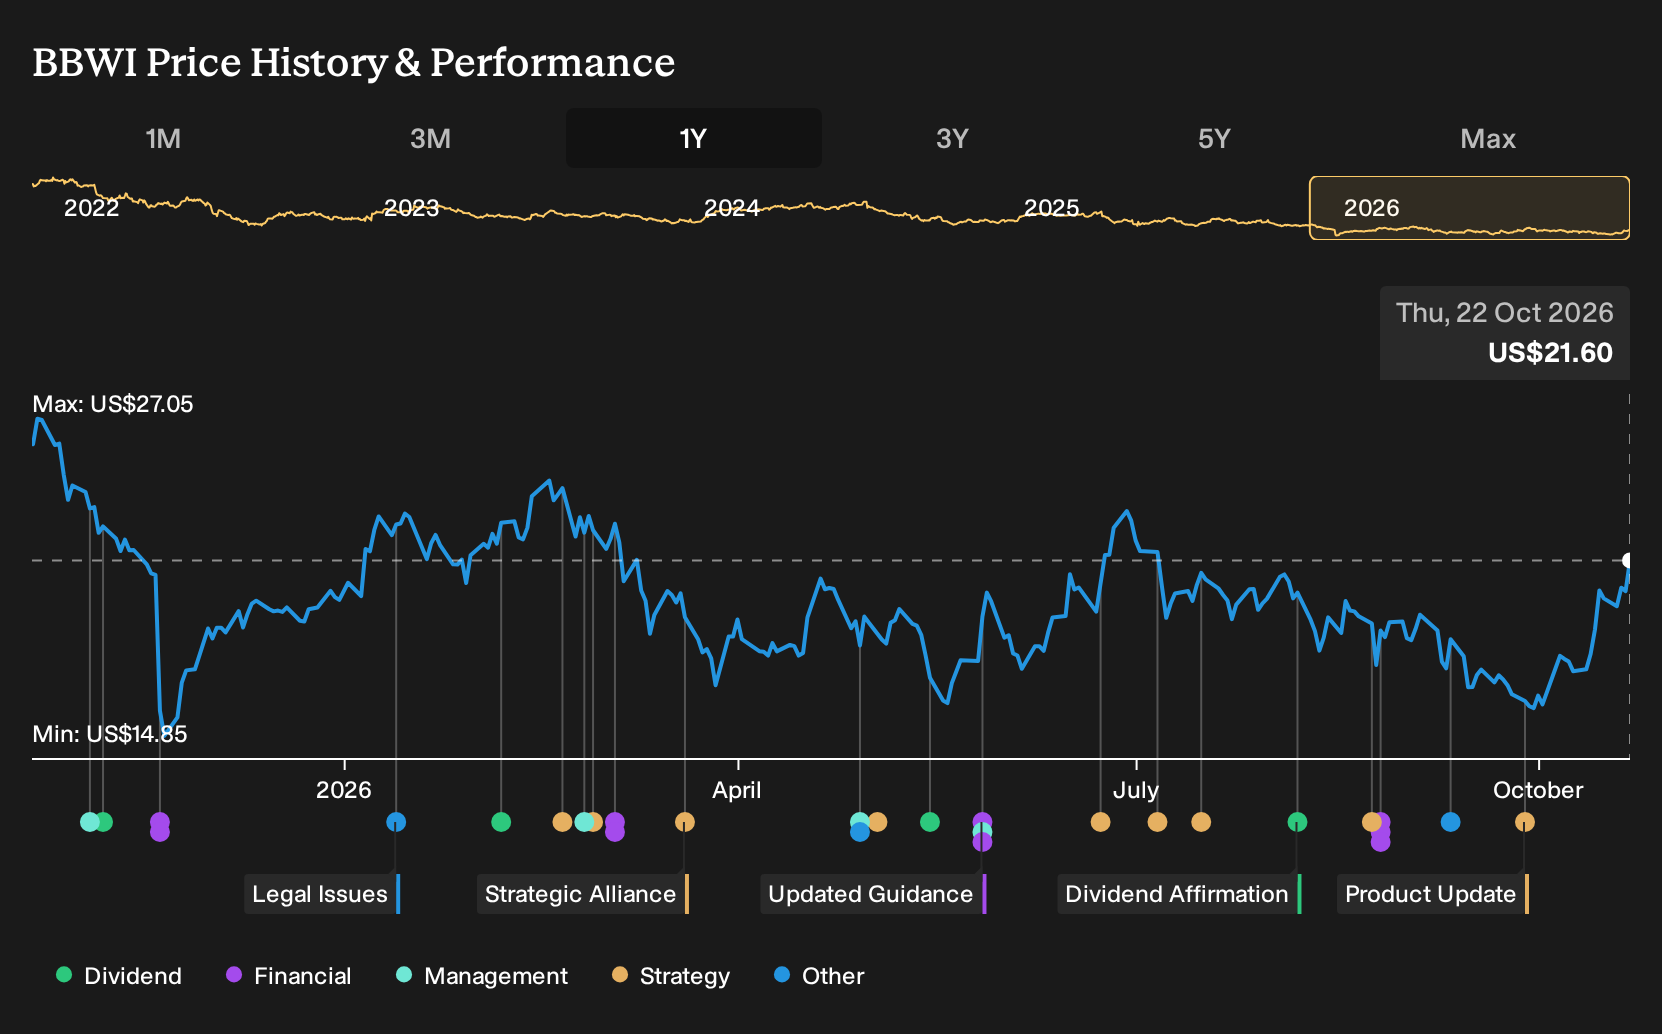
Price targets anchor that forecast in a concrete way. The consensus figure of US$24.06 sits between a bullish US$54.0 and a cautious US$17.0, with the midpoint implying the stock would need to close a 33.3% gap from the quoted US$16.06 share price as of the report date. For that scenario to line up, an investor would need to be comfortable with modest top line expansion, lower profitability than today and a higher future P/E multiple, while also accepting that analyst opinions are split on how much earnings power Bath & Body Works ultimately retains by 2029.
Uncover how Bath & Body Works' fair value indicates an 11% potential upside to its current price that could narrow quickly if sentiment improves.
Exploring Other Perspectives
One alternate view hangs on Bath & Body Works using creator led collaborations as the real swing factor. Bullish analysts already modeled revenue of about US$7.6b and earnings near US$747.6 million by 2029 before this latest beat and softer EPS guide. That is far more optimistic than consensus, and the fresh results may eventually push both stories to shift.
Explore 5 other Bath & Body Works fair value estimates, including one that suggests up to 72% upside from the current price!
Form Your Own Verdict
Don't just follow the ticker. Dig into the data and build a conviction that's truly your own.
- A great starting point for your Bath & Body Works research is our analysis highlighting 2 key rewards and 3 important warning signs that could impact your investment decision.
- See our latest analysis for Bath & Body Works. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Bath & Body Works' overall financial health at a glance.
Looking for more investment ideas beyond Bath & Body Works?
Once you have a view on Bath & Body Works, it can help to cross check that thesis against other opportunities with different risk and income profiles. The Simply Wall St Screener is a quick way to scan for stocks that match the type of balance sheet strength, return potential, or resilience you want in your portfolio.
- If capital preservation is near the top of your list, start with a curated set of resilient businesses through the 30 resilient stocks with low risk scores.
- For investors aiming to combine quality with attractive pricing, you can compare Bath & Body Works with a broader pool of candidates using the 30 high quality undervalued stocks.
- If you are hunting for future leaders that are not yet widely followed, you can broaden your opportunity set with the 20 high quality undiscovered gems.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com