
Did Capital Return Boost Just Shift Mueller Water Products' (MWA) Investment Narrative?
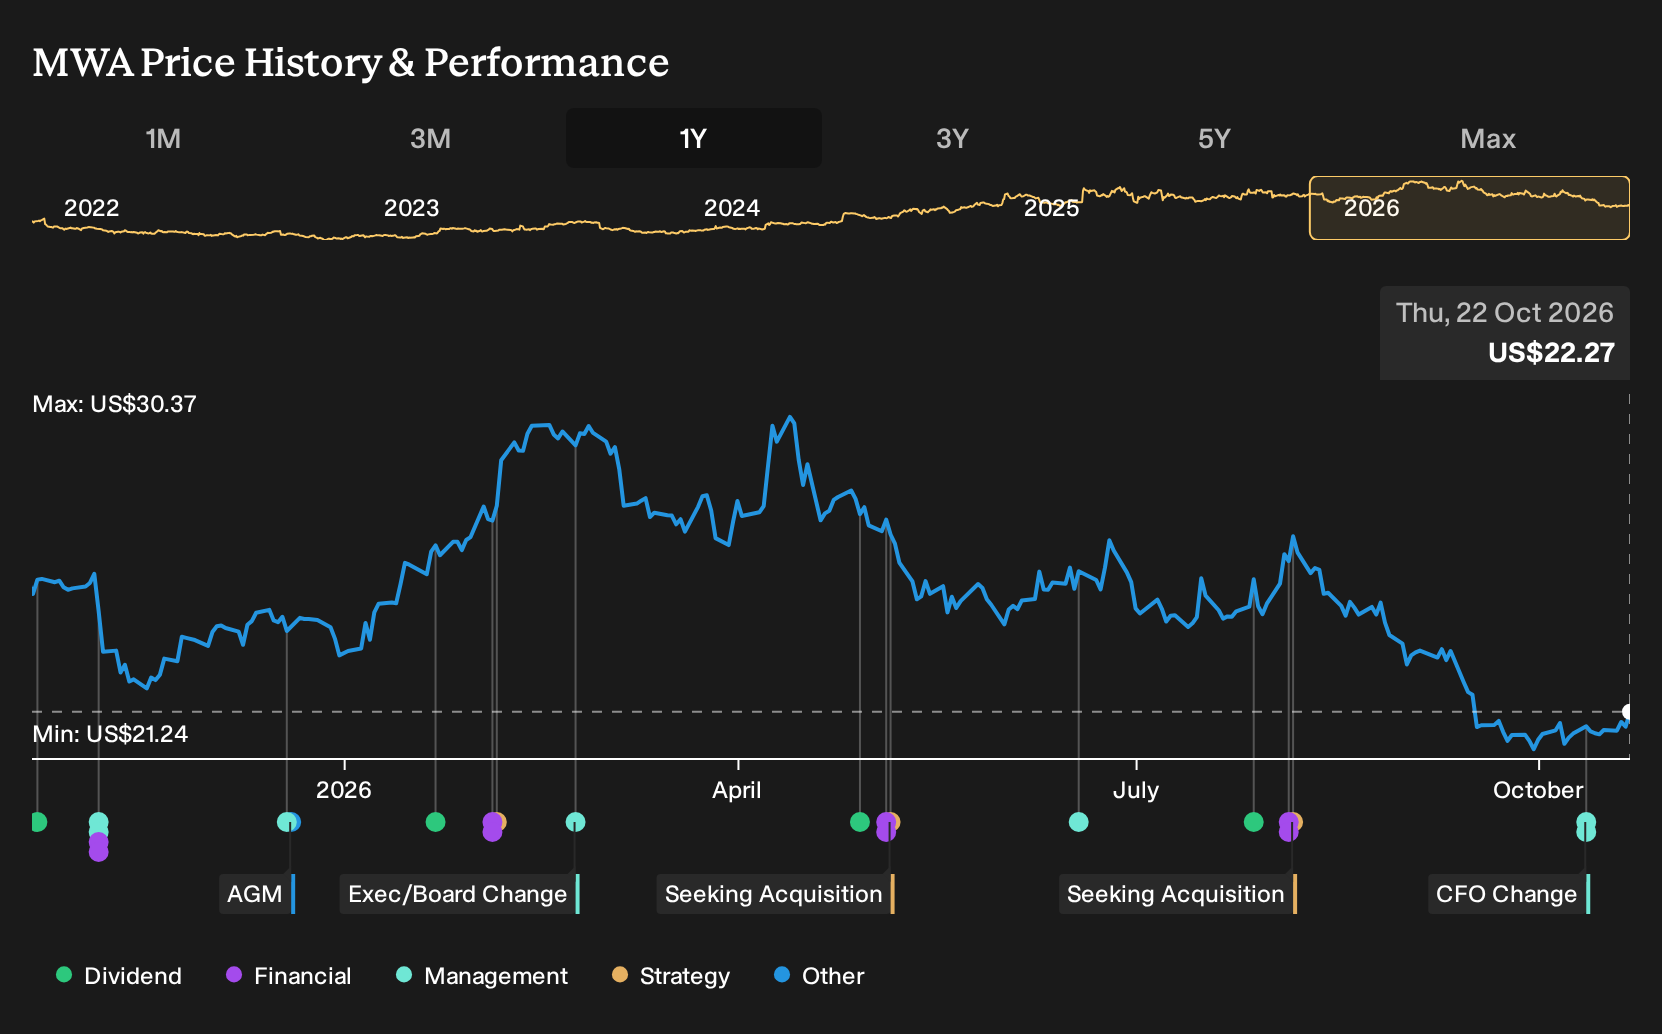
- Mueller Water Products announced a $300 million increase to its common stock repurchase authorization and a 14.3% lift in the quarterly dividend to $0.08 per share, alongside a planned CFO transition to Michael Morgan following the fiscal 2026 Form 10-K filing.
- The larger buyback pool and higher cash payout indicate that Mueller Water Products is prioritizing capital returns while retaining flexibility to fund foundry investments, water management technologies and specialty valve growth.
- We will now examine how Mueller Water Products' expanded repurchase authorization could influence the existing investment narrative around capital deployment.
Mueller Water Products Investment Narrative Recap
For a shareholder in Mueller Water Products, the core belief is pretty simple. Municipal repair and replacement work, higher value specialty valves, and water management solutions need to keep doing the heavy lifting while softer residential demand and fading stimulus are absorbed in the background. The latest dividend and buyback moves do not change that operational story in a material way.
The near term swing factor still looks like how well pricing, the Mueller Operating System and foundry investments support margins as hydrant backlogs ease and free cash flow conversion guidance remains lower. The biggest risk remains that utility spending or stimulus related demand cools faster than expected, which could pressure both revenue and cash generation.
The board’s decision to expand the stock repurchase authorization by US$300 million and lift the quarterly dividend to US$0.08 per share ties directly into those catalysts. Capital returns now sit alongside plans for 4% to 5% of sales in capex, including foundry projects and water technology build out, so execution on both sides of that equation matters.
If operations keep supporting margin quality in Water Flow Solutions and Water Management Solutions, this larger capital return program can reinforce the existing thesis that Mueller Water Products uses its balance sheet to fund both reinvestment and shareholder payouts. If hydrant normalization or weaker U.S. utility budgets hit revenue or free cash flow harder than guidance contemplates, that same program could become harder to sustain at current levels.
For this analyst view to line up, Mueller Water Products would need to reach US$1.5b in revenue and US$271.0 million in earnings by 2029. This would be built on 1.5% yearly top line growth and an earnings increase of about US$48.8 million from the current US$222.2 million base.
Uncover why Mueller Water Products' fair value indicates a 21% potential upside to its current price that could narrow quickly.
Exploring Other Perspectives
One alternate view focuses squarely on leadership risk. The most cautious analysts already treated Mueller Water Products as closer to fairly valued, even while penciling in US$1.5b of revenue and US$286.6 million of earnings by 2029. Those pre news numbers assume today’s playbook stays intact, so a new CFO could easily prompt fresh opinions.
Explore 2 other Mueller Water Products fair value estimates, including one that suggests it could be worth just $27.00!
Reach Your Own Conclusion
Don't just follow the ticker; dig into the data and build a conviction that's truly your own.
- A great starting point for your Mueller Water Products research is our analysis highlighting 4 key rewards and 1 important warning sign that could impact your investment decision.
- See our latest analysis for Mueller Water Products. The report includes a comprehensive fundamental analysis summarized in a single visual, the Snowflake, making it easy to evaluate Mueller Water Products' overall financial health at a glance.
Looking For More Investment Ideas Beyond Mueller Water Products?
If this update on Mueller Water Products sharpened your thinking on capital returns and balance sheet strength, use that same checklist to hunt for other opportunities on the Simply Wall St screener before making your next move.
- If you want potential mispricing combined with quality fundamentals, start with a curated set of 20 high quality undiscovered gems that might not yet be widely followed.
- For investors who care most about resilience through the cycle, filter for companies in our 30 resilient stocks with low risk scores and focus your attention where risk scores look more contained.
- When your priority is capital strength and financial footing, build a watchlist from the list of solid balance sheet and fundamentals (26 results) so you can compare how each business funds growth and returns cash.
Have feedback on this article? Concerned about the content? Get in touch with us directly. Alternatively, email editorial-team@simplywallst.com